
North America Alzheimer Therapeutics Market Size & Forecast:
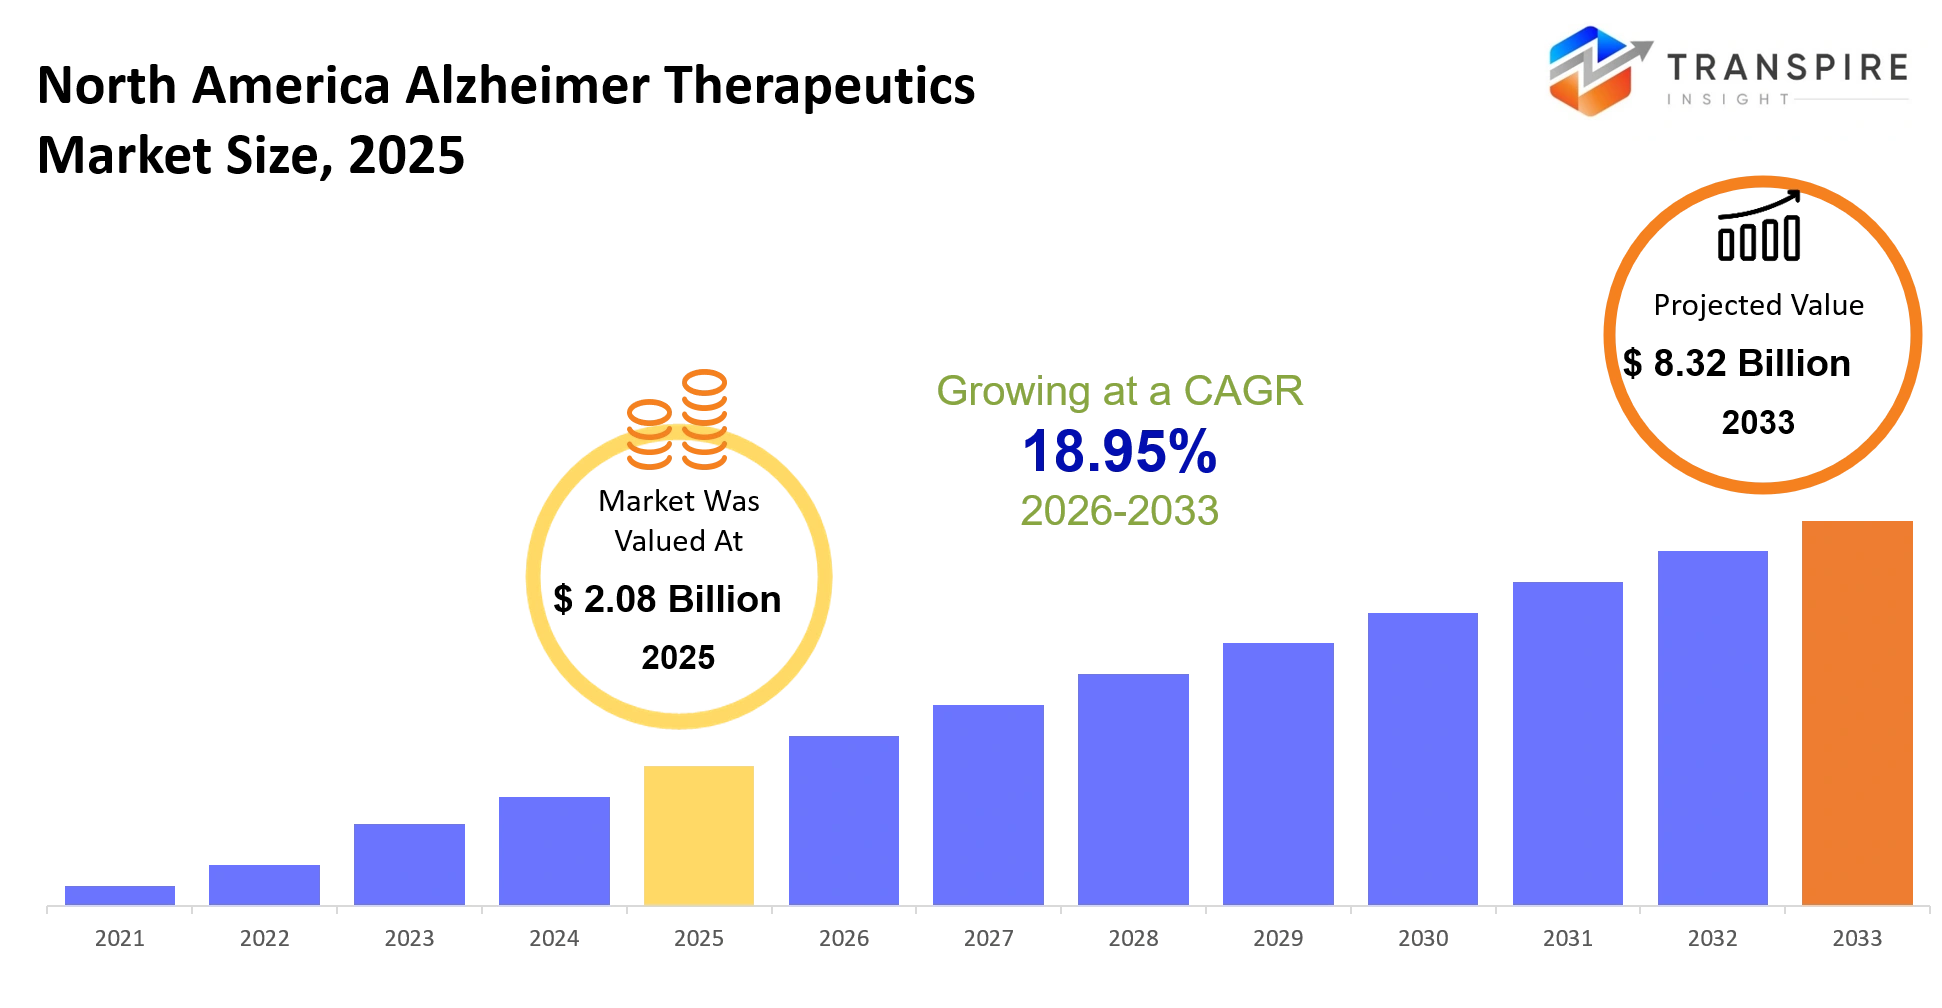
- North America Alzheimer Therapeutics Market Size 2025: USD 2.08 Billion
- North America Alzheimer Therapeutics Market Size 2033: USD 8.32 Billion
- North America Alzheimer Therapeutics Market CAGR: 18.95%
- North America Alzheimer Therapeutics Market Segments: By Drug Type (Cholinesterase Inhibitors, NMDA Receptor Antagonists, Anti-Amyloid Monoclonal Antibodies, Combination Therapies, Disease-Modifying Therapies, Symptomatic Therapies, Pipeline Therapies, Others); By Disease Stage (Mild Alzheimer's Disease, Moderate Alzheimer's Disease, Severe Alzheimer's Disease, Early-Onset Alzheimer's, Late-Onset Alzheimer's, Prodromal Alzheimer's, Mild Cognitive Impairment, Others); By Route of Administration (Oral, Intravenous, Injectable, Transdermal, Intranasal, Extended-Release Formulations, Combination Therapy, Others); By End User (Hospitals, Neurology Clinics, Long-Term Care Centers, Home Healthcare, Academic Medical Centers, Specialty Clinics, Research Institutes, Others); By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Pharmacies, Government Supply, Direct Sales, Others)
North America Alzheimer Therapeutics Market Summary
As per Transpire Insight Analysis, the North America Alzheimer Therapeutics Market was valued at USD 2.08 Billion in 2025. It is forecast to reach USD 8.32 Billion by 2033. That is a CAGR of 18.95% over the period.
In North America, the Alzheimer therapeutics market basically delivers pharmaceutical treatments that slow down symptom progression, help handle cognitive plus behavioral decline, and support longer patient independence, so that healthcare providers can reduce long term care loads while payers and public health systems are able to absorb the economic impact that comes with an aging population. Over the last three to five years, the whole market has kind of shifted in structure from symptomatic therapies to disease modifying treatments, and this has been supported by biomarker based diagnosis, which reshapes the clinical pathways and also changes investment priorities across drug development and neurological care. One big push was the COVID-19 pandemic, it disrupted clinical trials, delayed diagnoses, and it also made care delivery vulnerabilities more visible. Because of that, adoption started to accelerate for decentralized research models, digital patient monitoring, and even more streamlined regulatory engagement. These changes have then led pharmaceutical companies and healthcare organizations to lean toward earlier intervention strategies, expand diagnostic infrastructure, and firm up commercialization planning for advanced Alzheimer therapies.
Key Market Insights
- In 2025, the United States basically led the North America Alzheimer Therapeutics Market with around 88% market share, which seems fueled by advanced reimbursement frameworks and basically a wave of commercial drug launches.
- Canada meanwhile looks like the fastest moving regional market during 2025–2032, propelled by more memory clinic networks, and also broader diagnostic access that keeps widening over time .
- When it comes to offerings, disease-modifying therapies take the product segment lead with nearly 42% market share in 2025, showing stronger go-to-market momentum and a more optimistic long term market view.
- Symptomatic therapies still sit as the second-biggest slice, mainly because established prescribing habits continue backing large treatment volumes, even with competitive innovation arriving.
- Monoclonal antibody therapies are the fastest-growing segment through 2032, helped by expanded biomarker testing and earlier diagnosis that in turn speeds up commercial adoption .
- For applications, mild cognitive impairment and early stage Alzheimer's management are leading, holding about 47% market share, largely supported by earlier intervention approaches.
- Early stage disease intervention is also the fastest-growing application across the forecast period, since clinical guidance is increasingly placing more weight on treating before major cognitive decline takes hold.
- Looking at end users, hospitals and specialty neurology centers account for almost 54% market share, benefiting from infusion infrastructure, and advanced diagnostic abilities that are pretty well established.
- And specialty memory clinics emerge as the fastest-growing end-user category through 2032, because healthcare systems keep expanding dedicated neurodegenerative disease management programs.
What are the Key Drivers, Restraints, and Opportunities in the North America Alzheimer Therapeutics Market?
The main growth driver seems to be this shift toward disease-modifying therapies, that are now more supported by biomarker based diagnosis, and also updated regulatory pathways. With accelerated approvals, plus broader clinical guidance, the whole approach has moved from late-stage symptom handling to more early intervention. That shift nudges clinicians to broaden diagnostic capacity, while pharmaceutical companies put money into infusion networks, plus patient support programs. When diagnosis happens earlier, it grows the reachable treatment population. And even if the treated group is more selective, higher value therapies can still lift market revenue, kind of like offsetting the narrower reach.
Still, the biggest restraint is limited diagnostic infrastructure, and plain treatment access outside the major neurological centers. Biomarker testing, specialist coverage, and infusion capacity all need serious capital, and also trained staff. These issues can’t be fixed quickly, since healthcare workforce growth and facility investments take years. So patients end up being eligible later, and commercial uptake slows across several regions. From what I saw in the Transpire Insight review, based on regional procurement notices and launch timelines, the supply chain concentration remains the main execution risk. On top of that, manufacturing bottlenecks, and reimbursement reviews, can delay product availability, which then suppresses revenue potential and drags launch momentum a bit.
There is a big opportunity in weaving together blood based biomarkers, precision medicine, and digital cognitive testing into regular neurological care, and yes it can feel kinda “complex” at first. Together these approaches lower diagnostic complexity and help spot patients sooner, earlier identification in a more proactive way. Both public and private money going into neuroscience research keeps nudging this shift forward, even if the timelines can be a bit uneven. If real world evidence programs grow, payer confidence will likely get stronger, and reimbursement decisions can move faster. When you also consider wider specialty clinic expansion across North America, these changes are set to unlock the market's next phase of commercial growth, not just in theory but in actual uptake.
What Has the Impact of Artificial Intelligence Been on the North America Alzheimer Therapeutics Market?
Artificial intelligence is sort of reworking the regional Alzheimer therapeutics industry, mainly by making clinical development feel faster, patient identification clearer, and treatment monitoring more steady. In practice, AI algorithms can automate medical image interpretation, sort through electronic health records, and even help with compliance documentation during multicenter clinical trials, so the admin workload gets reduced and studies start running sooner. Machine learning models then do more than expected, they can also anticipate patient eligibility, disease progression, and enrollment trends, which means sponsors can tune recruitment tactics and get better trial efficiency overall.
Pharmaceutical companies are using predictive analytics more and more, to forecast therapy demand, line up manufacturing timing, and reinforce inventory planning when disease-modifying treatments move into wider commercialization. Healthcare providers, meanwhile, can lean on AI-assisted cognitive assessment tools that shorten evaluation time , while also helping keep clinical decisions more consistent. Digital platforms add another layer too, they strengthen remote patient monitoring, so earlier detection of treatment response and adverse events becomes easier, and follow-up workflows get less time consuming. With these operational changes, unnecessary clinic visits tend to drop, resources can be allocated better, and regulatory evidence generation may move quicker.
Still, broad adoption doesn’t happen automatically, it’s held back by expensive integration work, fragmented healthcare data, and interoperability that doesn’t always match between hospital information systems. On top of that, AI quality depends on diverse, high quality datasets, yet these inputs are still limited for underrepresented patient groups, and that limitation can curb model accuracy in real-world neurological care.
Key Market Trends
- Blood based biomarker testing started gaining more momentum after 2023 , which helped cut down diagnostic delays a bit and it also supported earlier choice of treatment— especially within specialized neurological centers.
- Then around 2023 to 2025, disease modifying monoclonal antibodies kind of changed the competitive map, so investment from pharma shifted toward earlier intervention plans, not just later line options.
- Regulatory agencies also moved faster with review pathways for new Alzheimer’s therapies, so commercialization timelines got shorter . That ended up nudging more neuroscience pipeline funding too, in a way.
- During 2024 and 2025, pharmaceutical companies expanded their real world evidence programs, partly so they could negotiate better with payers and back reimbursement choices more cleanly.
- Digital cognitive assessment platforms became more embedded in memory clinics over time, improving patient screening speed and making long term disease monitoring less awkward, and more consistent.
- Contract manufacturing investments increased after pandemic related disruptions , because those disruptions revealed supply chain weak spots tied to biologics production plus distribution.
- Between 2024 and 2025, Eli Lilly, Biogen, and Eisai intensified commercialization partnerships— aiming to increase infusion capacity and beef up physician education, programs that actually get used .
- Companion diagnostics adoption picked up alongside these newer therapeutics, which created tighter cooperation between diagnostic laboratories and pharmaceutical manufacturers.
- Finally , cross border clinical research collaboration between the United States and Canada broadened after 2023, helping patient recruitment and keeping multicenter trial execution moving.
North America Alzheimer Therapeutics Market Segmentation
By Drug Type :
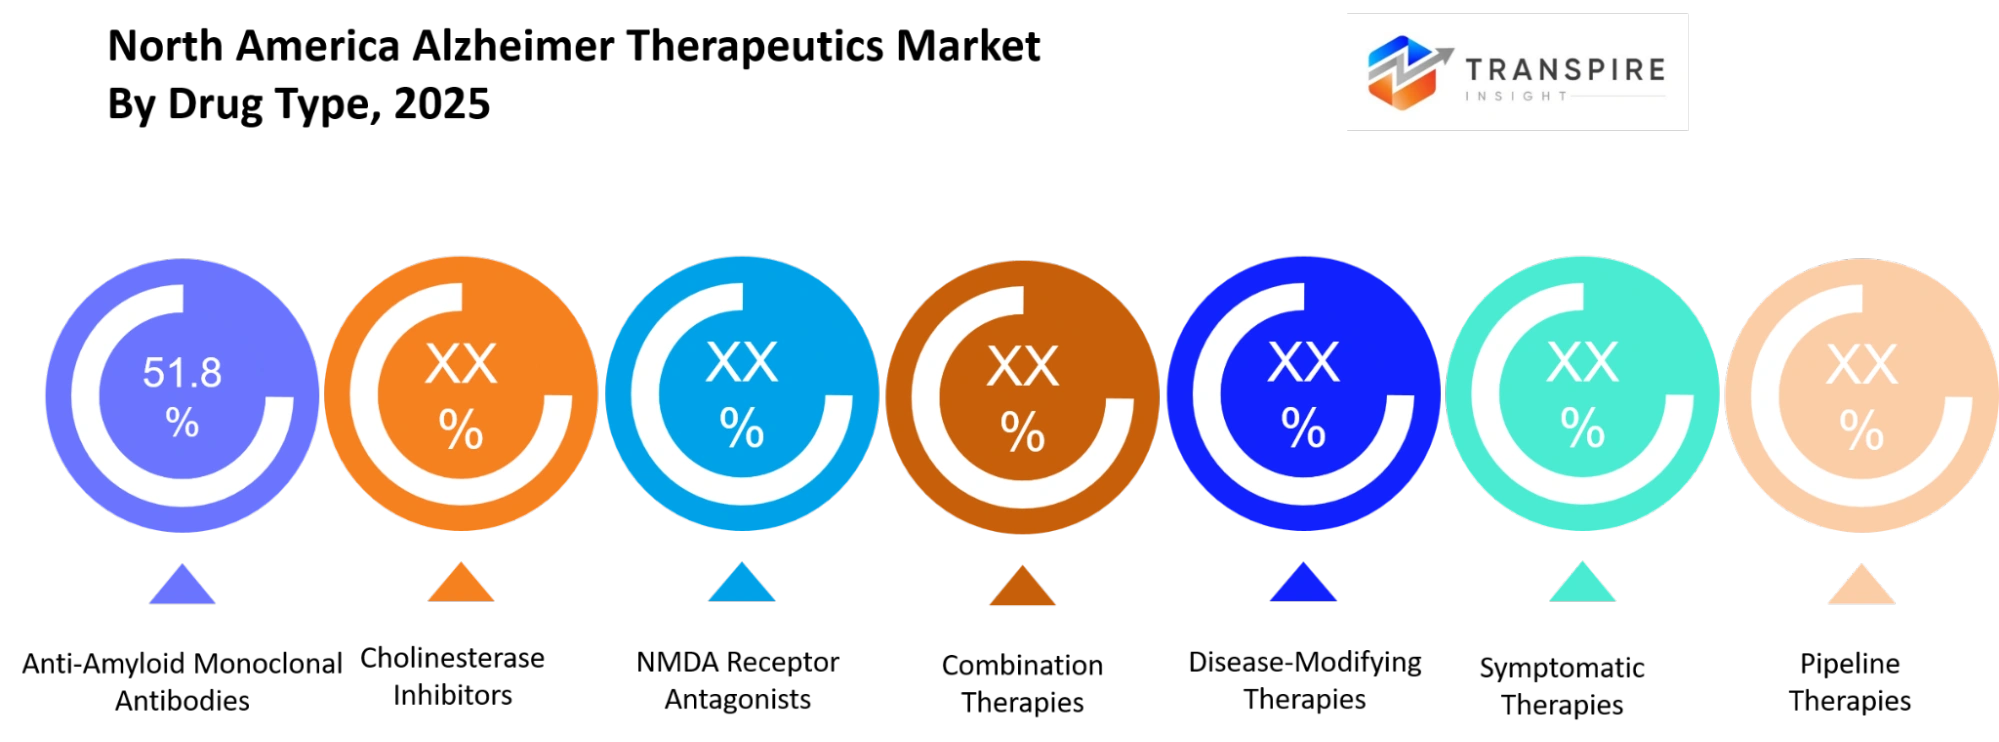
Drug development keeps drifting away from just symptom control toward treatments that try to slow the disease itself, not only manage what we see day to day. Cholinesterase inhibitors are still very common in practice, largely because they’ve been used for a long time and the treatment guidelines are pretty set in stone. NMDA receptor antagonists keep backing moderate and later disease management, and combinations also seem useful since they can cover several clinical needs at once, at least for selected patients.
Anti-amyloid monoclonal antibodies, along with disease-modifying therapies, are reshaping strategies by putting more weight on earlier disease stages. Pipeline therapies keep drawing research support as pharmaceutical companies look at new biological targets and more novel, experimental style approaches. Even so, symptomatic therapies remain a key piece of the puzzle, because many patients still need cognitive and behavioral help across different points in care. There are also other options that feed into wider clinical decisions, based on a patient’s status and what the physician recommends, in practice.
By Disease Stage :
Treatment strategies shift a bit depending on what stage the disease is in, so the chances and approaches in different clinics can look pretty varied. Mild Alzheimer’s disease gets more focus, not just because it’s common, but because an earlier diagnosis means treatment can start before major cognitive decline sets in. For moderate and severe Alzheimer’s disease, the picture stays centered on long-term therapeutic management, aiming at preserving daily function and also lowering behavioral symptoms, which is kind of a big deal over time.
Prodromal Alzheimer’s disease and mild cognitive impairment are also getting more attention lately, largely because better diagnostic tools let clinicians identify problems earlier. Early-onset Alzheimer’s disease is a smaller group of patients, though it still needs specialized clinical management, mainly because the social and economic challenges can be different, and those ripple into care decisions. Late-onset Alzheimer’s disease keeps representing the largest patient population, largely reflecting demographic trends across North America. And yeah, other disease categories remain meaningful too, especially for people who show less common clinical presentations.
By Route of Administration :
Oral therapies remain one of the top choices, mostly due to convenience , long standing prescribing practices , and simple patient familiarity. Intravenous routes have also grown, especially as newer biologic treatments get rolled out in infusion centers. Injectable products still matter a lot for those therapies that need carefully measured dosing, and also specialized clinical oversight.
Transdermal delivery can be a workable alternative when swallowing becomes difficult or when adherence starts slipping a bit. Intranasal approaches keep getting studied too, largely because they may offer a more direct path for delivery toward the brain. Extended-release formulations help streamline the dosing schedule, since patients need fewer administrations. Combination therapy strategies, meanwhile, back more individualized treatment plans, depending on the person. Other routes are still being evaluated, as product development keeps moving forward.
By End User :
Hospitals are still kinda central for diagnosis, infusion therapy, and the multidisciplinary neurological care thing. Neurology clinics keep handling the usual evaluations, treatment plans and then the long term patient tracking. Long term care centers, support patients with advanced disease who need ongoing medical supervision, and daily assistance, that part matters.
Home healthcare services are still growing too, since many healthcare systems want patients treated outside the traditional hospital space when it's clinically suitable. Academic medical centers add value via clinical research, physician mentoring, and access to innovative therapies. Specialty clinics offer more focused neurological services with advanced diagnostic abilities, and research institutes back drug discovery and later clinical development. Other healthcare facilities also get involved in patient management across wider regional care networks, so it all connects in a sorta continuous flow.
By Distribution Channel :
Hospital pharmacy services still end up doing a lot of the heavy lifting, because advanced therapies need a very careful way to be handled and it needs close coordination with the clinical teams. Regular retail pharmacies stay relevant too , especially for getting established oral medications out to patients as part of routine treatment plans. Online pharmacies keep improving prescription access via easier ordering and home delivery options, as long as the local rules allow it.
Meanwhile, specialty pharmacies handle high-value therapies which means there’s a lot more patient education needed, plus reimbursement help, and temperature controlled distribution too. Government supply routes still matter in certain public health programs, and for institutional buying. Direct sales approaches also show up, supporting more specialized products through coordinated relationships between manufacturers and healthcare providers. There are also other distribution paths that keep supporting regional healthcare systems, depending on local procurement requirements, and what treatments are actually available.
What are the Key Use Cases Driving the North America Alzheimer Therapeutics Market?
The biggest use case is basically about handling patients with mild, moderate Alzheimer’s through hospitals and neurology clinics, kinda like treating there first, and then supporting follow ups later. Healthcare systems and specialty physicians, plus whole hospital networks buy these therapies to slow cognitive decline, make clinical results better, and lower those longer-run treatment expenses by doing something earlier than before.
Then the other use cases just keep growing, especially in long-term care settings and home health services where these therapies help with continuous disease management and steadier symptom control. On top of that, academic medical centers also apply advanced treatments inside clinical research programs—those programs look at fresh therapeutic approaches and also real world patient outcomes, not just trial numbers.
What’s starting to show up more is biomarker-guided treatment selection, supported by blood based diagnostic testing, and also disease modifying therapies for people in prodromal Alzheimer’s disease stages. With regulatory backing for earlier diagnosis and precision medicine, adoption is expected to broaden across specialized neurological care through out the forecast period.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 2.08 Billion |
|
Market size value in 2026 |
USD 2.47 Billion |
|
Revenue forecast in 2033 |
USD 8.32 Billion |
|
Growth rate |
CAGR of 18.95% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
North America (Canada, The United States, and Mexico) |
|
Key company profiled |
Eisai, Biogen, Eli Lilly, Roche, Pfizer, Novartis, AbbVie, Johnson & Johnson, Otsuka Pharmaceutical, Lundbeck, Teva Pharmaceuticals, Viatris, Merz Therapeutics, Amneal Pharmaceuticals, AC Immune |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Drug Type (Cholinesterase Inhibitors, NMDA Receptor Antagonists, Anti-Amyloid Monoclonal Antibodies, Combination Therapies, Disease-Modifying Therapies, Symptomatic Therapies, Pipeline Therapies, Others); By Disease Stage (Mild Alzheimer's Disease, Moderate Alzheimer's Disease, Severe Alzheimer's Disease, Early-Onset Alzheimer's, Late-Onset Alzheimer's, Prodromal Alzheimer's, Mild Cognitive Impairment, Others); By Route of Administration (Oral, Intravenous, Injectable, Transdermal, Intranasal, Extended-Release Formulations, Combination Therapy, Others); By End User (Hospitals, Neurology Clinics, Long-Term Care Centers, Home Healthcare, Academic Medical Centers, Specialty Clinics, Research Institutes, Others); By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Pharmacies, Government Supply, Direct Sales, Others) |
Which Regions are Driving the North America Alzheimer Therapeutics Market Growth?
The United States makes up about 88% of the regional market, and it still ends up being the main driver for revenue. Clear regulatory routes, wide reimbursement coverage and a huge network of neurology care centers help speed up commercial take up of new therapies. Major global pharma, biotechnology groups, contract research organizations, and advanced biologics manufacturing facilities all together form a solid ecosystem for product development, and later commercialization. If investment keeps going into clinical research, diagnostic capabilities and disease-modifying approaches then leadership should hold steady across the 2026–2033 forecast window.
Canada comes in as the second biggest regional market, simply because healthcare delivery uses a publicly funded approach with structured reimbursement, and coordinated provincial procurement. There is steady regulatory supervision, along with fairly predictable healthcare spending, which keeps things stable for pharmaceutical suppliers even when reviews take longer. Research universities and team based clinical trial networks keep supporting therapeutic progress, while also reinforcing longer-term market steadiness. Because of those internal strengths Canada stays a dependable place for recurring revenue when manufacturers broaden across North America.
Mexico is expected to show the quickest growth during the 2026–2033 window, mainly because the healthcare infrastructure is being built out and access to neurological care is getting better. There was recent capital going into specialty hospitals, diagnostic capabilities, and pharmaceutical distribution, and this has really helped reinforce the groundwork for more wide ranging treatment availability. If healthcare services keep getting modernized and access to new innovative medicines keeps expanding, it should generate fresh commercial openings across both public and private healthcare systems. All this momentum will end up giving pharmaceutical companies and investors some attractive entry points if they are looking for long term expansion beyond the region’s already established markets .
Who are the Key Players in the North America Alzheimer Therapeutics Market and How Do They Compete?
Competition stays fairly consolidated, because advanced biologic development really needs big research investment , specialized manufacturing, and a lot of clinical proof. In other words, it is not mainly a price game. Technology innovation, solid neuroscience pipelines, and regulatory execution are the main levers. Existing pharmaceutical firms keep safeguarding market share via continuous research spending, while biotechnology companies bring forward novel therapeutic approaches that tend to unsettle the older treatment playbooks a bit.
Eli Lilly leans into disease-modifying therapies, with large-scale clinical development and commercialization programs behind them. Their strong push for biomarker-led treatment strategies and manufacturing capacity helps widen product availability once regulatory approvals land. Biogen, on the other hand, differentiates through deep neuroscience know-how and strategic collaborations, which end up reinforcing development efforts, commercialization reach, and even physician education across neurological care networks. Eisai expands its market presence by using global development partnerships that blend clinical evidence with coordinated launch tactics, especially for innovative Alzheimer’s treatments.
Roche builds competitive power by using advanced diagnostic technologies that, kind of support therapeutic research and make precision medicine approaches work better. When biomarker capabilities are integrated with neuroscience development it creates a more distinct footing across diagnostic pathways and treatment planning, even if it’s not perfectly straightforward all the time. Meanwhile Pfizer keeps putting money into neuroscience research partnerships and targeted pipeline expansion, aiming to uncover next potential therapeutic options while also boosting long term inventive capability across neurodegenerative disease programs.
Company List
- Eisai
- Biogen
- Eli Lilly
- Roche
- Pfizer
- Novartis
- AbbVie
- Johnson & Johnson
- Otsuka Pharmaceutical
- Lundbeck
- Teva Pharmaceuticals
- Viatris
- Merz Therapeutics
- Amneal Pharmaceuticals
- AC Immune
Recent Development News
In May 2026, Sanofi agreed to acquire Vigil Neuroscience for up to US$470 million. The acquisition strengthens Sanofi's neurology pipeline by adding the Alzheimer's disease candidate VG-3927, reinforcing competitive investment in disease-modifying therapeutics for the North American Alzheimer's market. Sourcehttps://www.reuters.com/
In July 2025, Acumen Pharmaceuticals entered into a strategic collaboration, option and license agreement with JCR Pharmaceuticals to develop Enhanced Brain Delivery™ therapies for Alzheimer's disease. The partnership combines Acumen's amyloid beta oligomer-targeting expertise with JCR's blood-brain barrier delivery technology, aiming to accelerate next-generation Alzheimer's therapeutics with improved brain penetration.
Source https://investors.acumenpharm.com/
What Strategic Insights Define the Future of the North America Alzheimer Therapeutics Market?
Over the next five to seven years, the North America Alzheimer Therapeutics Market is expected to, kind of transition from symptomatic disease management into precision and also disease modifying care, mostly pushed by improvements in biomarker guided diagnosis, earlier intervention approaches, and wider integration of anti amyloid and emerging neuroprotective treatments into day to day clinical practice. A less visible risk is, the increasing concentration of commercial wins among a small set of high cost biologics, which creates reimbursement pressure and can leave the market exposed to regulatory or payer driven limits if long term real world results do not really prove the treatment value.
An interesting opportunity is in blood based biomarker platforms that can support more scalable patient identification and speed up therapeutic adoption beyond specialized memory centers. Market participants should focus on partnerships that blend therapeutics with companion diagnostics and real world evidence readiness , because that helps position their offerings for value based reimbursement models and also expand access through community healthcare settings.
North America Alzheimer Therapeutics Market Report Segmentation
By Drug Type
- Cholinesterase Inhibitors
- NMDA Receptor Antagonists
- Anti-Amyloid Monoclonal Antibodies
- Combination Therapies
- Disease-Modifying Therapies
- Symptomatic Therapies
- Pipeline Therapies
By Disease Stage
- Mild Alzheimer's Disease
- Moderate Alzheimer's Disease
- Severe Alzheimer's Disease
- Early-Onset Alzheimer's
- Late-Onset Alzheimer's
- Prodromal Alzheimer's
- Mild Cognitive Impairment
By Route of Administration
- Oral
- Intravenous
- Injectable
- Transdermal
- Intranasal
- Extended-Release Formulations
- Combination Therapy
By End User
- Hospitals
- Neurology Clinics
- Long-Term Care Centers
- Home Healthcare
- Academic Medical Centers
- Specialty Clinics
- Research Institutes
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Specialty Pharmacies
- Government Supply
- Direct Sales
Frequently Asked Questions
Find quick answers to common questions.
The expected North America Alzheimer Therapeutics Market size for the market will be USD 8.32 Billion in 2033.
Key segments for the North America Alzheimer Therapeutics Market are Type By Drug Type (Cholinesterase Inhibitors, NMDA Receptor Antagonists, Anti-Amyloid Monoclonal Antibodies, Combination Therapies, Disease-Modifying Therapies, Symptomatic Therapies, Pipeline Therapies, Others); By Disease Stage (Mild Alzheimer's Disease, Moderate Alzheimer's Disease, Severe Alzheimer's Disease, Early-Onset Alzheimer's, Late-Onset Alzheimer's, Prodromal Alzheimer's, Mild Cognitive Impairment, Others); By Route of Administration (Oral, Intravenous, Injectable, Transdermal, Intranasal, Extended-Release Formulations, Combination Therapy, Others); By End User (Hospitals, Neurology Clinics, Long-Term Care Centers, Home Healthcare, Academic Medical Centers, Specialty Clinics, Research Institutes, Others); By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies, Specialty Pharmacies, Government Supply, Direct Sales, Others).
Major North America Alzheimer Therapeutics Market players are Eisai, Biogen, Eli Lilly, Roche, Pfizer, Novartis, AbbVie, Johnson & Johnson, Otsuka Pharmaceutical, Lundbeck, Teva Pharmaceuticals, Viatris, Merz Therapeutics, Amneal Pharmaceuticals, AC Immune.
The North America Alzheimer Therapeutics Market size is USD 2.08 Billion in 2025.
The North America Alzheimer Therapeutics Market CAGR is 18.95% from 2026 to 2033.
- Eisai
- Biogen
- Eli Lilly
- Roche
- Pfizer
- Novartis
- AbbVie
- Johnson & Johnson
- Otsuka Pharmaceutical
- Lundbeck
- Teva Pharmaceuticals
- Viatris
- Merz Therapeutics
- Amneal Pharmaceuticals
- AC Immune
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Jul 2026
Alopecia Treatment Market
Alopecia Treatment Market Size, Share & Analysis Report By Disease Type (Alopecia Areata, Cicatricial Alopecia, Traction Alopecia, Alopecia Totalis, Androgenetic Alopecia, Alopecia Universalis, and Other Disease Types), By Treatment Type (Topical Treatments, Oral Medications, Injectable Therapies, and Hair Transplantation), By Gender (Male, and Female), By Distribution Channel (Hospitals and Clinics, Retail Pharmacies, and Online Retailers), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Jul 2026
Medical Ultrasound Probe Market
Medical Ultrasound Probe Market Size, Share & Analysis Report By Type (Linear Type, Convex Type, Endocavitary Probe, Phased Array/Cardiac Probe, Transesophageal (TEE) Probe, and Others), By Application (Ophthalmology, Cardiology, Musculoskeletal, Oncology, Obstetrics & Gynecology, General Imaging, and Others), By End User (Hospitals & Clinics, Diagnostic Centers, Ambulatory Surgical Centers, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
May 2026
Biosimilars Market
Biosimilars Market By Product Type (Monoclonal Antibodies, Recombinant Hormones, Erythropoietin, G-CSF, Others), By Indication (Oncology, Autoimmune Diseases, Blood Disorders, Diabetes, Others), By Manufacturing Type (In-House Manufacturing, Contract Manufacturing), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033
-
Apr 2026
Gastrointestinal Endoscopy Market
Gastrointestinal Endoscopy Market By Type (Rigid Gastrointestinal Endoscope, Flexible Gastrointestinal Endoscopes, Disposable Gastrointestinal Endoscope), By Procedure Type (Colonoscopy, Gastroscopy, Duodenoscopy, Enteroscopy, Flexible Sigmoidoscopy, Others), By Application (Diagnosis, Treatment), By End-Users (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Laboratories, Others), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033