
North America Esophageal Cancer Therapeutics Market Size & Forecast:
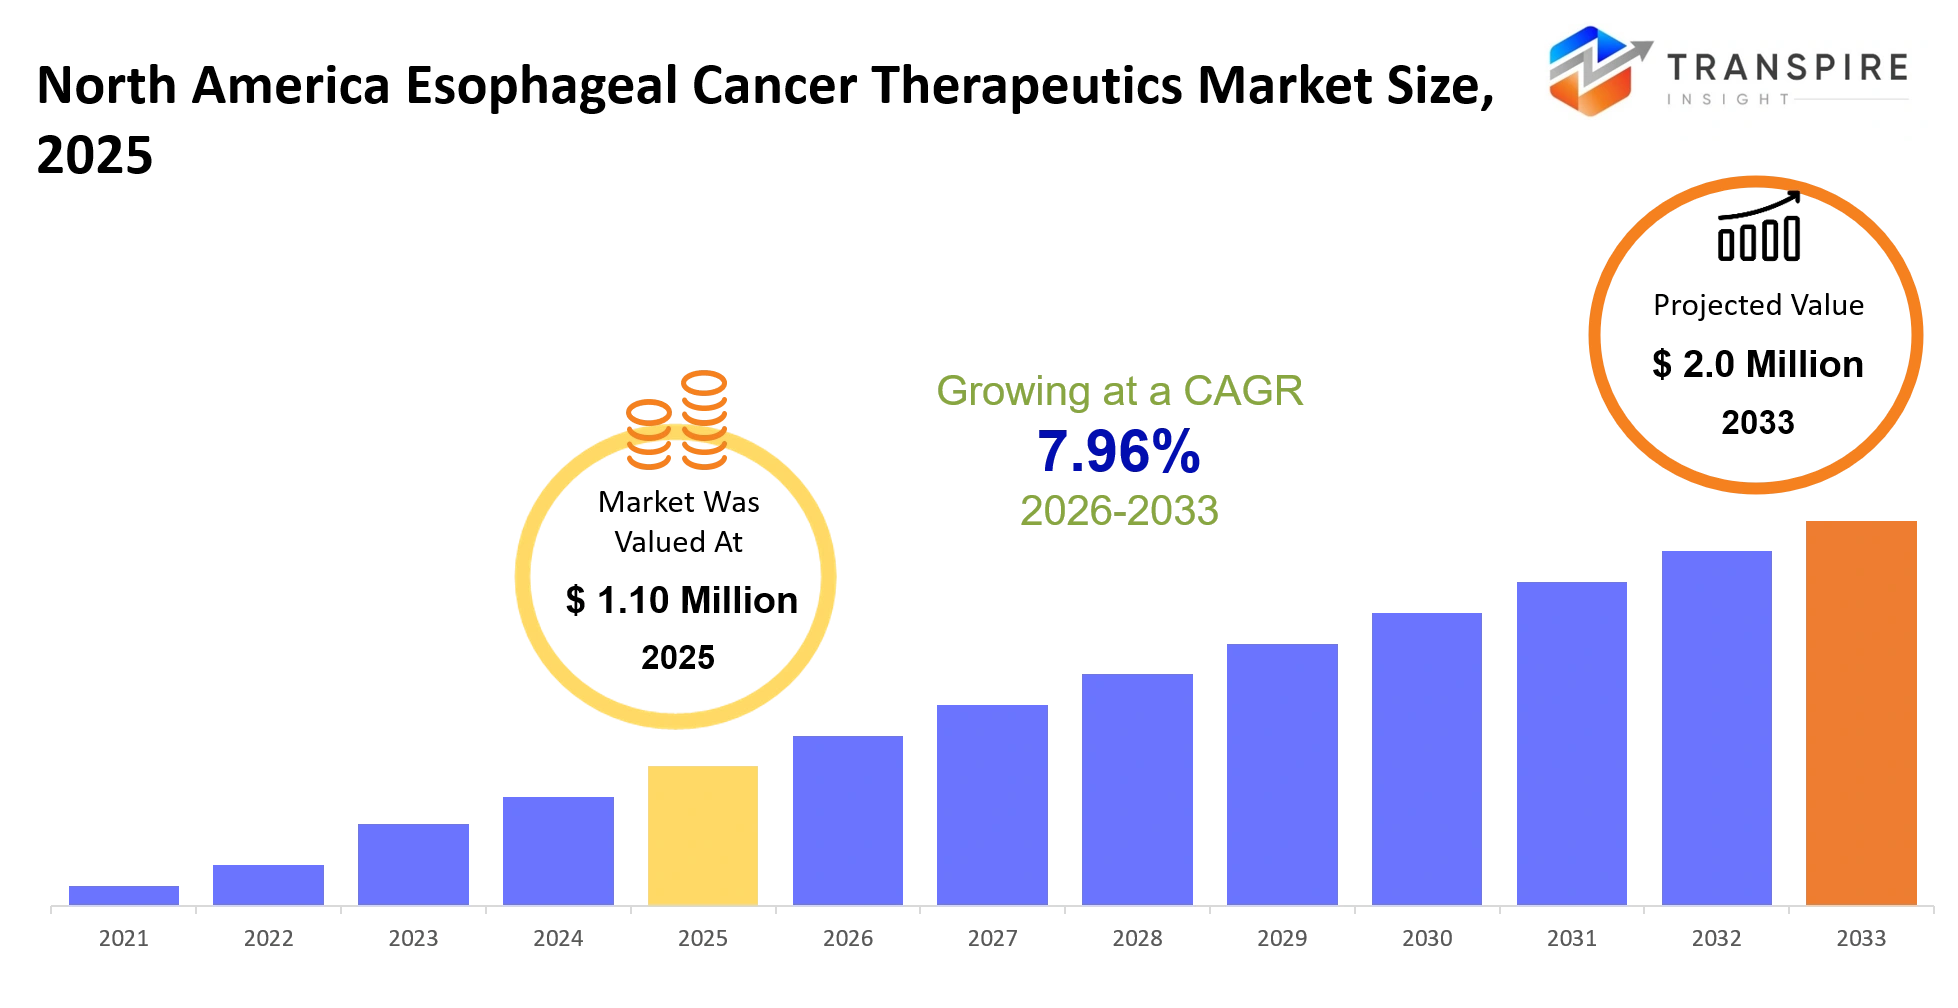
- North America Esophageal Cancer Therapeutics Market Size 2025: USD 1.10 Million
- North America Esophageal Cancer Therapeutics Market Size 2033: USD 2.0 Million
- North America Esophageal Cancer Therapeutics Market CAGR: 7.96%
- North America Esophageal Cancer Therapeutics Market Segments: By Therapy Type (Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy, Others), By Application (Esophageal Adenocarcinoma, Squamous Cell Carcinoma, Gastroesophageal Junction Cancer, Others), By End User (Hospitals, Cancer Research Institutes, Specialty Clinics, Others), By Drug Class (PD-1 Inhibitors, HER2-targeted Drugs, Cytotoxic Drugs, Others).
To learn more about this report,  Download Free Sample Report
North America Esophageal Cancer Therapeutics Market Summary:
The North America Esophageal Cancer Therapeutics Market size is estimated at USD 1.10 Million in 2025 and is anticipated to reach USD 2.0 Million by 2033, growing at a CAGR of 7.96% from 2026 to 2033. North America ’s esophageal cancer therapeutics market is pretty important for helping patients improve survival odds, and keep a little quality of life even after diagnosis with one of the region’s more aggressive gastrointestinal cancers. In practice, the market covers drug therapies, targeted treatments, plus immunotherapies, and it also includes combo regimens that show up across different stages of disease management, so clinicians can extend overall survival while trying to slow down disease progression.
In the last three to five years, things sort of shifted in a noticeable way , moving away from chemotherapy as the central plan toward biomarker-led targeted therapies and immuno-oncology styles. This change has been pushed along by wider use of precision medicine and companion diagnostics in everyday oncology care. A big trigger behind this evolution was how quickly clinical evidence piled up, along with regulatory approvals for immune checkpoint inhibitors which then reshaped treatment guidelines and even how physicians decide what to prescribe. Since more patients now qualify for individualized treatment routes, healthcare providers are leaning into premium therapies more often , which can raise treatment value per patient and keep revenue growth steady across the overall market.
Key Market Insights
- In 2025, the United States is basically running the show in the North America Esophageal Cancer Therapeutics Market, with more than 85% of the regional share, it feels like almost everything is there.
- Canada meanwhile shows the quickest momentum, fueled by widening oncology infrastructure and easier access to newer cancer therapies and yes, reimbursement is part of it too.
- Overall, higher healthcare spending, plus solid reimbursement frameworks, keeps pushing up the regional industry size and the real world adoption of treatments kinda continuously.
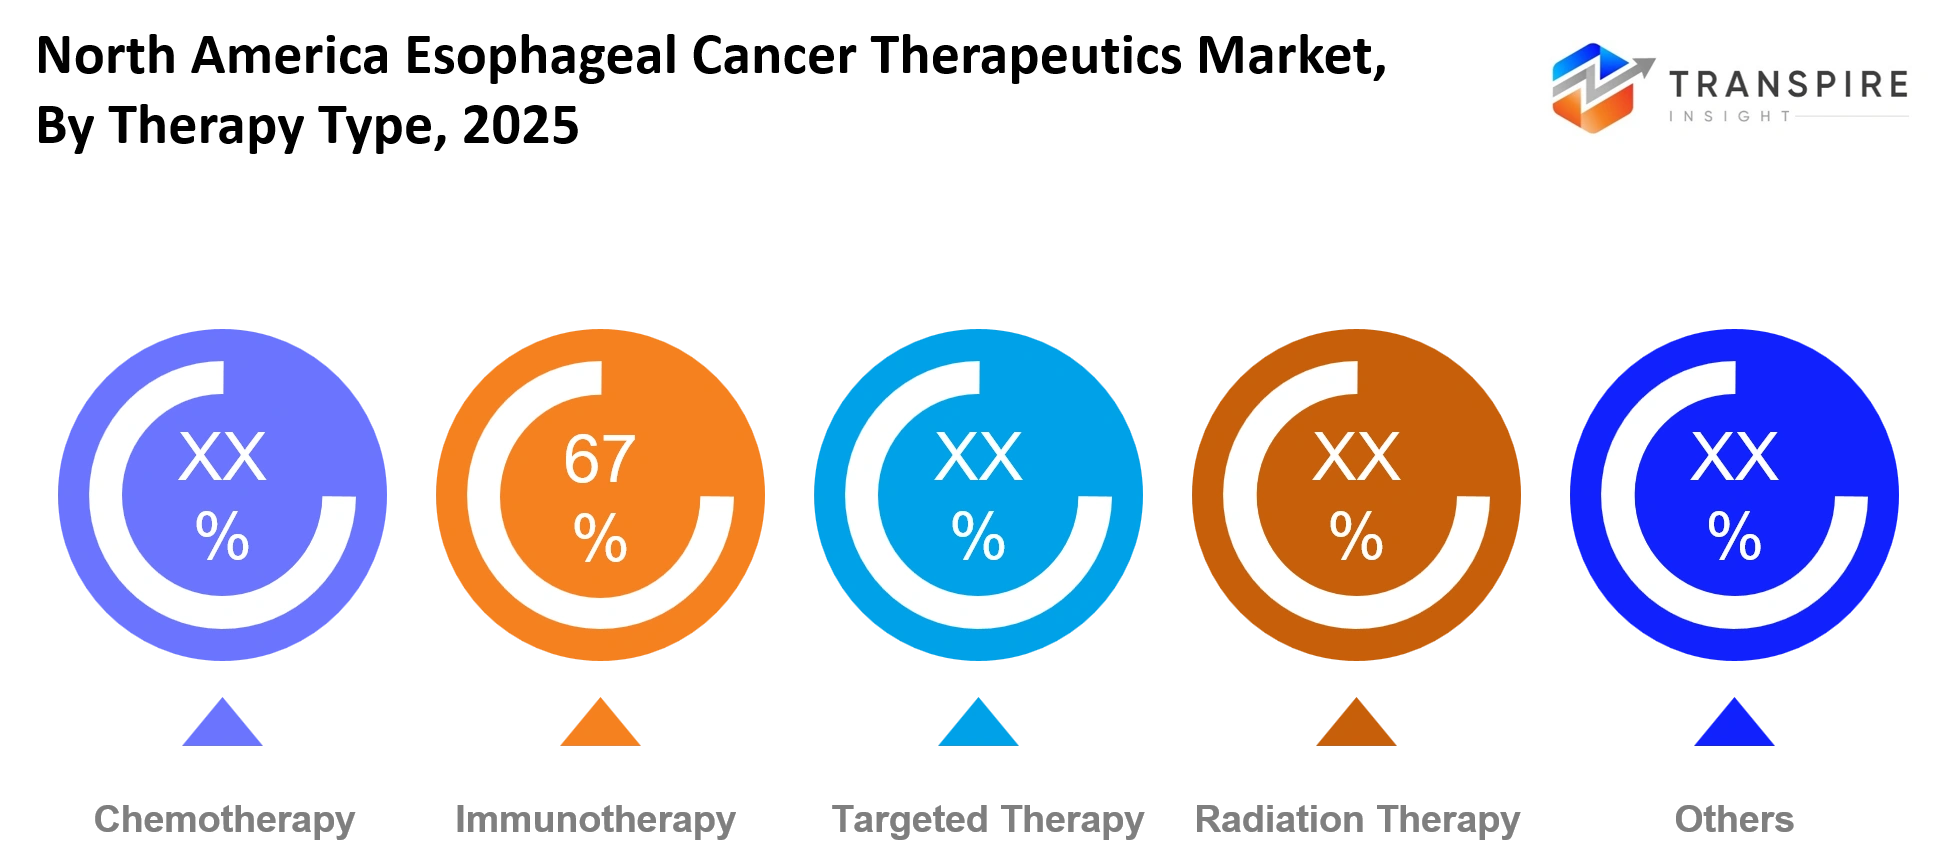
- Immunotherapy is still taking the lead, it grabs about 40% of the total revenue in 2025, mostly because the outcomes look a bit stronger and the use cases keep widening, you know.
- Targeted therapy remains in the second spot , and it’s supported by broader biomarker testing plus more individualized treatment plans.
- Combination therapy is the segment that grows fastest through the forecast period, and that’s largely connected to better progression-free survival and improved treatment performance, too.
- For disease stage , advanced and metastatic esophageal cancer treatment takes nearly 60% of the market share, which basically mirrors the heavy clinical demand. Early stage disease management is rising as the fastest-growing application, supported by screening improvements and earlier detection.
- And neoadjuvant, along with adjuvant therapies, are also reshaping how care pathways move across oncology centers.
- When it comes to end-use, hospitals dominate the North America Esophageal Cancer Therapeutics Market, accounting for about 65% of total treatment volume in 2025.
- Specialized cancer centers are the fastest-growing end-user category, with multidisciplinary care models acting like the engine.
- Academic research institutions keep extending clinical trial activity which is, in turn, speeding up therapeutic innovation and overall market growth.
What are the Key Drivers, Restraints, and Opportunities in the North America Esophageal Cancer Therapeutics Market?
The strongest growth driver in the North America Esophageal Cancer Therapeutics Market, is the quick move toward immunotherapy and biomarker guided treatment. This change was pushed along by a chain of regulatory approvals and clinical trial results showing better survival outcomes compared with plain chemotherapy alone. As oncologists keep adding checkpoint inhibitors and targeted therapies into first line and adjuvant care, overall treatment duration also stretches, and the per patient therapy value goes up. In practice, this evolution increases market revenue too, by shifting more patients toward premium priced options that show measurable clinical gains, and also by widening who can qualify across multiple disease stages, or at least that’s how it tends to play out.
The biggest restraint, though still, remains the high cost and the general complexity of advanced cancer treatment. This problem is sort of structural, because it is tied to long drug development cycles, expensive biologic manufacturing processes, and also tough reimbursement negotiations across health care systems. Even after innovative therapies get approved, access can be a bit lopsided, depending on insurance coverage, biomarker tests that are actually available, and what kind of treatment centers can truly deliver. And that whole situation kinda slows the adoption of therapy, reduces the number of patients who are eligible for advanced care, and it also means the market doesn’t reach its full revenue upside.
A major chance is hiding in the expansion of precision oncology, backed by next-generation sequencing and companion diagnostics . There is also an opening through molecular profiling infrastructure, that is helping spot actionable biomarkers earlier, specifically for esophageal cancer patients, which is kinda the key point. As testing gets more embedded into day to day oncology practice, pharmaceutical companies can start building highly targeted therapies for certain patient groups, not just broad approaches. This whole direction could push treatment results forward, while at the same time creating fresh commercial pathways for newer therapeutic products throughout North America.
What Has the Impact of Artificial Intelligence Been on the North America Esophageal Cancer Therapeutics Market?
Artificial intelligence along with advanced digital technologies are, increasingly reshaping the North America Esophageal Cancer Therapeutics Market, but mainly by improving clinical decision making and speeding up drug development, plus better patient management in general. In practice, healthcare providers are rolling out AI powered platforms that kinda automate the review of pathology slides, radiology images, and electronic health records. This way, disease progression can be spotted sooner and treatment eligibility becomes easier to confirm. At the same time, these setups cut down on manual checking, so oncologists can focus on high risk patients with more discipline and less delay.
Machine learning models are also making predictive tasks sharper across the entire treatment pathway. Researchers use AI algorithms to locate biomarkers, forecast how someone might respond to immunotherapy, and even fine tune clinical trial recruitment strategies. Pharmaceutical firms increasingly lean on these capabilities to interpret large genomic datasets, which shortens the time until target discovery, and also improves the chance of a successful development program. In real clinical environments, predictive analytics back up treatment planning by estimating recurrence likelihood and flagging possible adverse events earlier than before.
Altogether, these uses drive operational advantages like quicker diagnosis, better patient stratification, lower trial expenses, and in many cases improved treatment results. A number of oncology centers say they see smoother workflow efficiency and faster time-to-treatment decisions once AI assisted diagnostic tools get integrated into routine care.
Still, one key constraint stays kind of stubborn: the supply of high quality, standardized clinical datasets. If healthcare systems collect data in different ways then algorithm accuracy can drop, and that also limits how well AI models can scale outside controlled environments, especially in real world oncology care.
Key Market Trends
- From 2020 on, oncologists have been leaning more and more into immunotherapy combinations, so a lot of treatment protocols have slid past the old style chemotherapy track for advanced esophageal cancer patients , and it kinda changed how clinicians think day to day.
- Between 2021 and 2025, biomarker testing rates jumped a lot , which in turn let more patients meet the criteria for targeted therapies and those individualized treatment plans , you know the kind that match the patient’s profile.
- Then after a few big pivotal trials, regulatory approvals for checkpoint inhibitors sped up , especially because they showed better overall survival than chemotherapy-only approaches did.
- At the same time, pharma leaders like Merck, Bristol Myers Squibb, and AstraZeneca boosted oncology investments quite a bit, and that made competition feel more intense across the top therapeutic categories.
- Clinical trial design choices also drifted toward combination therapies , because multiple studies suggested stronger progression-free survival results than what single agent strategies usually deliver.
- Academic cancer centers and specialty oncology networks kept expanding precision medicine programs, and that increased how often genomic profiling shows up in normal clinical practice.
- Real-world evidence platforms also started getting more attention after 2022, letting manufacturers show longer-term treatment value, and it also supported reimbursement discussions that can be pretty tough.
- Drug developers have increasingly paired up with diagnostic companies , to push companion testing technologies forward, and to tighten up patient selection accuracy , even when the workflow is messy.
- Meanwhile, earlier detection initiatives gradually shifted treatment volumes toward adjuvant and neoadjuvant settings , and that has created new commercial openings that weren’t as obvious before.
- And across R&D, AI-powered analytics tools have surfaced more widely , cutting down biomarker discovery timelines, plus improving clinical trial recruitment efficiency, which sounds simple but it really isn’t.
North America Esophageal Cancer Therapeutics Market Segmentation
By Therapy Type
By therapy type, immunotherapy sits in the lead spot, mainly because strong clinical results, more regulatory approvals, and a growing inclusion into first line protocols. Checkpoint inhibitors have pretty much shifted the whole plan of care, improving survival numbers for certain patient groups, and also opening up room for combined regimens. Chemotherapy keeps being relevant, since many people still get the more traditional approach either by itself or alongside newer options.
Targeted therapy is also gaining some momentum as biomarker testing gets more common across oncology clinics so doctors can better align the medicine with the particular tumor features. Radiation therapy and a few other supportive care choices still matter a lot, especially when a multimodal approach is used. In the future, the growth curve is expected to lean toward immunotherapy and targeted treatment as precision medicine keeps moving forward. Manufacturers are putting in big effort into clinical studies, while healthcare providers are increasingly drawn to regimens that demonstrate measurable benefits in patient outcomes ,and durable long term disease control.
To learn more about this report, Download Free Sample Report
By Application
By application, esophageal adenocarcinoma takes the largest share, mostly because prevalence stays high across North America and there’s a growing supply of targeted treatments that people can actually use. Gastroesophageal junction cancer is also a big part, not just because it sits near the esophagus, but because the treatment pathway often overlaps with how esophageal cancer is managed, and it tends to gain from similar therapeutic innovations. Squamous cell carcinoma is still clinically significant too, especially now that immunotherapy keeps expanding what’s possible for this group of patients.
Demand patterns shift across applications, since molecular profiles, the pace of disease progression, and treatment responses don’t match up neatly between these cancer types. Better diagnostic capability has made it easier to spot particular tumor subtypes, and that in turn supports more personalized care choices. Looking ahead, development will probably lean toward subtype focused therapies and biomarker led approaches, kind of like using signals first then selecting a therapy. All of this should open up room for pharmaceutical companies to launch differentiated products, while also helping clinicians deliver more effective, individualized treatment strategies, without the usual one size fits all feeling.
By End-User
For end user, hospitals kind of end up dominating the market, because really complete cancer treatment needs advanced infrastructure, a multidisciplinary care crew and also access to specialized oncology services. Big hospital networks also show up a lot in clinical trials, so patients can reach innovative therapies earlier than they usually appear at broader commercialization. Specialty clinics are a growing part too, mainly since outpatient cancer care is getting more sophisticated and is able to handle advanced biologics, plus targeted therapies. Cancer research institutes also matter a ton, through drug development routines, translational research work and clinical validation studies that end up shaping what future treatment standards look like.
Some other healthcare facilities still play a support function, like in diagnosis, follow up care and supportive treatment services. Growth in this area tends to follow healthcare investment, reimbursement structures, and how much oncology expertise is actually available. In the future, expansion should further reinforce the role of specialty treatment centers and the integrated care networks, those can deliver complex therapeutic regimens in a more efficient way
By Drug Class
In terms of drug class, the PD-1 inhibitors kinda lead the market, mostly because there’s been a lot of uptake across different treatment settings, and the evidence is pretty steady on improved survival. They’ve turned into a key part of modern treatment protocols, and they still keep picking up market share, driven by new indications and those combination strategies that keep coming up. Cytotoxic drugs are still used a lot too, mainly due to well-known treatment guidelines, easy access, and also acquisition costs that are usually lower compared to many advanced therapies. HER2-targeted drugs hold a solid spot, but mostly inside biomarker-selected patient groups, where the clinical gains justify the premium pricing, and the adoption keeps going.
Then there are other emerging classes, like novel targeted agents and combination biologics, and they’re starting to widen the competitive field as research momentum intensifies. Looking ahead, market direction seems to move toward more personalized treatment plans, so developers are focusing on molecularly defined patient cohorts. Investors and manufacturers are expected to lean toward innovative drug classes, the ones with differentiated efficacy and stronger long-term commercial upside.
What are the Key Use Cases Driving the North America Esophageal Cancer Therapeutics Market?
The main scenario that seems to drive adoption is basically the treatment of advanced and metastatic esophageal cancer, inside hospital based oncology programs. Immunotherapy and combination treatment regimens are where the highest demand comes from, mainly because patients can end up needing long treatment durations and this specialized kind of clinical management that helps survival outcomes. In practice, it’s not just one drug it’s more of a whole pathway.
A further expansion shows up in neoadjuvant and adjuvant settings, so therapies are given before or after surgery, to help reduce recurrence risk. Specialty cancer clinics, and academic medical centers too are gradually picking up targeted therapies and biomarker guided treatment protocols. This supports a more personal care pathway, even if the rollout can feel uneven at first.
For emerging use cases, there’s the molecularly tailored approach for biomarker defined patient groups and AI assisted treatment selection that leans on genomic profiling. Clinical research institutes are also looking into new combination approaches that mix immunotherapy with targeted agents, and that can create openings for more effective interventions across the forecast period.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 1.10 Million |
|
Market size value in 2026 |
USD 1.17 Million |
|
Revenue forecast in 2033 |
USD 2.0 Million |
|
Growth rate |
CAGR of 7.96% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Country scope |
North America (Canada, The United States, and Mexico) |
|
Key company profiled |
Merck & Co., Bristol Myers Squibb, Roche, AstraZeneca, Pfizer, Eli Lilly, Novartis, Amgen, BeiGene, Sanofi, GSK, Takeda Pharmaceutical, Daiichi Sankyo, Regeneron Pharmaceuticals, Ono Pharmaceutical. |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Therapy Type (Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy, Others), By Application (Esophageal Adenocarcinoma, Squamous Cell Carcinoma, Gastroesophageal Junction Cancer, Others), By End User (Hospitals, Cancer Research Institutes, Specialty Clinics, Others), By Drug Class (PD-1 Inhibitors, HER2-targeted Drugs, Cytotoxic Drugs, Others). |
Which Regions are Driving the North America Esophageal Cancer Therapeutics Market Growth?
Honestly, the United States is kinda leading the regional market because it has a really advanced oncology setup, a solid reimbursement environment, and a high density of specialized cancer centers. Also, when it comes to regulatory support for new treatments, that has sped up how quickly immunotherapies, targeted drugs, and precision medicine are being picked up. A lot of large clinical trials are happening too, which lets new treatments reach commercialization sooner and, you know , it also helps build physician confidence in whatever is just emerging. On top of that, the whole ecosystem is pretty well developed—pharmaceutical companies, academic institutions, diagnostic labs, and healthcare providers, all together, it sustains that dominant position.
Canada, meanwhile, is the second-largest regional market and it feels a bit different from the United States. It focuses more on coordinated public healthcare delivery and using evidence based treatment adoption as the main idea. Healthcare funding stays consistent there, and the reimbursement assessments are structured, so uptake of approved therapies is steady across the major provinces. Academic cancer networks are a big deal as well, they expand access to advanced treatment options while still keeping cost effectiveness standards in place. So even though the patient population is smaller, this stability basically makes Canada a dependable contributor to regional revenue.
Mexico is, kind of, coming up as the quickest expanding market as healthcare modernization pushes better access to oncology services and dedicated cancer treatment centers. Lately there have been investments into diagnostic capabilities ,and also hospital infrastructure which in turn widened the availability of advanced therapeutics inside urban healthcare systems. On top of that , more engagement in international clinical research, plus a steady rise in access to innovative medicines, has really kept the market momentum moving forward. Overall growth across Mexico means there are promising chances for pharmaceutical manufacturers, healthcare investors, and diagnostic providers looking for expansion between 2026 and 2033.
Who are the Key Players in the North America Esophageal Cancer Therapeutics Market and How Do They Compete?
In the North America Esophageal Cancer Therapeutics Market , competition is kind of moderately concentrated, because only a few pharmaceutical companies control a meaningful chunk of revenue, through proprietary immunotherapy and more focused targeted therapies. The thing is, competition isn’t mainly about price . It’s more about who can keep refining their pipeline, improve outcomes, and stay one step ahead in efficacy. Instead it is more driven by technology novelty, where clinical strength, survival results, and biomarker based treatment differences end up steering prescribing behavior. Existing manufacturers still try to hold their spot by pushing out expanded indications, running combination therapy studies and keeping big clinical development efforts going. Meanwhile, newer biotechnology firms are landing specialized oncology candidates, and that naturally raises competitive tension in a few particular patient groups
Merck kind of leans hard into immuno-oncology innovation with it’s PD-1 inhibitor lineup, and it stands out because there is a large amount of clinical evidence across many cancer types. Their continued push into combination therapy trials, and biomarker research it helps make the treatments feel a little more relevant. it also supports broader physician comfort, which is maybe why people talk about it a lot. On the other hand, Bristol Myers Squibb seems to lean more heavily into checkpoint inhibitor development, and it also gets help from a deep oncology pipeline that they can route across different phases of disease progression, like from one stage to the next. With strategic research collaborations and clinical partnerships, validation of new approaches can happen faster, and that in turn helps the brand keep growing its long term portfolio.
AstraZeneca kind of differentiates via precision oncology and targeted treatment work, especially in biomarker-selected patient groups, where personalized medicine really does generate measurable clinical value. The company keeps expanding through diagnostic partnerships and also investments in molecular testing capabilities, that help improve patient matching. Pfizer meanwhile mixes internal research with licensing arrangements and collaborative development approaches, to boost its oncology offerings and move commercialization timelines along faster, generally speaking. F. Hoffmann-La Roche gets an advantage from having therapeutics and diagnostics tightly integrated, which allows better patient stratification and helps wider adoption of personalized treatment pathways across healthcare systems, too.
Company List
- Merck & Co.
- Bristol Myers Squibb
- Roche
- AstraZeneca
- Pfizer
- Eli Lilly
- Novartis
- Amgen
- BeiGene
- Sanofi
- GSK
- Takeda Pharmaceutical
- Daiichi Sankyo
- Regeneron Pharmaceuticals
- Ono Pharmaceutical
Recent Development News
In June 2026, Fulcrum Therapeutics Explores Strategic Alternatives Following FDA Concerns: Fulcrum Therapeutics announced it would halt development of its lead drug candidate after the U.S. FDA raised concerns regarding potential cancer-related risks associated with the targeted protein complex. Following the decision, the company stated it was evaluating strategic alternatives, including a possible merger or sale, while implementing cost-reduction measures. Although the program was not for esophageal cancer, the FDA's heightened scrutiny of oncology-related pathways may influence future cancer drug development and regulatory reviews across the sector.
Source: https://www.reuters.com
In May 2026, Partner Therapeutics Secured FDA Approval for New Oncology Therapy: Partner Therapeutics received U.S. FDA approval for a treatment targeting a rare bile duct cancer through a fast-track regulatory pathway. The approval highlights continued regulatory support for innovative oncology therapies addressing unmet needs. The event reinforces investor confidence in oncology-focused biopharmaceutical companies and demonstrates the FDA's willingness to expedite novel cancer treatments, an important factor for developers pursuing esophageal cancer indications.
Source: https://www.reuters.com
What Strategic Insights Define the Future of the North America Esophageal Cancer Therapeutics Market?
North America Esophageal Cancer Therapeutics Market is kind of structurally shifting toward precision-led oncology ecosystems where treatment calls are more and more hinging on molecular profiling, plus real-world evidence mashups. In the next 5–7 years immunotherapy alongside biomarker-driven targeting should anchor clinical pathways, pushed by tighter linkage between diagnostic validation and reimbursement signoffs. This feels like part of that wider shift in healthcare where oncology spending moves more toward outcomes-based budgets rather than volume based drug use, so the developers who bring both therapeutic and diagnostic capabilities will likely get the edge.
Still, there’s a less visible risk that’s starting to show up, like concentration exposure inside checkpoint inhibitor portfolios, where too much reliance on a small group of immunotherapy classes could magnify pricing pressure if biosimilar competition or guideline revisions hit sooner than anyone expected. Another issue is fragmented biomarker standardization across treatment centers, which might make uniform adoption slower, even if the clinical evidence is strong.
One real opportunity that’s emerging, a bit under the radar, involves decentralized molecular testing that gets integrated with hospital-at-home oncology models, especially in the United States where outpatient cancer care is expanding quickly. Market players should aim for partnerships with diagnostic platforms and invest in adaptive clinical trial designs that can produce faster real-world validation. That way reimbursement alignment can happen earlier, and the differentiation stays more durable and sustained.
North America Esophageal Cancer Therapeutics Market Report Segmentation
By Therapy Type
- Chemotherapy
- Immunotherapy
- Targeted Therapy
- Radiation Therapy
- Others
By Application
- Esophageal Adenocarcinoma
- Squamous Cell Carcinoma
- Gastroesophageal Junction Cancer
- Others
By End User
- Hospitals
- Cancer Research Institutes
- Specialty Clinics
- Others
By Drug Class
- PD-1 Inhibitors
- HER2-targeted Drugs
- Cytotoxic Drugs
- Others
Frequently Asked Questions
Find quick answers to common questions.
The approximate North America Esophageal Cancer Therapeutics Market size for the market will be USD 2.0 Million in 2033.
The key segments of the North America Esophageal Cancer Therapeutics Market are By Therapy Type (Chemotherapy, Immunotherapy, Targeted Therapy, Radiation Therapy, Others), By Application (Esophageal Adenocarcinoma, Squamous Cell Carcinoma, Gastroesophageal Junction Cancer, Others), By End User (Hospitals, Cancer Research Institutes, Specialty Clinics, Others), By Drug Class (PD-1 Inhibitors, HER2-targeted Drugs, Cytotoxic Drugs, Others).
Major players in the North America Esophageal Cancer Therapeutics Market are Merck & Co., Bristol Myers Squibb, Roche, AstraZeneca, Pfizer, Eli Lilly, Novartis, Amgen, BeiGene, Sanofi, GSK, Takeda Pharmaceutical, Daiichi Sankyo, Regeneron Pharmaceuticals, Ono Pharmaceutical.
The current market size of the North America Esophageal Cancer Therapeutics Market is USD 1.10 Million in 2025.
The North America Esophageal Cancer Therapeutics Market CAGR is 7.96%.
- Merck & Co.
- Bristol Myers Squibb
- Roche
- AstraZeneca
- Pfizer
- Eli Lilly
- Novartis
- Amgen
- BeiGene
- Sanofi
- GSK
- Takeda Pharmaceutical
- Daiichi Sankyo
- Regeneron Pharmaceuticals
- Ono Pharmaceutical
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Jul 2026
Alopecia Treatment Market
Alopecia Treatment Market Size, Share & Analysis Report By Disease Type (Alopecia Areata, Cicatricial Alopecia, Traction Alopecia, Alopecia Totalis, Androgenetic Alopecia, Alopecia Universalis, and Other Disease Types), By Treatment Type (Topical Treatments, Oral Medications, Injectable Therapies, and Hair Transplantation), By Gender (Male, and Female), By Distribution Channel (Hospitals and Clinics, Retail Pharmacies, and Online Retailers), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Jul 2026
Medical Ultrasound Probe Market
Medical Ultrasound Probe Market Size, Share & Analysis Report By Type (Linear Type, Convex Type, Endocavitary Probe, Phased Array/Cardiac Probe, Transesophageal (TEE) Probe, and Others), By Application (Ophthalmology, Cardiology, Musculoskeletal, Oncology, Obstetrics & Gynecology, General Imaging, and Others), By End User (Hospitals & Clinics, Diagnostic Centers, Ambulatory Surgical Centers, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
May 2026
Biosimilars Market
Biosimilars Market By Product Type (Monoclonal Antibodies, Recombinant Hormones, Erythropoietin, G-CSF, Others), By Indication (Oncology, Autoimmune Diseases, Blood Disorders, Diabetes, Others), By Manufacturing Type (In-House Manufacturing, Contract Manufacturing), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033
-
Apr 2026
Gastrointestinal Endoscopy Market
Gastrointestinal Endoscopy Market By Type (Rigid Gastrointestinal Endoscope, Flexible Gastrointestinal Endoscopes, Disposable Gastrointestinal Endoscope), By Procedure Type (Colonoscopy, Gastroscopy, Duodenoscopy, Enteroscopy, Flexible Sigmoidoscopy, Others), By Application (Diagnosis, Treatment), By End-Users (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Laboratories, Others), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033