
Middle East and Africa Catalyst Handling Services Market Size & Forecast:
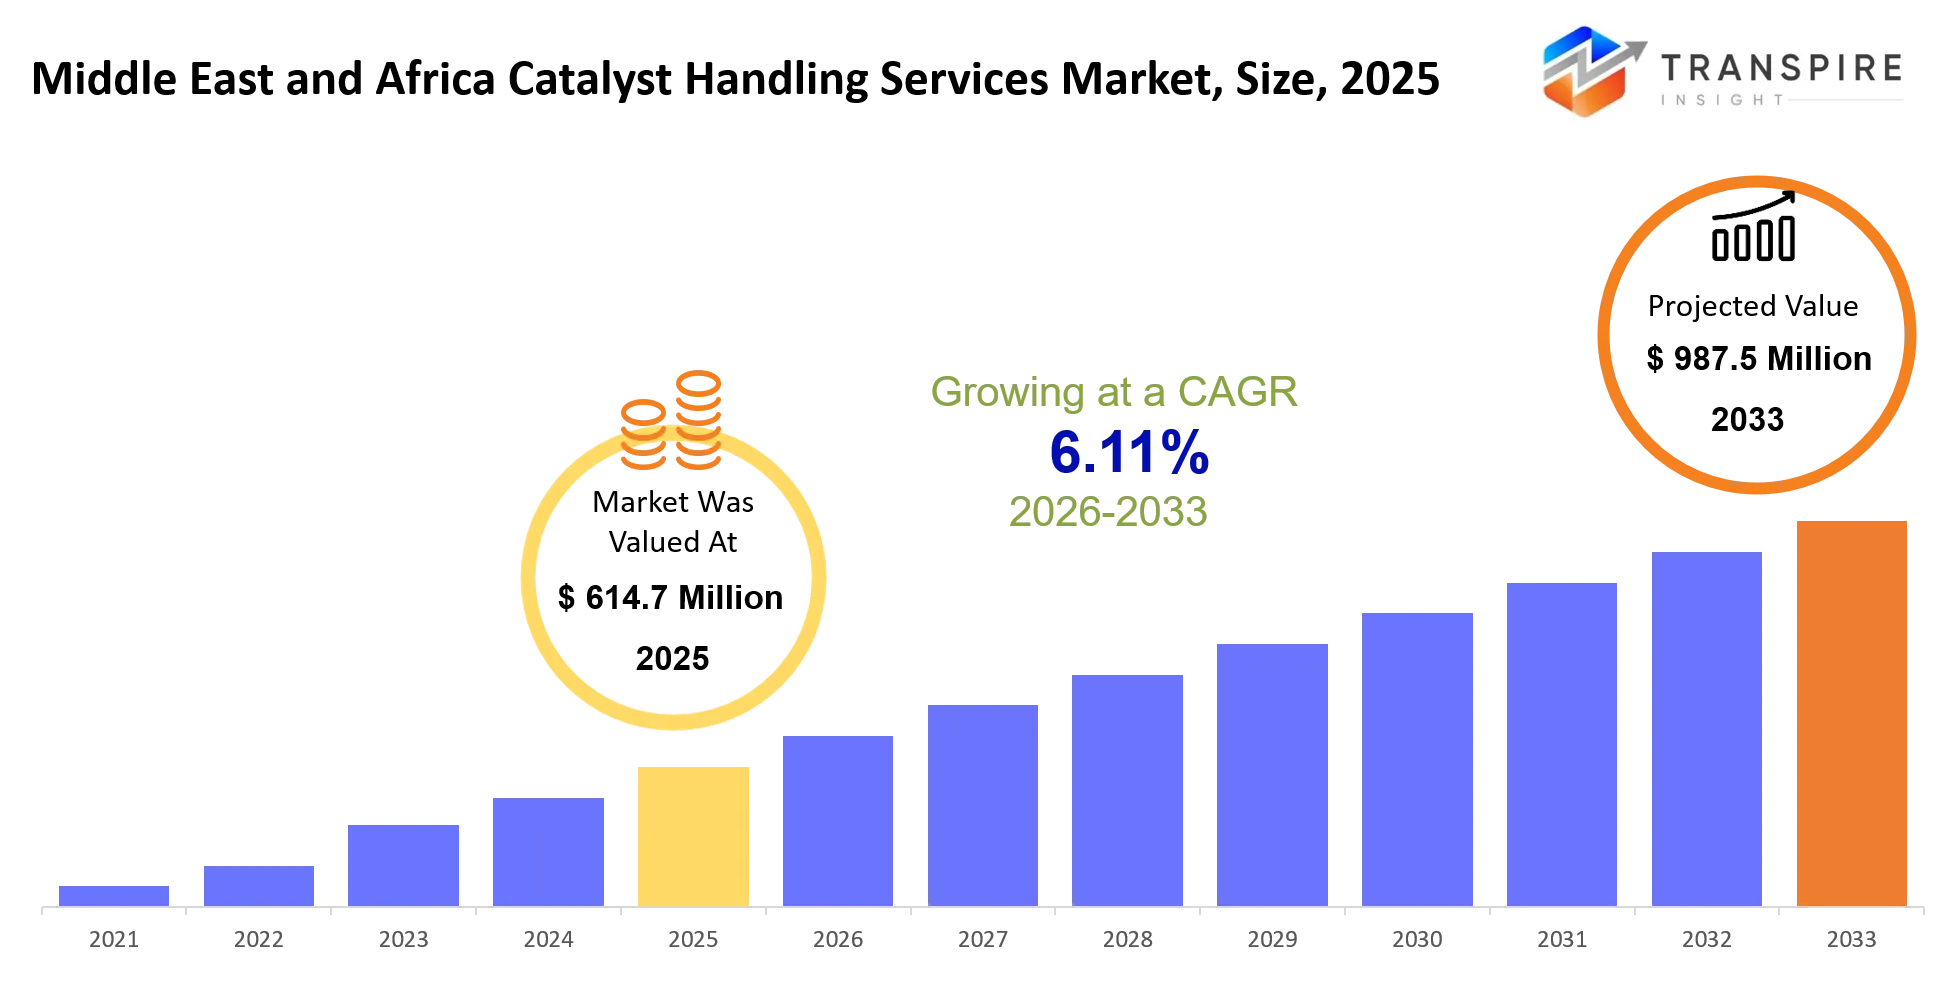
- Middle East and Africa Catalyst Handling Services Market Size 2025: USD 614.7 Million
- Middle East and Africa Catalyst Handling Services Market Size 2033: USD 987.5 Million
- Middle East and Africa Catalyst Handling Services Market CAGR: 6.11%
- Middle East and Africa Catalyst Handling Services Market Segments: By Service Type (Catalyst Loading, Unloading, Screening, Replacement, Others); By Application (Refineries, Petrochemical Plants, Chemical Plants, Others); By Catalyst Type (Hydrotreating, Reforming, FCC, Others); By End User (Oil & Gas, Chemicals, Others)
Middle East and Africa Catalyst Handling Services Market Summary
The Middle East and Africa Catalyst Handling Services Market was valued at USD 614.7 Million in 2025. It is forecast to reach USD 987.5 Millionby 2033. That is a CAGR of 6.11% over the period.
The Middle East and Africa Catalyst Handling Services Market plays a critical role in making sure refineries, petrochemical complexes , and chemical processing plants are working safely and efficiently . In practice these services oversee the loading, unloading, screening, replacement , and handling of catalysts inside reactors, especially during maintenance shutdowns and turnaround projects . If there is no specialized catalyst handling then operators can end up with longer downtime , higher safety risks, and less production efficiency. Over the last five years the market moved away from labor heavy ways of doing things and it has been leaning more toward automated loading systems , dense loading technologies, and also digital turnaround management platforms that help reactor performance as well as worker safety.
One big trigger shaping the market is the push for more refining and petrochemical investments across Gulf countries, plus stricter environmental compliance rules around fuel quality and emissions . When refiners start processing heavier crude grades and then they also add cleaner fuel production units , the catalyst replacement cycles can turn more frequent and they become more technically demanding too. That evolution has pushed more spend toward specialized handling services , boosted the uptake of advanced reactor maintenance solutions , and opened up recurring revenue routes for providers that support big industrial assets.
Key Market Insights
- The Middle East and Africa Catalyst Handling Services Market, kinda benefits from refinery expansion programs, with Saudi Arabia showing the most notable forecast growth, inside the region.
- GCC countries together bring in more than 55% of the regional service demand, driven by big refining and petrochemical assets, that keep running.
- Catalyst loading and unloading is basically what the market leans on most , and it makes up nearly 40% of global catalyst handling service revenues in 2025.
- Screening and replacement services show up as the second-largest revenue slice, because catalyst performance optimization needs are rising, little by little, every quarter.
- Transport and handling services are set to be the fastest-growing segment through 2033, as logistics complexity keeps increasing, even when the timeline feels tight.
- Refineries still lead as the dominant application, generating over 45% of regional service demand via scheduled turnaround operations, which is still a big deal.
- Petrochemical plants are emerging as the quickest-growing application segment, tied to new downstream investment plans across the Gulf.
- Oil and gas companies hold the largest end-user share , supported by ongoing hydroprocessing and fuel upgrading work that doesn’t really slow down.
- Major participants—CR Asia, Cat Tech, Anabeeb, Mourik, Veolia, and Johnson Matthey—are investing in automation, along with advanced reactor services, to keep improving efficiency.
- Firms are building competitive edge through robotic unloading systems, dense loading technology, catalyst recycling solutions , and by pushing regional expansion strategies that feel more targeted.
What are the Key Drivers, Restraints, and Opportunities in the Middle East and Africa Catalyst Handling Services Market?
The strongest growth driver seems like the expansion, plus modernization, of refining and petrochemical infrastructure across the Middle East. Governments and national oil companies have put a lot of money into fuel quality upgrades, hydroprocessing units, and those integrated refining–petrochemical complexes. These efforts, they still need periodic catalyst replacement and reactor maintenance so throughput stays steady and the output matches the tougher product specifications. Every turnaround event then generates demand for loading, unloading , screening and catalyst management services, which makes these recurring revenue streams for specialized contractors. And as operators aim for higher conversion efficiency while also keeping operational risk lower, spending on advanced handling services keeps climbing
One big structural challenge, is the lack of highly trained technical personnel who can carry out catalyst handling operations under strict safety rules. Reactor entry work, confined-space operations, and catalyst management basically require specialized certifications, the right equipment, and real operational experience. Building that workforce takes years, so it cannot be fixed overnight. Because of this, service providers run into labor constraints during peak turnaround seasons, which can slow projects down and curb market expansion
A notable future opportunity, is automated and robotic catalyst handling systems. Refiners are increasingly looking for zero entry maintenance solutions that reduce worker exposure and also cut the shutdown durations. Technologies like robotic unloading, digital reactor mapping, catalyst traceability platforms, and automated dense loading systems are getting more attention over time.
What Has the Impact of Artificial Intelligence Been on the Middle East and Africa Catalyst Handling Services Market?
Artificial intelligence is gradually transforming catalyst handling operations, kinda by improving maintenance planning , reactor performance monitoring, and how turnaround execution is actually carried out. More and more industrial operators are using AI-driven analytics platforms to judge catalyst activity, look at pressure drop trends , review reactor temperature profiles, and check overall operational performance right before scheduled maintenance events. What this does is help spot catalyst degradation patterns earlier, so teams can plan replacement activities more efficiently.
Machine learning models also back predictive maintenance programs, in the sense that they forecast catalyst life cycles and estimate the most suitable replacement intervals. This technique cuts down on unexpected shutdowns and bumps refinery utilization rates. Digital twins and advanced analytics platforms are also getting integrated with reactor management systems, in order to refine catalyst loading patterns and improve conversion efficiency. In several big refining facilities, predictive maintenance programs have helped reduce downtime , while also strengthening operational reliability and making maintenance scheduling more accurate
On top of that, AI-enabled project planning tools get used to improve turnaround management by optimizing workforce allocation, equipment deployment , and the maintenance sequencing itself. These upgrades tend to lower operational costs and make project execution more predictable.
Even so, adoption is still kinda limited by integration costs and the shortage of high quality operational data. A lot of facilities still rely on legacy infrastructure, which means they don’t have the sensor networks and digital architecture needed to fully support AI-driven maintenance and performance optimization systems.
Key Market Trends
- Automated catalyst unloading adoption climbed, kind of notably between 2023 and 2026, because operators seemed to prioritize worker safety and also turnaround efficiency.
- Dense loading technologies got more widespread acceptance as well, helping with catalyst distribution, and in turn making reactor performance better by as much as 10% in certain units.
- More than 60% of the new refinery maintenance contracts now seem to contain digital monitoring, plus performance reporting requirements, built right in.
- The Gulf refinery expansion projects also sped up catalyst replacement activity by an estimated 15–20% since 2022, not exactly slow.
- Catalyst recycling and regeneration services expanded quite a lot, as operators kept focusing on lifecycle cost optimization, rather than just the short term.
- Strategic collaborations between catalyst manufacturers and service providers increased during 2025, to strengthen integrated offerings, which makes sense I guess.
- Robotic reactor maintenance solutions that once were only pilot projects moved into commercial deployment in a few large refining facilities.
- Biofuel and renewable feedstock processing created extra catalyst management requirements after 2024.
- Regional operators are increasingly favoring multi service contractors that can handle complete turnaround projects instead of only standalone jobs, you know.
- Digital catalyst traceability and lifecycle management platforms have also emerged as differentiating capabilities among major service providers.
Middle East and Africa Catalyst Handling Services Market Segmentation
By Service Type
Catalyst loading and unloading take up the biggest portion of service activity because each scheduled turnaround needs safe placement and also removal of catalyst materials from the reactors, so in practice it’s kind of always there. Dense loading techniques support better reactor efficiency, and the unloading part also makes room for inspection and replacement programs, which operators really rely on. Screening services then do the sorting, they identify reusable material and separate the damaged particles, this way operators can lower waste, and also keep operating costs more controlled.
Replacement services are still just as crucial for preserving conversion efficiency and for hitting product quality targets at refining and chemical processing facilities. Besides that there are other bits, like catalyst transport and storage, plus segregation, vacuum handling, reactor cleaning, and different technical support activities. Growth across these areas shows how more complex modern refining and petrochemical operations have become. Service providers keep stretching their capabilities to deliver a whole reactor maintenance package under one single contract, so it feels more bundled than before.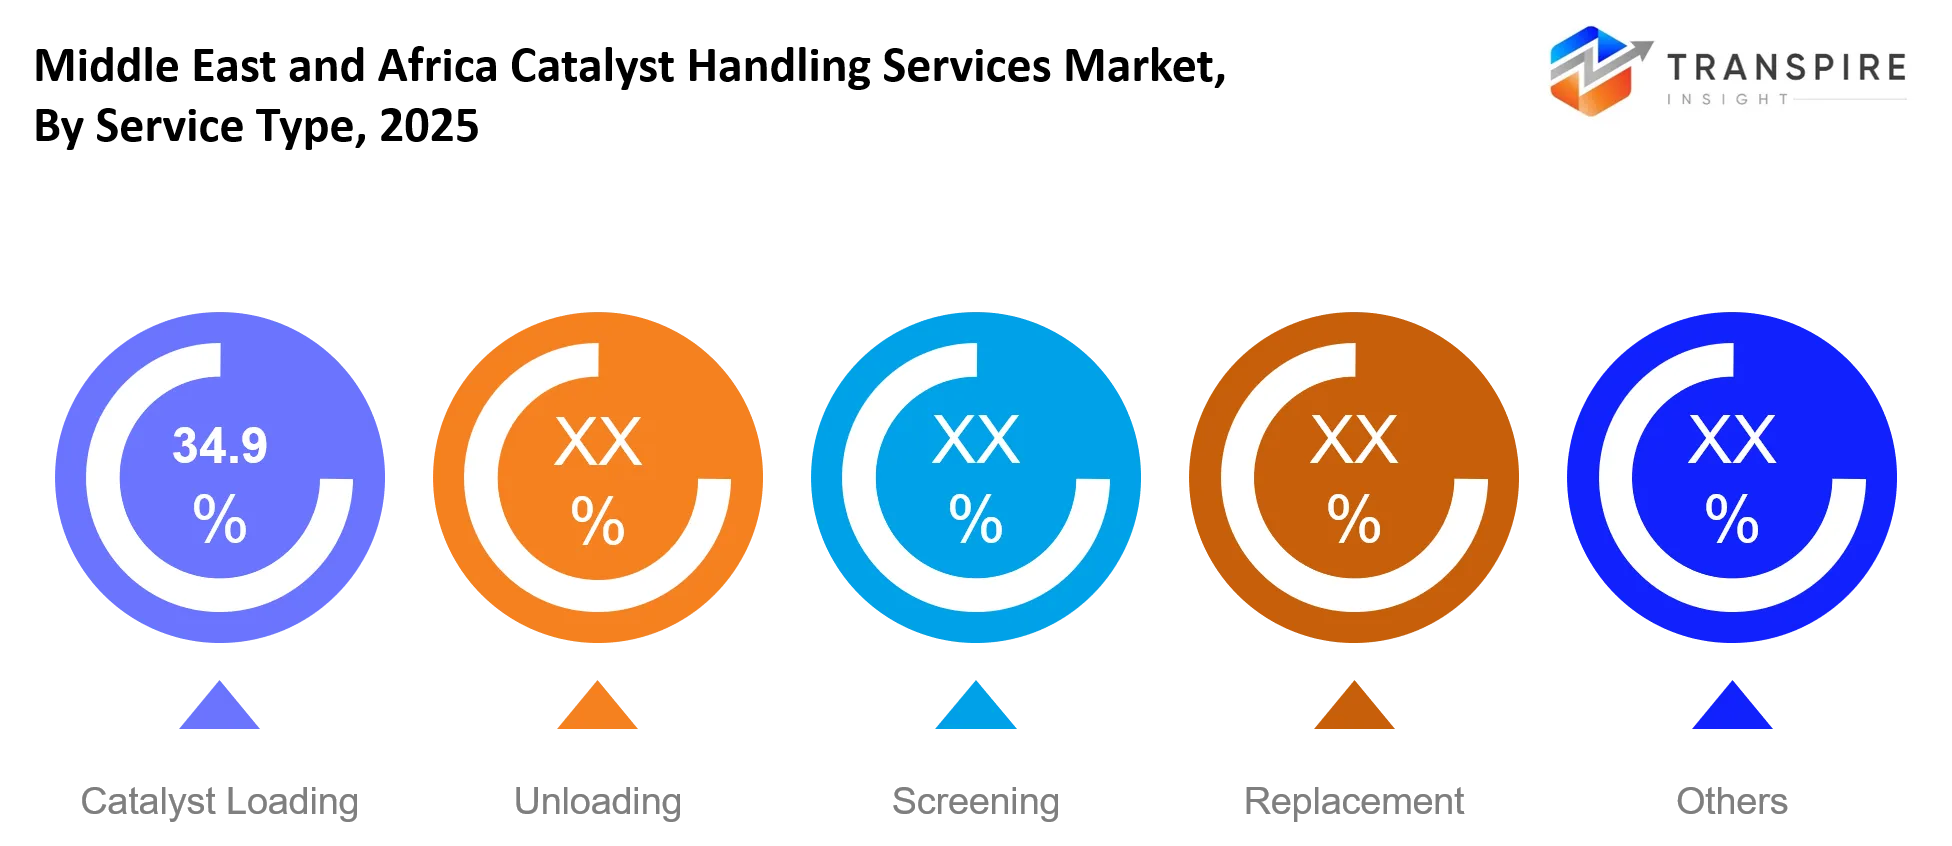
By Application
Refineries make up the biggest slice of the application share, since hydroprocessing , hydrocracking, reforming and desulfurization units do need catalyst maintenance quite often. When large refineries do shut down on a big scale, it generates substantial demand for loading, unloading, screening ,and catalyst replacement services. On top of that, fuel grade regulations plus production efficiency targets make these services even more necessary.
For petrochemical plants, they also depend on catalyst handling so conversion and processing units can keep running with fewer interruptions. Chemical plants typically work with specialized catalyst systems across many reaction pathways, which means there are recurring maintenance needs. Other uses show up at fertilizer production sites, industrial gas operations, and newer biofuel processing installations where the catalyst ability basically drives both throughput and product quality.
By Catalyst Type
Hydrotreating catalysts pull in a lot of in- service demand, partly because fuel desulfurization keeps pushing for constant catalyst monitoring and periodic swap outs. Also when operators push heavier crude grades through , the catalyst tends to fade faster , so deactivation happens quicker, which then boosts the maintenance cycle. Even so the regular upkeep services basically keep the reactor running steady while also helping with regulatory compliance , you know.
For reforming catalysts, they back gasoline output and also support petrochemical feedstock generation, so there’s usually a continuous stream of maintenance work. Meanwhile FCC catalysts stay pretty central to refining because they’re always being regenerated and re- positioned, with replacement requirements that don’t really slow down. Other groups like hydrocracking, isomerization, alkylation, plus specialty chemical catalysts, all fall under the same general theme but they need different handling steps , and they really demand technical know-how for the job to be done right.
By End User
Oil and gas companies kinda represent the biggest end user group, mostly because they run all that refining, processing, and hydrocarbon conversion infrastructure throughout the region. Big turnaround programs along with refinery modernization work keep generating a steady kind of demand for catalyst handling services. You could say operational dependability and safety targets still push budgets in this segment too, even when markets get weird or slow.
Chemical manufacturers come in as the second-largest end-user category because how well a catalyst performs basically changes production efficiency, and also the final product quality. Specialty chemical producers are increasingly looking for customized handling solutions for those more delicate, or “sensitive”, catalyst systems. Other end users show up as well , like fertilizer producers , industrial processing plants, and newer renewable fuel operators who want specialized maintenance support that fits their setup.
What are the Key Use Cases Driving the Middle East and Africa Catalyst Handling Services Market?
The primary use case kind of centers on refinery turnaround operations, where catalyst loading and unloading, plus replacement actions, keep hydroprocessing, desulfurization, and conversion units running smoothly. Those maintenance cycles create the biggest service demand, because refinery profitability really leans on uptime, product quality, and staying compliant with fuel specs, all at once.
Other use cases are also showing up more often in petrochemical and chemical manufacturing plants. New downstream projects across the Gulf, are increasingly leaning on specialized catalyst management services. The goal is to keep production steady, shave down shutdown durations, and fine tune reactor performance during the whole operating cycle.
In the future there are opportunities forming around renewable fuels, catalyst regeneration, and digital reactor maintenance programs. Sites working with bio based feedstocks need more advanced catalyst monitoring and lifecycle management, practices. Automated reactor services , and remote performance diagnostics are expected to keep gaining momentum too, since operators want safer and more efficient maintenance strategies, not just faster ones.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 614.7 Million |
|
Market size value in 2026 |
USD 652.2 Million |
|
Revenue forecast in 2033 |
USD 987.5 Million |
|
Growth rate |
CAGR of 6.11% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United States; Canada; Mexico; United Kingdom; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; United Arab Emirates |
|
Key company profiled |
CR Asia, Cat Tech, Anabeeb, Altrad, Mourik, Veolia Catalyst Services, HMT, Dickinson Group, Veolia, SGS, BASF, Johnson Matthey, Axens, Clariant, Albemarle |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Service Type (Catalyst Loading, Unloading, Screening, Replacement, Others); By Application (Refineries, Petrochemical Plants, Chemical Plants, Others); By Catalyst Type (Hydrotreating, Reforming, FCC, Others); By End User (Oil & Gas, Chemicals, Others) |
Which Regions are Driving the Middle East and Africa Catalyst Handling Services Market Growth?
The Gulf region is kinda leading the overall market growth, and Saudi Arabia along with the United Arab Emirates are basically the big hubs for refining plus petrochemical activity. Bigger downstream energy infrastructure investments , keep generating recurring needs for catalyst maintenance. Then there’s strong regulatory oversight, advanced industrial facilities, and ongoing capacity expansion that help lock in market leadership. Also, the very frequent turnaround schedules really do provide a fairly stable stream of service contracts, for both regional and international providers.
South Africa is another noteworthy market contributor, but the driving factors are not exactly the same as in the Gulf. The country has established refining and chemical production facilities, so the demand is more about steady maintenance , instead of fast capacity growth. Industrial operations stay relatively stable, and long term asset management programs keep encouraging consistent spending on catalyst handling services. In other words, service providers get repeat maintenance cycles across mature plants which makes the business more reliable.
Meanwhile, the fastest growth momentum is showing up from developing energy markets across North and Sub-Saharan Africa. New refining investments, fuel infrastructure upgrades, and wider industrial development work have expanded catalyst service needs. Governments are also increasingly backing domestic processing capability, to reduce import reliance and improve energy security. All these changes together are creating appealing opportunities for service providers and investors who want expansion during 2026 to 2033.
Who are the Key Players in the Middle East and Africa Catalyst Handling Services Market and How Do They Compete?
Competition is still pretty moderately fragmented, like regional specialists versus multinational catalyst service providers, kind of side by side. In the end, winning is mostly about technical know how, safety record, how fast you can execute turnarounds, and whether you can actually deliver integrated catalyst lifecycle solutions. What we’re seeing more and more is that firms go after customers with automation, digital maintenance tools, and specialized reactor handling skills, not just price.
Anabeeb sort of built its strong position by leaning into refinery focused maintenance services, plus deep relationships with Middle Eastern energy operators. Mourik, on the other hand, stands out with advanced reactor services and it has been investing in automated maintenance technologies. Cat Tech is more about specialized catalyst handling know-how and quick turnaround execution, so operators can keep shutdown durations to a minimum, which sounds simple but it matters a lot.
Veolia is expanding beyond the usual handling activities by folding in catalyst recycling, regeneration, and sustainability focused services. Axens strengthens its market placement via catalyst lifecycle management, regeneration capabilities, and deeper collaboration with Eurecat. Johnson Matthey leans on catalyst technology expertise and strategic portfolio optimization, to improve its service suite for refining and petrochemical customers. Taken together, these different strategies help them land long term contracts and hold onto competitive advantages.
Company List
- CR Asia
- Cat Tech
- Anabeeb
- Altrad
- Mourik
- Veolia Catalyst Services
- HMT
- Dickinson Group
- Veolia
- BASF
- SGS
- Johnson Matthey
- Axens
- Clariant
- Albemarle
Recent Development News
In May 2025, Honeywell announced acquisition of Johnson Matthey's Catalyst Technologies business. The £1.8 billion transaction expands Honeywell's catalyst and process technology portfolio serving refining and petrochemical industries globally.https://www.honeywell.com
In October 2025, Axens announced plans to acquire full ownership of Eurecat. The move strengthens catalyst regeneration, recycling, unloading, and loading service capabilities across refining and petrochemical markets, including the Middle East.https://www.axens.ne
In October 2025, Ketjen and Axens entered new collaboration agreements involving Eurecat. The partnership extends cooperation on catalyst regeneration, processing, and advanced service technologies while supporting broader catalyst lifecycle management activities.https://www.axens.net
What Strategic Insights Define the Future of the Middle East and Africa Catalyst Handling Services Market?
The market is shifting toward more technology-enabled catalyst lifecycle management, not really the usual labor based handling services. Things like automated reactor maintenance, robotic unloading systems, catalyst traceability platforms,and predictive maintenance technologies will keep showing up in purchasing choices. This change seems to be pushed by refinery operators who want faster turnaround durations, better safety outcomes, and stronger asset utilization, basically more throughput without the usual slowdown.
One not-so-obvious risk is market concentration around big refinery projects and national oil company investments. If there are any delays in downstream capital spending or the turnaround schedules, service providers that lean on just a handful of major customers could see short term revenue wobble.
There’s also a fairly solid opportunity in integrated catalyst management services that bundle catalyst handling, regeneration, recycling, and digital performance monitoring into one single model. Providers who can deliver this kind of all-in-one package should see better customer retention and higher value contract work, not just smaller standalone engagements.
Market participants should probably focus their spending on automation, workforce training, and digital maintenance know-how. Firms that can mix real technical expertise with advanced reactor technologies are likely to be the ones that capture future growth across the region.
Middle East and Africa Catalyst Handling Services Market Report Segmentation
By Service Type
Catalyst Loading
Unloading
Screening
Replacement
Others
By Application
Refineries
Petrochemical Plants
Chemical Plants
Others
By Catalyst Type
Hydrotreating
Reforming
FCC
Others
By End User
Oil & Gas
Chemicals
Others
Frequently Asked Questions
Find quick answers to common questions.
The Expected Middle East and Africa Catalyst Handling Services Market size for the Market will be USD 987.5 Million in 2033.
Key Segments for the Middle East and Africa Catalyst Handling Services Market are By Service Type (Catalyst Loading, Unloading, Screening, Replacement, Others); By Application (Refineries, Petrochemical Plants, Chemical Plants, Others); By Catalyst Type (Hydrotreating, Reforming, FCC, Others); By End User (Oil & Gas, Chemicals, Others).
Major Middle East and Africa Catalyst Handling Services Market Players are CR Asia, Cat Tech, Anabeeb, Altrad, Mourik, Veolia Catalyst Services, HMT, Dickinson Group, Veolia, SGS, BASF, Johnson Matthey, Axens, Clariant, Albemarle.
The Current Middle East and Africa Catalyst Handling Services Market size is USD 614.7 Million in 2025.
The Middle East and Africa Catalyst Handling Services Market CAGR is 6.11% from 2026 to 2033.
- CR Asia
- Cat Tech
- Anabeeb
- Altrad
- Mourik
- Veolia Catalyst Services
- HMT
- Dickinson Group
- Veolia
- BASF
- SGS
- Johnson Matthey
- Axens
- Clariant
- Albemarle
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Active Power Filter Market
Active Power Filter Market Size, Share & Analysis Report By Type (Shunt Active Power Filters, Series Active Power Filter, Hybrid Active Power Filter), By Application (Harmonics Mitigation, Reactive Power Compensation, Voltage Regulation, Power Factor Correction), By Phase (Single Phase, Three Phase), By End-User Industry (Manufacturing, Healthcare, Commercial, Automotive, Oil and Gas, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Electrical Transformer Market
Electrical Transformer Market Size, Share & Analysis Report By Core (Closed, Shell, and Berry), By Insulation (Gas, Oil, Solid, Air, and Other), By Phase (Single, and Three), By Rating (100 MVA to 500 MVA, 501 MVA to 800 MVA, and 801 MVA to 1200 MVA), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Hydraulic Piston Pumps Market
Hydraulic Piston Pumps Market Size, Share & Analysis Report By Type (Axial Piston Pumps, Radial Piston Pumps), By Operating Pressure (Low Pressure, Medium Pressure, High Pressure), By Application (Construction, Mining, Agriculture, Automotive, Oil & Gas, Industrial Machinery, Others), By End-User (OEMs, Aftermarket), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Laboratory Gas Generators Market
Laboratory Gas Generators Market Size, Share & Analysis Report By Product (Nitrogen Gas Generator, Hydrogen Gas Generator, Zero Air Gas Generator, Purge Gas Generator, TOC Gas Generators, Others), By Application (Gas Chromatography, Liquid Chromatography-mass Spectrometry (LC-MS), Gas Analyzers, Others), By End-user (Life Science, Chemical & Petrochemical, Food & Beverage, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031