
Global Custom Display Packaging Market Size & Forecast:
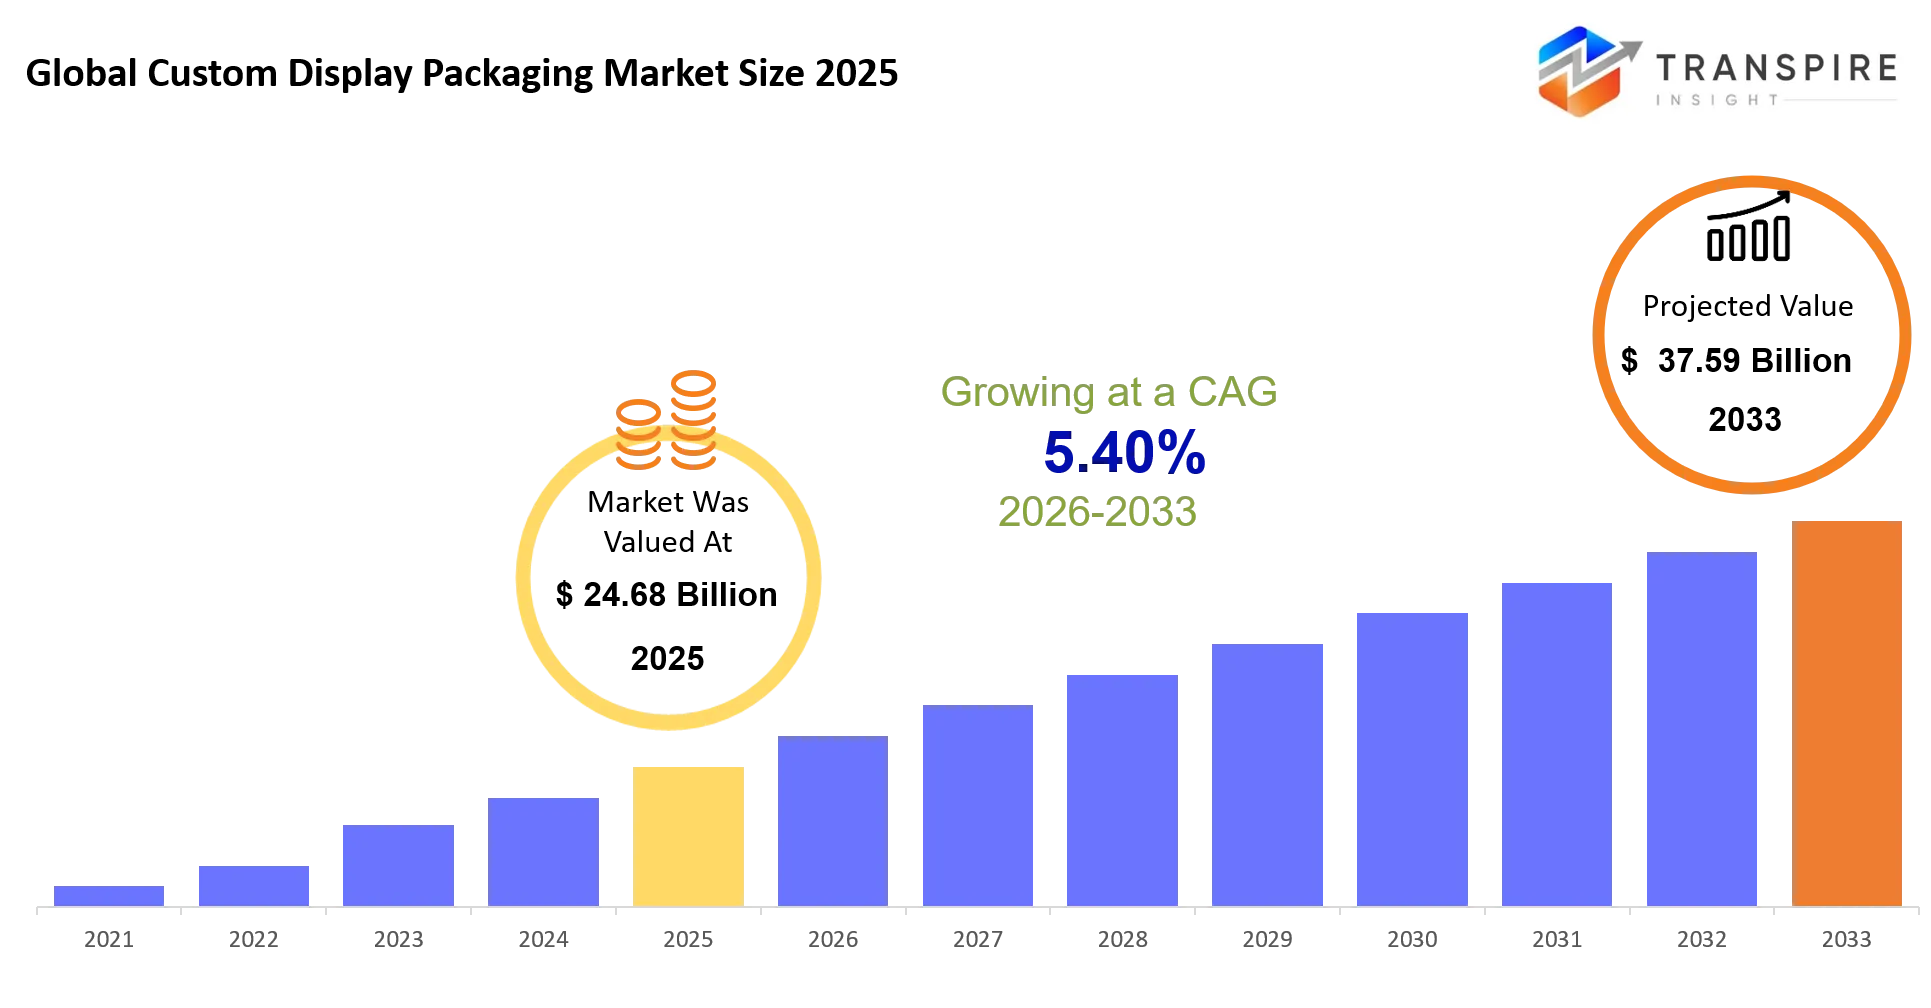
- Global Custom Display Packaging Market Size 2025: USD 24.68 Billion
- Global Custom Display Packaging Market Size 2033: USD 37.59 Billion
- Global Custom Display Packaging Market CAGR: 5.40%
- Global Custom Display Packaging Market Segments: By Material (Corrugated Board, Paperboard, Plastic, Metal, Sustainable Materials, Others); By Product (Counter Displays, Floor Displays, Pallet Displays, End-cap Displays, Dump Bins, Others); By End User (Food & Beverage, Retail, Cosmetics, Electronics, Pharmaceuticals, Others); By Printing Technology (Digital, Offset, Flexographic, Others); By Distribution (Direct Sales, Packaging Distributors, Others)
Global Custom Display Packaging Market Summary:
As per Transpire Insight Analysis, the Global Custom Display Packaging Market size is estimated at USD 24.68 Billion in 2025 and is anticipated to reach USD 37.59 Billion by 2033, growing at a CAGR of 5.40% from 2026 to 2033.
The Global Custom Display Packaging Market allows brands & retail chains to sell and sell their products with custom-made retail-ready display packaging in stores, which enhances product visibility, increases merchandising efficiency and campaigns, and promotes products in supermarkets, convenience, speciality stores, and e-commerce fulfillment channels. In the last 3-5 years, the market has transitioned from using generic POS displays towards custom-made short-run & sustainable packaging with a move towards short campaign implementation and strong store differentiation, where rapid uptake of digital printing & recyclable corrugated material is enabling cheaper custom packaging production with less waste. Real world events that were major catalysts to this have the rise in ‘omnichannel retail’ following the impact of the pandemic, prompting the reinvention of shelf-ready packaging solutions for physical store & click & collect purchasing; as a result, the market is seeing increased capital investment for custom, in-store ready display packaging solutions that build brand engagement, lower shelf stock-out times & ultimately increase in-store revenue generation.
Global Custom Display Packaging Market Insights:
Custom display packaging is transitioning from promotional packaging to an integrated retail execution platform with sustainability, digital design, and merchandising efficiency. Customisation, automated production, and new ways to display products for the retailer are becoming more important for competitive advantage than scale.
- Corrugated Displays hold 44% market share and remain dominant as Smurfit Westrock expands recyclable retail-ready solutions using automated structural design.
- North America makes up 37% of the market, and North American companies are investing in quick-turn promotional display programs as an example of premium display demand.
- Europe makes up 28% of the market and is driving the circular packaging uptake as DS Smith develops fibre-based displays to replace plastic packaging.
- Asia Pacific accounts for 26% of the market and drives digital production faster, with Mondi adding more flexible digital printing capabilities to the Asia Pacific brands.
- Floor Displays take 19% of the market share and are preferred by retailers as Creative Displays Now improves modular display solutions for seasonal promotions.
- Counter Displays make up 15% of the market, offering high levels of impulse merchandising, and Sonoco is focusing on lightweight but robust structural packaging technologies.
- Sustainable Materials are expected to expand at a 15.8% CAGR for the next five years as Stora Enso introduces renewable fibre solutions that lower carbon footprints.
- Digital Printing remains the replacement of traditional production as Packaging Corporation of America embraces short-run customization and quicker artwork changes.
What are the Key Drivers, Restraints, and Opportunities in the Global Custom Display Packaging Market?
Driver:
This is being facilitated by modern retail merchandising being geared to experience rather than standard shelving. Mega-retailers have been driving demand for ready-to-display, retail-ready product packaging, which reduces replenishment costs, labour in-store, and increases promotional exposure during seasonal promotions. Increased proliferation of organised retail (chain stores), club stores, convenient stores has made the FMCG (Fast-moving consumer goods) sector invest in brand-aligned logistics and optimized display packs. Also, digital printing of cost-effective short run lengths permits marketing teams to use local, regional campaigns with minimal inventory, which drives better pack utility and increased revenues.
In June 2026, the DPIIT and ONDC Action partnered with FMCG industry leaders to launch the DigiDukaan initiative. This deployment digitises the general trade ecosystem by connecting thousands of small-format retailers directly with FMCG brand catalogues, enabling localised inventory management and streamlined regional promotional rollouts.
Restraint:
However, demand is tempered by the difficulty & expense of high levels of customisation, both across SKU configurations, formats, & Retailers, requiring manufacturers to weigh design agility against product protection, plus addressing sustainability and retailers' specific requirements for pack format. Such design & structural complexity demand frequent tooling adjustments and unique design talent, impacting the ability of smaller suppliers to participate in highly customised orders due to being at the necessary scale.
Opportunity:
Continued growth is anticipated at the crossroads of smart packaging, sustainability, and data-driven retail merchandising. Investment in sustainable recycled fibre-based materials paired with QR codes, NFC tags, and interactive digital content is driving value beyond physical product presentations. Developing retail markets throughout Southeast Asia, Latin America, and the Middle East will see greater organised retail build-out, providing new avenues of opportunity for suppliers of innovative display packaging. Furthermore, AI-powered structural design and automation of digital workflows will empower manufacturers to deliver tailor-made display solutions faster while reducing material waste and manufacturing costs.
In May 2026, N8N secured a strategic investment from SAP. The multi-year partnership integrating N8N into SAP's Joule Studio AI platform enables manufacturers to automate design workflows and streamline tailor-made display solution delivery, reducing material waste and costs.
What Has the Impact of Artificial Intelligence Been on the Global Custom Display Packaging Market?
Artificial intelligence has improved how display packaging is constructed, produced, and positioned in retail spaces by leveraging it across the entire supply chain. AI design tools calculate packaging based on product size, weight distribution, transportation variables and the retailer’s display environment to provide more efficient packaging solutions. Machine learning applications can forecast demand and allocate appropriate manufacturing schedules to digital printing and finishing operations to limit idle capacity. Predictive analytic technology helps brands to identify and implement preferred display types based on anticipated consumer behaviour, seasonal variations and the retailer’s promotional calendar. Computer vision allows for real-time inspection of printing errors and material defects to cut waste and optimize efficiency in printing. Computer intelligence also predicts raw material orders to avoid potential supply shortages and optimise material inventories and the space to store them. However, this adoption rate is currently being limited due to high costs for implementation, compatibility issues between older packaging equipment and AI software, and a lack of sufficient and consistent data collection at various production stages. Small-scale packaging converters frequently lack the infrastructure necessary to fully adopt AI’s optimisations, despite proving to enhance efficiencies.
Global Custom Display Packaging Market Trends:
Custom display packaging is not just about presentation; it is now a comprehensive retail marketing solution that enhances efficiency, sustainability, and shopper engagement. Customization using technology and eco-friendly materials is transforming competitive strategy for packaging manufacturers.
- Retail-ready displays that cut down on shelf replenishment time and enhance promotional execution are increasingly preferred by retailers.
- Digital printing has enabled the move from long standardized runs to short-run campaigns with a low investment.
- As sustainability pledges turn into buying criteria, corrugated structures are steadily taking the place of plastic displays.
- Brands are increasingly creating displays that are physically as well as omnichannel-ready.
- QR-enabled consumer engagement is becoming a part of promotional packaging strategies.
- Structural engineering, powered by AI, is cutting material usage whilst enhancing load-bearing capability compared with previous designs.
- Rather than traditional display aesthetics, premium graphics and high-definition printing are taking their place, enhancing the ability to differentiate on the shelf.
- Rather than just production, packaging suppliers are increasingly providing end-to-end design, manufacturing, logistics and installation services.
Global Custom Display Packaging Market Segmentation
By Material:
Corrugated Board continues to dominate, due to its rigidity, recyclability, and price point, and accounts for 44% of total demand, and is seen in a variety of retailers. Paperboard grows as brands continue to leverage it for lighter-weight promotional applications, and plastic is the choice for applications that require moisture resistance and strength. Metal applications are geared for premium long-term installations that require higher structural integrity. The largest growth segment, however, is Sustainable Materials and shows a compound annual growth rate of 15.8% as brand owners and retailers focus on recyclable and bio-based display options.
By Product:
19% of all displays are Floor Displays, the popular option for increased product visibility and point of purchase campaigns. Counter Displays represent 15% due to impulse buy scenarios, whereas 10% is Pallet Displays utilised for efficient product transportation. End Cap Displays are becoming increasingly valuable and will become even more important as they attract shopper attention and traffic. Dump bins remain an effective alternative, with custom-built displays available to cater to specific merchandising strategies.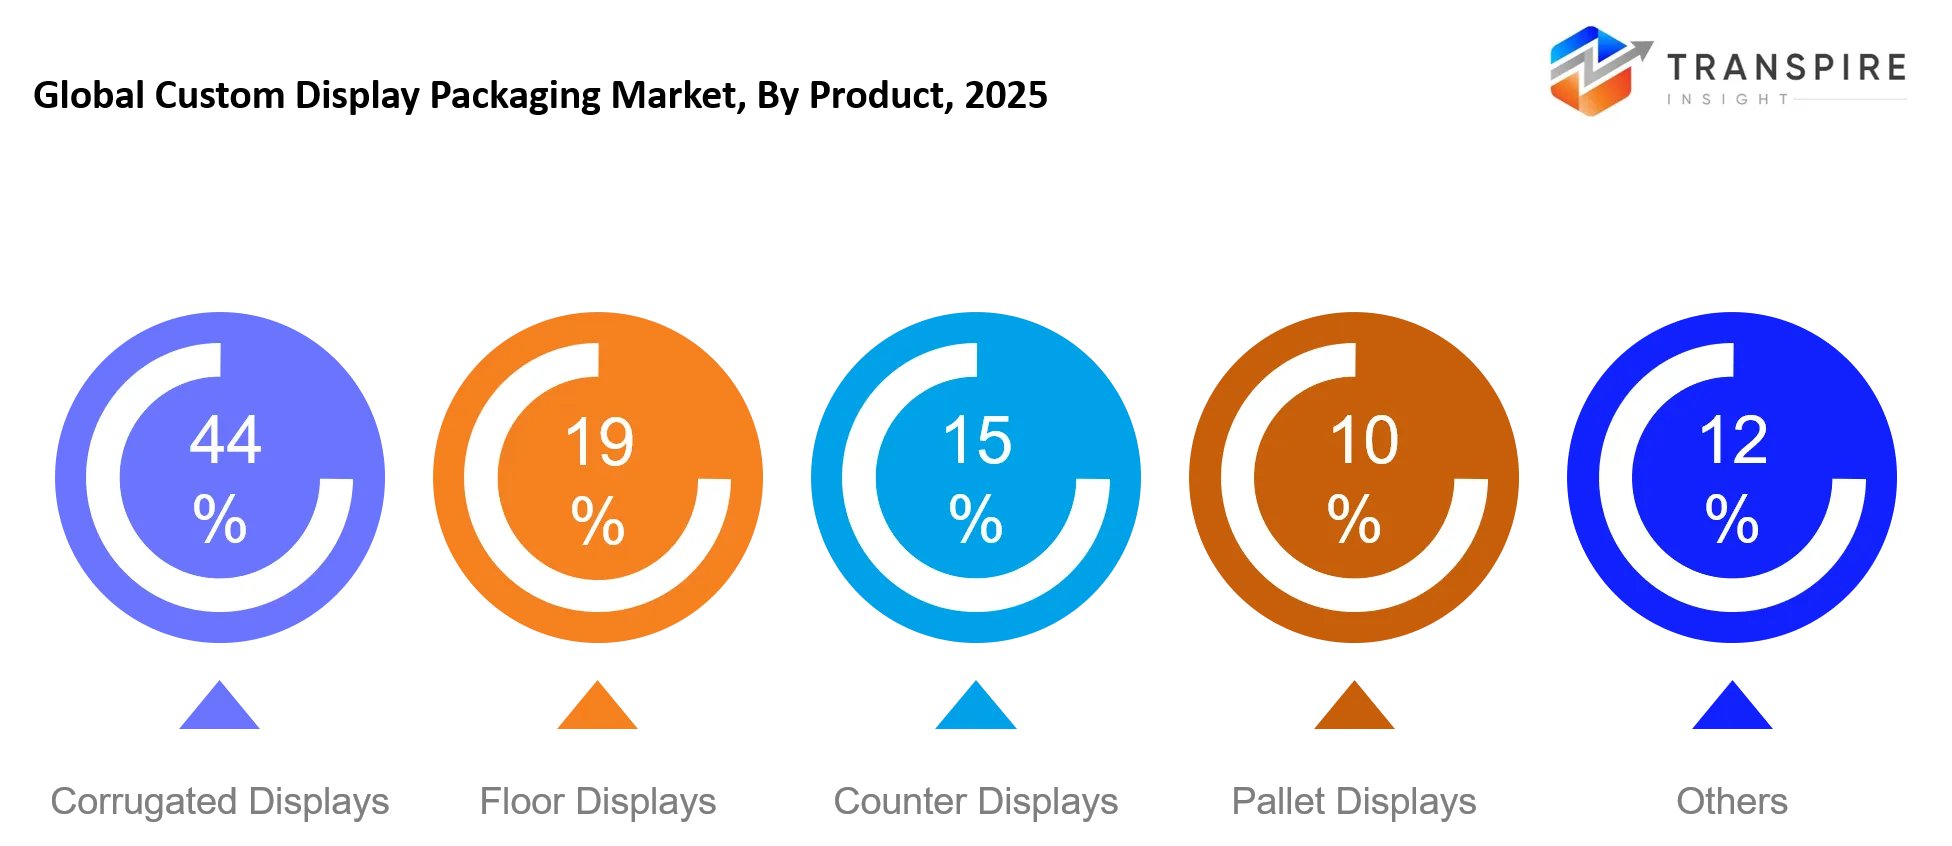
By End User:
Food & Beverage leads due to the regularity of promotional activity, then Retail to gain merchandising efficiency. Cosmetics benefit from upscale displays; Electronics need to present branded merchandise; Pharmaceuticals use compliance systems for display systems under secure packaging rules; Others continue to increase display packaging investment to showcase product differentiations.
By Printing Technology:
The greatest growth was in digital printing due to custom and short-run production. Offset printing maintains premier graphics for long-run, large-campaign orders, and flexographic is the best for high volumes on corrugated, and the remaining printing technology is utilised to accomplish very unique finishing needs.
By Distribution:
Direct Sales are expected to keep a leadership position in tailored projects co-developed with manufacturers and brand owners, Packaging Distributors will increase local penetration within a market segment, and alternative distribution channels will continue to support small commercial orders.
What are the Key Use Cases Driving the Global Custom Display Packaging Market?
The key application area is in corrugated retail display packaging where retailers utilise in-store promotional retail-ready displays to minimise in-store stocking time while optimising consumer visibility of their food and beverages and consumer-packaged goods.
The emerging application of custom-design floor displays, countertop displays, and end-cap applications across cosmetics, electronics, and pharma, as well as specialty retail, to improve branding and brand-consumer interaction as well as seasonal product launches.
Emerging applications of sustainable retail displays continue to drive market growth in addition to smart digitally printed displays with QR codes, personalisation, and interactive consumer elements that assist in omnichannel initiatives, limited-edition products, and locale-specific promotion.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 24.68 Billion |
|
Market size value in 2026 |
USD 26.01 Billion |
|
Revenue forecast in 2033 |
USD 37.59 Billion |
|
Growth rate |
CAGR of 5.40% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United States; Canada; Mexico; United Kingdom; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; United Arab Emirates |
|
Key company profiled |
Smurfit Westrock, DS Smith, Mondi, International Paper, Sonoco, Georgia-Pacific, WestRock, Stora Enso, Menasha Packaging, Pratt Industries, Packaging Corporation of America, Fencor Packaging, Creative Displays Now, Great Northern, UFP Packaging |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Material (Corrugated Board, Paperboard, Plastic, Metal, Sustainable Materials, Others); By Product (Counter Displays, Floor Displays, Pallet Displays, End-cap Displays, Dump Bins, Others); By End User (Food & Beverage, Retail, Cosmetics, Electronics, Pharmaceuticals, Others); By Printing Technology (Digital, Offset, Flexographic, Others); By Distribution (Direct Sales, Packaging Distributors, Others) |
Which Regions are Driving the Global Custom Display Packaging Market Growth?
North America holds 37% of the worldwide market – the highest share among all regions. The region's competitive advantages include strong, mature retail supply chains; extensive converting infrastructure; and extensive use of in-store merchandising and consumer packaged goods (CPGs) that constantly invest in in-store branding and promotion enhancement capabilities to ensure optimal performance of promotional activities. A solid and robust recycling infrastructure and retailer sustainability plans complement ongoing investments in automation, all of which suggest leadership. In February 2026, Unilever formed a five-year partnership with Google Cloud to inject generative AI into its global consumer goods technologies. This collaboration empowers Unilever to accelerate brand innovation and optimize supply chain operations directly at the retail level across North America.
Europe represents 28% of global demand and maintains a stable competitive position through sustainability-driven packaging innovation. Compared with North America, European growth is influenced more by environmental regulations and circular economy objectives than by promotional spending. Mature manufacturing capabilities and strong collaboration between packaging converters and retailers support product innovation. Continuous investment in recyclable materials sustains regional competitiveness despite slower retail expansion.
In May 2026, Coveris acquired GEFO Folienbetrieb GmbH, strengthening its German-based recyclable cast polypropylene (CPP) film manufacturing footprint to meet rising demand and comply with European regulations.
The Asia Pacific region constitutes 26% of the global market and has the fastest CAGR growth rate of 16.9%. With urbanisation and formalisation of the retail space, consumer preference for personalised packaging design, and a growing demand for display packaging in nascent markets have picked up pace. Increased spending on automation and digital printing processes is offering enhanced flexibility. Greater international market penetration and the increasing trend of branded retailers’ focus on brand localisation create strong future potential for local packaging manufacturers.
In April 2026, Veritiv Operating Company partnered with Packsize to deploy on-demand automated packaging systems across Asia Pacific, enabling brands to reduce waste and accelerate production.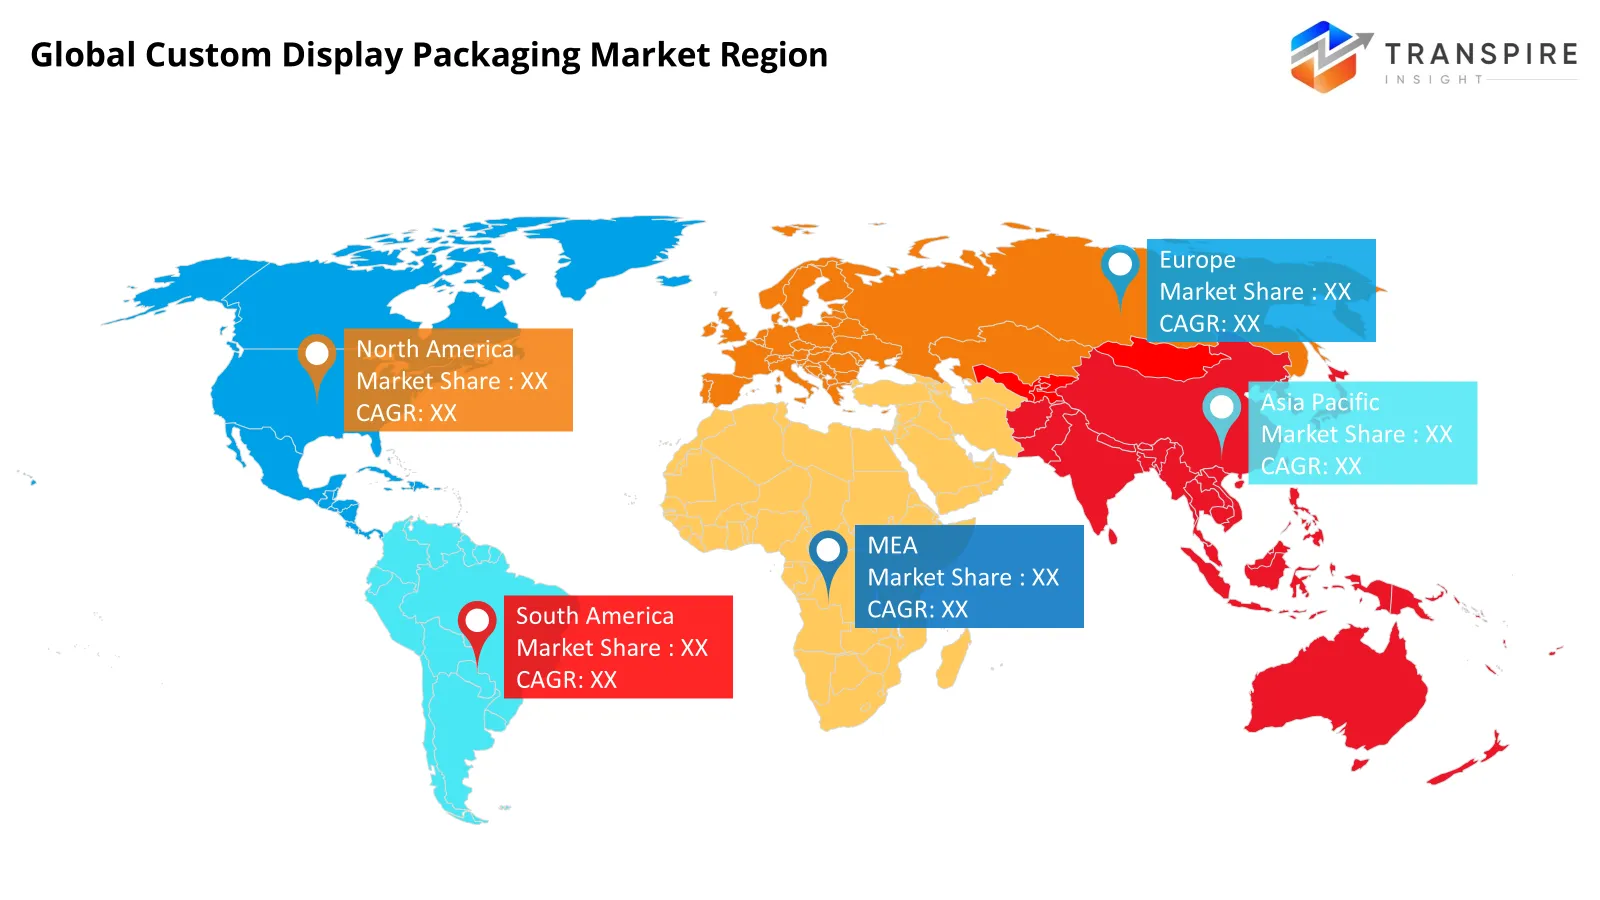
Who are the Key Players in the Global Custom Display Packaging Market, and how do they compete?
Competition focus remains on design expertise, material innovation for sustainability, operational manufacturing efficiencies, speed of delivery, and not only cost. The focus now revolves around the offering of integrated package design solutions, digital printing, structural engineering, and custom-made in-store, retailer-specific merchandising that builds on existing long-term customer relationships.
Smurfit Westrock, DS Smith, and Mondi; will continue to compete with their focus on innovation in fibre-based packaging sustainability and custom made retail-ready solutions, will achieve expansion through capital investments into new digital converting machines and sustainable, recyclable materials; whereas International Paper, Georgia-Pacific, Packaging Corporation of America, and Pratt Industries; will focus their competition through operational efficiencies and large-scale, cost-efficient corrugated packaging production and by extending their regional converting operations. Niche competitors such as Sonoco, Stora Enso, Menasha Packaging, Great Northern, Fencor Packaging, Creative Displays Now, and UFP Packaging will expand by specialising in value-added solutions that focus on design (structural/engineering), quick lead times on packaging, POS, and custom retail solutions, while building deeper relationships with e-commerce solutions and by expanding their use of digital capabilities and automation.
Key Players are:
- Smurfit Westrock
- DS Smith
- Mondi
- International Paper
- Sonoco
- Georgia-Pacific
- WestRock
- Stora Enso
- Menasha Packaging
- Pratt Industries
- Packaging Corporation of America
- Fencor Packaging
- Creative Displays Now
- Great Northern
- UFP Packaging.
Recent Development News on the Global Custom Display Packaging Market
- In June 2026, TRG Packaging and Display Solutions launched its newly integrated BHS Jetliner Xceed digital printing system into full production. This advanced technology implementation enables the company to expand material versatility from microflute to honeycomb boards.
- In March 2026, Smurfit Westrock completed an asset purchase agreement to acquire Cartomanabí, a prominent corrugated packaging supplier based in Ecuador. This transaction marks the company's first major acquisition as the combined Smurfit Westrock entity.
- In January 2026, Mondi plc finalised the broader commercial roll-out of its localised fibre-based transport and retail-ready shelf display configurations within Central European supermarket networks. This strategic operational scaling supports regional consumer goods distribution channels by replacing heavy plastics.
https://www.grocerytradenews.com
What Strategic Insights Define the Future of the Global Custom Display Packaging Market?
Trends in the packaging world favour smart, green, and digitally-created in-store displays that bring retail visibility and manufacturing efficiencies together. Future viability will more so rely on AI-powered structural engineering, versatility from digital print, and environmentally friendly, printable packaging that satisfies retailers’ sustainability metrics with superior display execution. There is a lurking threat where uncertain raw fibre and paper material prices, coupled with tightening regulations, may squeeze the profitability of less flexible producers. On the flip side, however, there is growth for connected packaging that uses the technology in QR code display, consumer personalised marketing messages, and smart data capture, taking it beyond traditional product presentations. It behoves businesses to invest in automation for production processes, a modular system for display formats, and progressive printing for speedy, customised regional display merchandising, working closely with retailers, packaged goods makers, and new material manufacturers.
Key Segmentations are:
By Material
- Corrugated Board
- Paperboard
- Plastic
- Metal
- Sustainable Materials
- Others
By Product
- Counter Displays
- Floor Displays
- Pallet Displays
- End-cap Displays
- Dump Bins
- Others
By End User
- Food & Beverage
- Retail
- Cosmetics
- Electronics
- Pharmaceuticals
- Others
By Printing Technology
- Digital
- Offset
- Flexographic
- Others
By Distribution
- Direct Sales
- Packaging Distributors
- Others
Regional Outlook
North America
- United States
- Canada
- Mexico
Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
Asia Pacific
- Japan
- China
- Australia & New Zealand
- South Korea
- India
- Rest of Asia Pacific
South America
- Brazil
- Argentina
- Rest of South America
Middle East & Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of the Middle East & Africa
Frequently Asked Questions
Find quick answers to common questions.
The Global Custom Display Packaging Market size was valued at USD 24.68 Billion in 2025 and is poised to reach USD 37.59 Billion by 2033, expanding at a 5.40% CAGR.
Key segments for the Global Custom Display Packaging Market are By Material (Corrugated Board, Paperboard, Plastic, Metal, Sustainable Materials, Others); By Product (Counter Displays, Floor Displays, Pallet Displays, End-cap Displays, Dump Bins, Others); By End User (Food & Beverage, Retail, Cosmetics, Electronics, Pharmaceuticals, Others); By Printing Technology (Digital, Offset, Flexographic, Others); By Distribution (Direct Sales, Packaging Distributors, Others).
Growth is primarily driven by organised retail expansion, digital printing adoption, sustainable packaging investments, and increasing demand for retail-ready merchandising solutions that improve in-store sales efficiency.
The Global Custom Display Packaging Market is led by major manufacturers, including Smurfit WestRock, DS Smith, Mondi, International Paper, Sonoco, Georgia-Pacific, WestRock, Stora Enso, Menasha Packaging, Pratt Industries, Packaging Corporation of America, Fencor Packaging, Creative Displays Now, Great Northern, and UFP Packaging.
North America holds 37% of the global market, supported by advanced retail infrastructure, strong sustainability initiatives, high promotional packaging adoption, and continuous investment in automated packaging technologies.
Key opportunities include smart QR-enabled display packaging, AI-driven design automation, recyclable fibre-based solutions, digital short-run printing, and expansion across emerging organised retail Markets.
- Smurfit Westrock
- DS Smith
- Mondi
- International Paper
- Sonoco
- Georgia-Pacific
- WestRock
- Stora Enso
- Menasha Packaging
- Pratt Industries
- Packaging Corporation of America
- Fencor Packaging
- Creative Displays Now
- Great Northern
- UFP Packaging.
About the Authors

Kartik bhong
I am Kartik Bhong, a Senior Research Analyst at Transpire Insight, specializing in the Packaging, Manufacturing, and Construction industry. My work focuses on analyzing market trends, emerging technologies, industry regulations, and competitive landscapes to deliver accurate, data-driven insights. I am passionate about transforming complex industry information into clear, practical content that helps businesses, professionals, and decision-makers stay informed and make confident strategic decisions. Through continuous research and a strong commitment to accuracy, I strive to create reliable, well-researched content that reflects the latest developments across these dynamic industries and supports the vision of Transpire Insight in delivering valuable market intelligence.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Pharmaceutical Cold Chain Packaging Market
Pharmaceutical Cold Chain Packaging Market By Material (Plastic,(Polyethylene (PE), Polypropylene (PP), Polyethylene Terephthalate (PET), Expanded Polystyrene (EPS), Polyurethane (PU),Others), Paper, Metal, Others), By Product (Small Boxes, Pallets, Large Sized Pallet Containers, Others), By End Use (Biopharmaceutical Companies, Clinical Research Organizations, Hospitals, Research Institutes, Logistics and Distribution Companies, Others)”, By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2026-2033
-
Apr 2026
Active & Intelligent Packaging Market
Active & Intelligent Packaging Market By Type (Active Packaging, Smart Packaging), By Material (Polymer-Based, Paper & Board-Based, Metal-Based, Glass-Based), By Technology (Time-Temperature Indicators, Freshness Indicators, RFID, Antimicrobial Packaging, Modified Atmosphere Packaging), By Application (Food & Beverages, Pharmaceutical, Cosmetics & Personal Care, Electronics & Consumer Goods, Others), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2026-2033
-
Apr 2026
Biodegradable Cut Flower Packaging Market
Biodegradable Cut Flower Packaging Market By Material Type (Paper & Paperboard, Biodegradable Plastics, Natural Fibers, Molded Pulp, Others), By Product Type (Sleeves, Wraps, Boxes & Cartons, Bags & Pouches, Inserts & Holders), By Application (Roses, Carnations, Tulips, Chrysanthemums, Mixed Flowers, Others) and By Distribution Channel (Direct Sales, Distributors & Wholesalers, Online Channels), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2026-2033
-
May 2026
Pharmaceutical Packaging Market
Pharmaceutical Packaging Market By Material Type (Plastic, Glass, Metal, Paper & Paperboard, Others), By Packaging Type (Bottles, Blister Packs, Vials, Ampoules, Pouches & Sachets, Others) and By End User (Hospitals & Clinics, Retail Pharmacies, Online Pharmacies, Pharmaceutical Manufacturers), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2026-2033