
Asia Pacific Stainless Steel Forgings Market Size & Forecast:
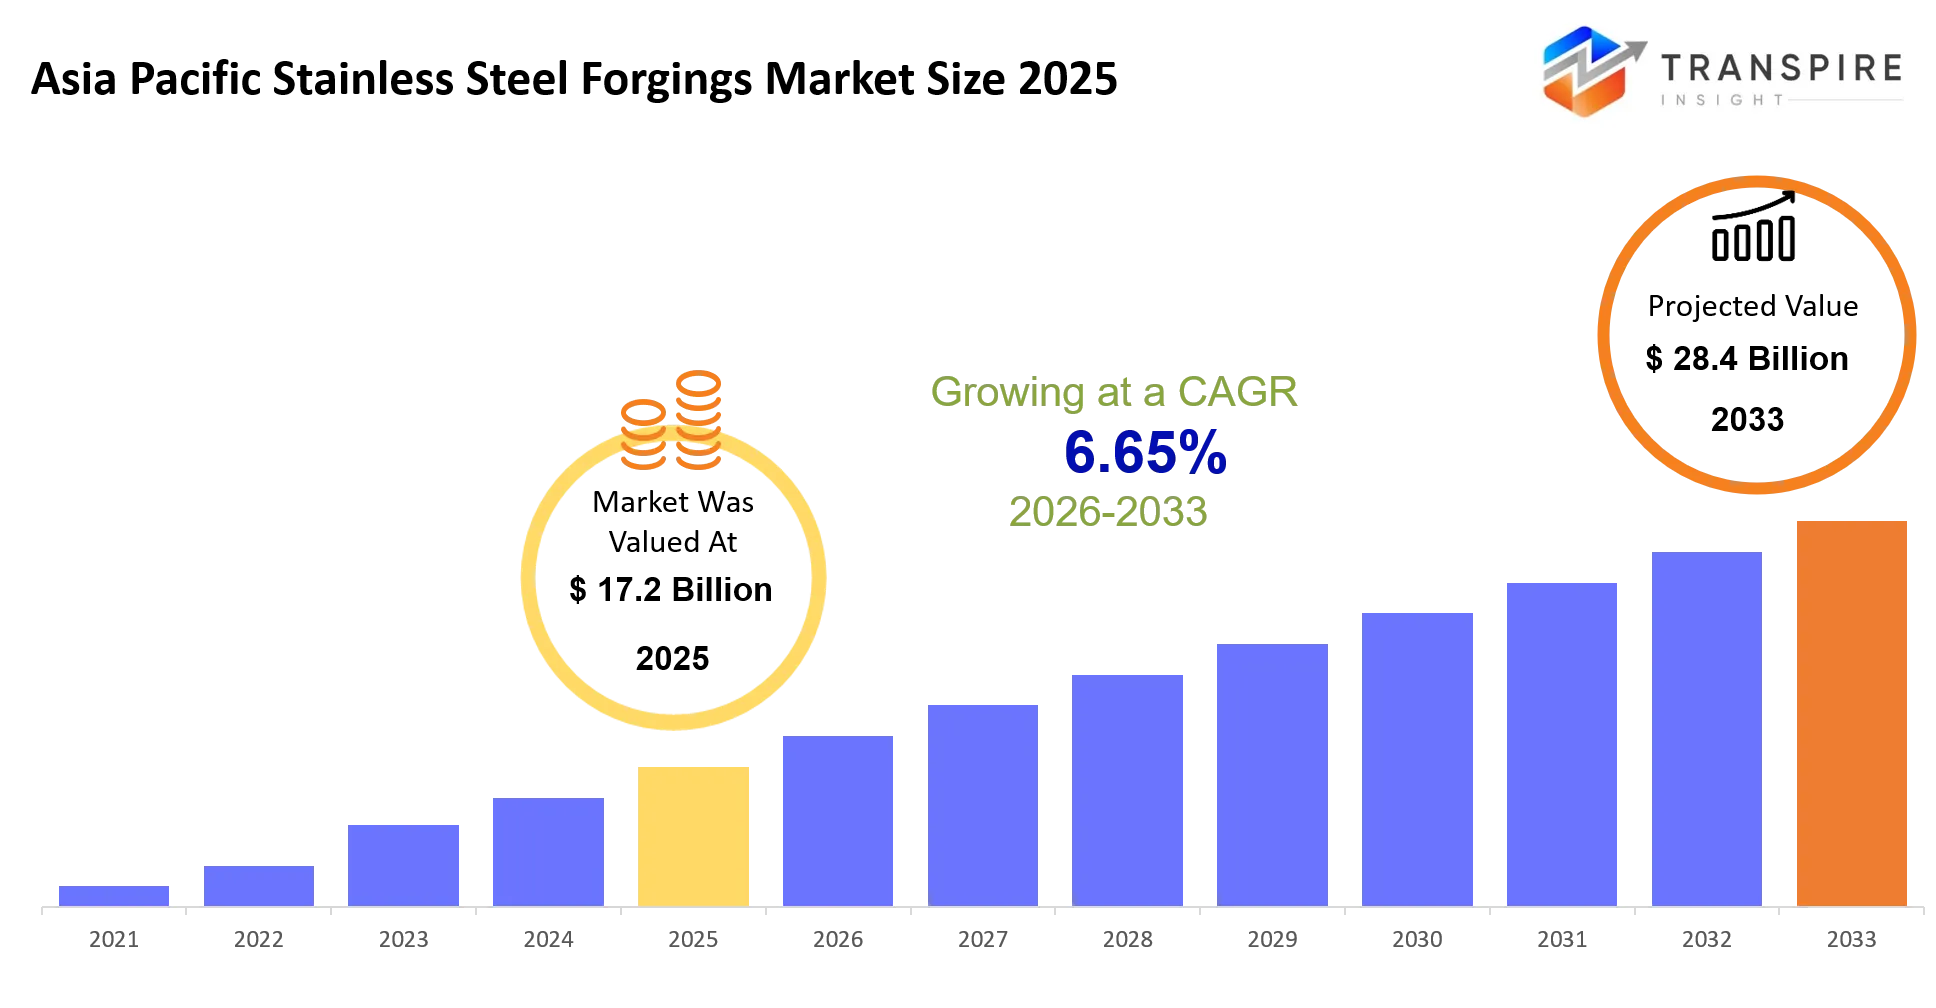
- Asia Pacific Stainless Steel Forgings Market Size 2025: USD 17.2 Billion
- Asia Pacific Stainless Steel Forgings Market Size 2033: USD 28.4 Billion
- Asia Pacific Stainless Steel Forgings Market CAGR: 6.65%
- Asia Pacific Stainless Steel Forgings Market Segments: By Product Type (Open Die Forgings, Closed Die Forgings, Rolled Rings, Shafts, Discs, Flanges, Others); By Grade (Austenitic, Ferritic, Martensitic, Duplex, Others); By Application (Oil & Gas, Aerospace, Automotive, Power Generation, Marine, Others); By End User (Industrial Manufacturers, OEMs, Energy Sector, Others)
Asia Pacific Stainless Steel Forgings Market Summary
The Asia Pacific Stainless Steel Forgings Market was valued at USD 17.2 Billion in 2025. It is forecast to reach USD 28.4 Billion by 2033. That is a CAGR of 6.65% over the period.
The Asia Pacific Stainless Steel Forgings Market supplies high-strength, corrosion-resistant components that keep critical industrial systems operating reliably in demanding environments. Forged stainless steel parts such as flanges, shafts, rings, valves, and pressure-bearing components are widely used in energy, marine, chemical processing, oil and gas, and heavy manufacturing applications where failure is costly and safety requirements are stringent.
Over the past few years, the market has undergone a structural shift toward higher-performance forged components designed for harsh operating conditions, longer service life, and stricter quality certification standards. At the same time, supply chain disruptions triggered by the COVID-19 pandemic and subsequent raw material volatility exposed weaknesses in global sourcing networks, prompting manufacturers and end users to diversify suppliers and strengthen regional production capabilities.
Current growth is being driven by industrial modernization projects, expanding energy infrastructure, and investment in process industries. As operators prioritize durability, maintenance reduction, and lifecycle cost optimization, forged stainless steel components are being specified more frequently, supporting higher-value contracts and stronger revenue opportunities across the regional supply chain.
Key Market Insights
- China dominates the Asia Pacific Stainless Steel Forgings Market with over 40% market share in 2025, supported by its extensive manufacturing and industrial base.
- India is projected to be the fastest-growing country through 2030, driven by refinery projects, industrial expansion, and infrastructure investments.
- Southeast Asia is emerging as a key growth hub as manufacturing relocation and export-oriented production increase forging requirements.
- Japan and South Korea retain significant market positions through advanced metallurgical expertise and precision forging capabilities.
- Closed die forgings lead the market with nearly 35% share in 2025 due to superior strength, accuracy, and performance characteristics.
- Flanges represent the second-largest product category, supported by widespread use across pipelines, processing plants, and industrial facilities.
- Rolled rings are forecast to be the fastest-growing segment between 2025 and 2030, benefiting from renewable energy and heavy equipment demand.
- Demand for shafts and discs continues to grow as industries prioritize operational reliability and longer equipment life cycles.
- Oil and gas remains the largest application segment, accounting for approximately 30% of market revenue in 2025.
- Chemical processing industries generate substantial demand for stainless steel forgings because of strict corrosion resistance requirements.
What are the Key Drivers, Restraints, and Opportunities in the Asia Pacific Stainless Steel Forgings Market?
The primary force accelerating the Asia Pacific Stainless Steel Forgings Market is the expansion of energy, process manufacturing, and industrial infrastructure projects that require components capable of operating under high pressure, temperature, and corrosive conditions. This trend gained momentum as governments across China, India, and Southeast Asia increased investments in power generation, refining, petrochemicals, and industrial facilities to strengthen economic resilience and energy security. Stainless steel forgings offer longer service life and lower maintenance costs than many alternative materials, making them a preferred choice for critical applications. As project developers prioritize reliability and lifecycle performance, forged components command higher-value contracts, directly supporting market revenue growth.
Raw material price volatility remains the most significant structural barrier. Stainless steel production depends heavily on nickel, chromium, and other alloying elements whose prices are influenced by global supply concentration, geopolitical tensions, and mining constraints. Forging manufacturers often face compressed margins when alloy costs fluctuate rapidly, while end users delay procurement decisions due to uncertain project economics. Because new mining capacity and alternative supply chains require years of development, this challenge cannot be resolved quickly. The result is slower capital investment and postponed equipment replacement cycles, which suppress market expansion.
Renewable energy infrastructure presents a major long-term opportunity. Offshore wind projects, hydrogen production facilities, and advanced energy systems increasingly require corrosion-resistant forged components. India and several Southeast Asian countries are accelerating investments in these sectors, creating favorable conditions for specialized stainless steel forging manufacturers to capture new high-value applications and diversify beyond traditional industrial markets.
What Has the Impact of Artificial Intelligence Been on the Asia Pacific Stainless Steel Forgings Market?
Artificial intelligence and advanced digital technologies are transforming stainless steel forging operations across Asia Pacific by improving production efficiency, quality control, and equipment reliability. Manufacturers are increasingly deploying AI-enabled process control systems that monitor forging temperatures, press loads, die conditions, and material flow in real time. These systems automatically adjust operating parameters to maintain product consistency and reduce scrap rates, particularly in high-specification forgings used in energy, marine, and chemical processing applications.
Machine learning models are also strengthening predictive maintenance programs. By analyzing vibration patterns, hydraulic pressure data, and equipment operating histories, manufacturers can identify early signs of wear in forging presses, heat-treatment furnaces, and machining systems before failures occur. This approach helps reduce unplanned downtime, extend equipment life, and improve production scheduling. Some facilities report double-digit reductions in maintenance-related stoppages and measurable improvements in overall equipment effectiveness.
Digital twins and advanced analytics are further enhancing operational performance by simulating production conditions and identifying opportunities to optimize energy consumption, throughput, and material utilization. These improvements contribute to lower operating costs and more reliable delivery schedules.
However, AI adoption still faces a significant limitation. Integrating advanced analytics platforms with legacy forging equipment requires substantial investment, while inconsistent production data and limited historical datasets can reduce model accuracy, particularly in smaller manufacturing facilities.
Key Market Trends
Asia Pacific Stainless Steel Forgings Market Segmentation
By Product Type:
Open die forgings maintain strong demand in heavy industrial applications where large custom components require high strength and structural reliability. Industries such as power generation, mining, and process manufacturing continue to utilize these products for critical equipment. Demand remains supported by projects that require specialized dimensions and enhanced mechanical performance.
Closed die forgings hold a significant position because of superior precision, consistency, and material efficiency. Rolled rings continue to gain acceptance in energy, industrial machinery, and engineering applications due to excellent load-bearing characteristics. Shafts and discs support rotating equipment and heavy machinery, while flanges remain essential for pipeline and process plant operations.
Other product categories serve specialized requirements across marine, chemical processing, and manufacturing sectors. Product development efforts increasingly focus on durability, performance, and longer operational life. Investment in advanced forging technologies will continue to improve product quality and manufacturing efficiency across multiple end-use industries.
By Grade:
Austenitic grades account for a substantial share of consumption because of strong corrosion resistance, weldability, and versatility. Chemical processing, food processing, and industrial equipment applications frequently utilize these grades. Consistent performance in demanding operating conditions supports long-term adoption across multiple industries.
Ferritic grades offer cost advantages and adequate corrosion resistance for selected industrial applications. Martensitic grades remain important where high hardness, wear resistance, and mechanical strength are required. Duplex stainless steel continues to attract attention because of the combination of strength and corrosion resistance, particularly in aggressive operating environments.
Precipitation hardening grades support applications requiring exceptional strength and durability. Growing emphasis on operational efficiency encourages wider use of advanced stainless steel grades. Material selection increasingly depends on lifecycle performance, maintenance requirements, and operating conditions rather than initial procurement costs alone.
By Application:
Oil and gas applications continue to generate substantial demand for forged stainless steel components because of harsh operating environments and strict safety requirements. Equipment reliability remains a key factor in procurement decisions throughout upstream, midstream, and downstream operations. Corrosion resistance and long service life support continued usage across critical installations.
Chemical processing facilities utilize forged components in systems exposed to corrosive substances and challenging process conditions. Power generation projects rely on durable materials capable of performing under elevated temperatures and pressures. Marine applications also require components that withstand prolonged exposure to moisture and corrosive environments.
Aerospace and industrial machinery sectors create opportunities for high-performance forged products with strict quality specifications. Expanding infrastructure and industrial investment support broader application across manufacturing activities. Demand patterns increasingly favor products that improve operational reliability and reduce maintenance frequency.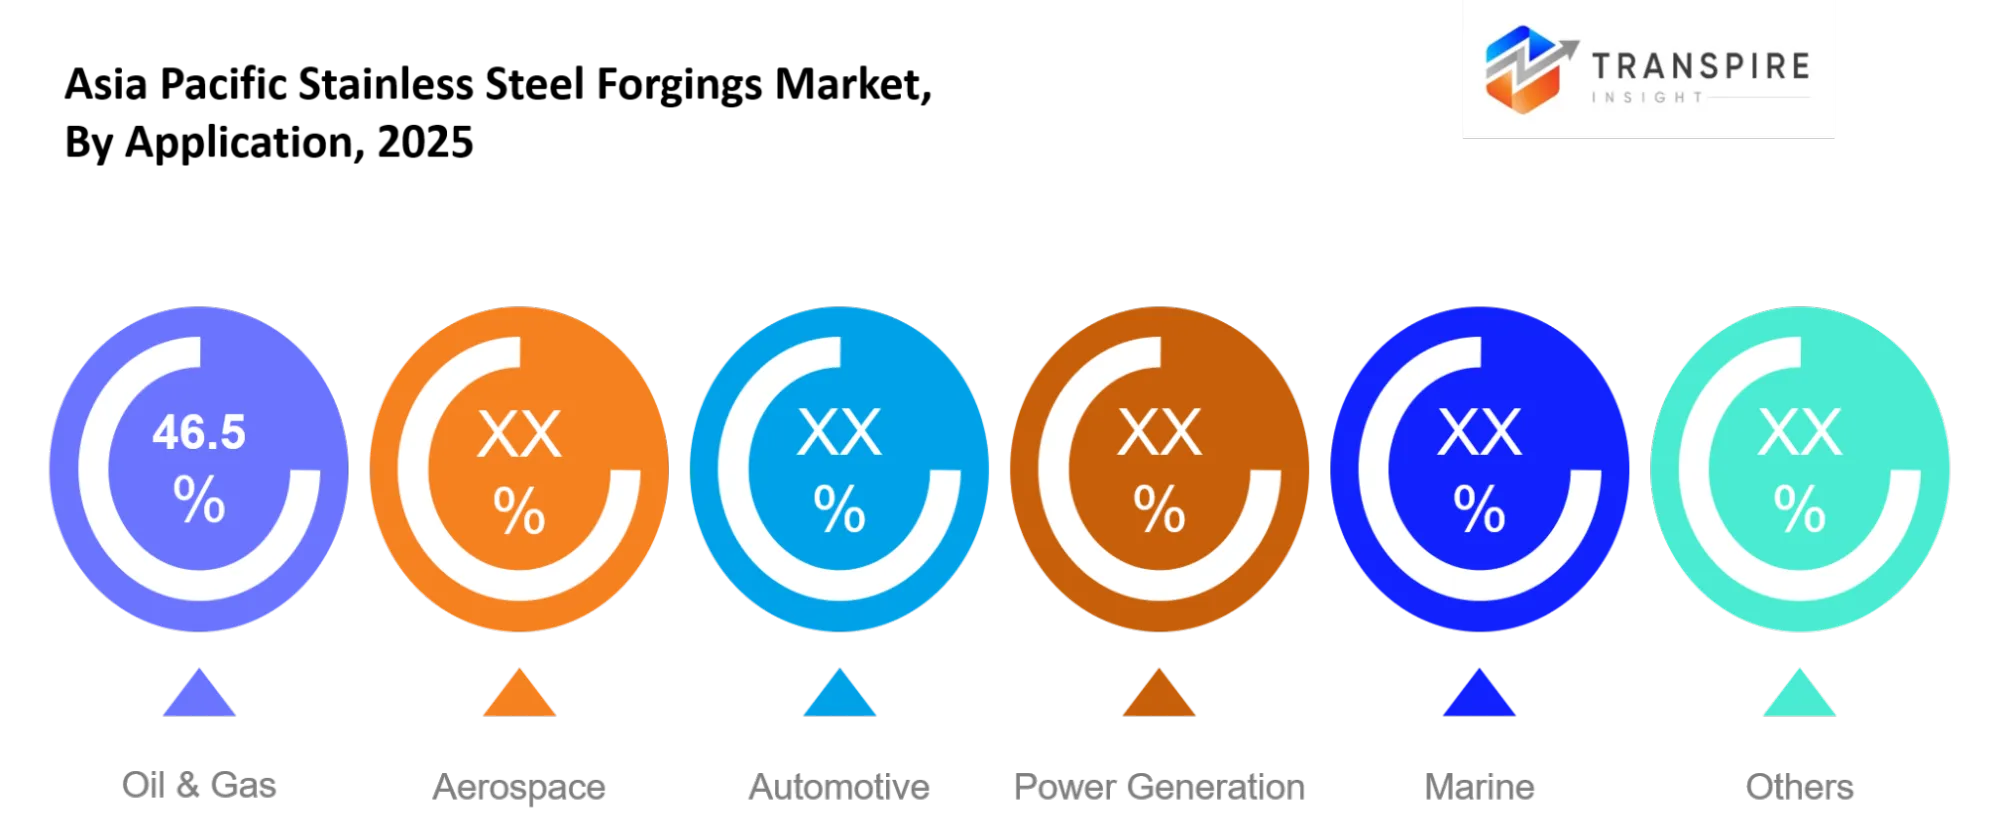
By End User:
The energy sector represents a major end user due to ongoing investment in power generation, refining, and related infrastructure. Operational reliability remains a primary requirement for equipment operating under demanding conditions. Forged stainless steel components support long-term performance and maintenance efficiency within critical systems.
Industrial manufacturing continues to utilize a wide range of forged products across production facilities and heavy machinery applications. Marine and shipbuilding activities require durable components capable of handling corrosive operating conditions and continuous exposure to challenging environments. Aerospace and defense applications maintain strict standards for quality, precision, and material performance.
The chemical industry relies on corrosion-resistant forged products to support safe and efficient processing operations. Other end-user categories include engineering, infrastructure, and specialized industrial activities. Continued modernization efforts across these sectors will support steady adoption of advanced forged stainless steel solutions in the coming years.
What are the Key Use Cases Driving the Asia Pacific Stainless Steel Forgings Market?
The largest share of forged stainless steel component usage comes from oil and gas processing facilities, where valves, flanges, shafts, and pressure-containing equipment operate under extreme temperatures, pressures, and corrosive conditions. These environments require high mechanical strength and long service life, making forged products a preferred choice for critical infrastructure and continuous production operations.
Beyond traditional energy applications, chemical processing plants and power generation facilities are expanding adoption. Chemical manufacturers rely on corrosion-resistant forged components to maintain operational safety and equipment reliability, while power producers use them in turbines, piping systems, and high-pressure equipment where durability directly affects plant performance and maintenance costs.
Emerging opportunities are developing in offshore wind installations, hydrogen production facilities, and advanced energy infrastructure projects. These applications require specialized forged components capable of withstanding demanding operating conditions for extended periods. As governments across Asia Pacific accelerate investment in energy transition projects, these newer use cases are expected to create additional avenues for long-term market expansion.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 17.2 Billion |
|
Market size value in 2026 |
USD 18.1 Billion |
|
Revenue forecast in 2033 |
USD 28.4 Billion |
|
Growth rate |
CAGR of 6.65% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Asia Pacific |
|
Key company profiled |
Scot Forge, Bharat Forge, Ellwood Group, Nippon Steel, Sumitomo Metal, Sakamoto Tekko, Synergy Forgings, KOBELCO, Thyssenkrupp, ATI, Finkl Steel, Ramkrishna Forgings, CFS Forge, Kalyani Forge, Pacific Forge |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (Open Die Forgings, Closed Die Forgings, Rolled Rings, Shafts, Discs, Flanges, Others); By Grade (Austenitic, Ferritic, Martensitic, Duplex, Others); By Application (Oil & Gas, Aerospace, Automotive, Power Generation, Marine, Others); By End User (Industrial Manufacturers, OEMs, Energy Sector, Others) |
Which Regions are Driving the Asia Pacific Stainless Steel Forgings Market Growth?
East Asia holds the largest share of the market, supported by strong industrial manufacturing capabilities and extensive downstream demand from energy, chemical processing, and heavy engineering sectors. China, Japan, and South Korea maintain large forging capacities, advanced metallurgical expertise, and integrated supply chains that support high-volume production. Government-backed industrial development programs and ongoing investment in strategic manufacturing industries continue to reinforce regional leadership. A mature ecosystem of raw material suppliers, forging companies, machining providers, and industrial end users sustains this dominant position and supports consistent market activity.
South Asia ranks as the second-largest regional contributor, but growth dynamics differ from those in East Asia. Rather than relying on a deeply established manufacturing base, the region benefits from steady infrastructure development, refinery expansion, and long-term industrial investment. India remains the primary driver, supported by domestic manufacturing initiatives and increasing capital expenditure across energy and process industries. Stable economic growth and a growing focus on local production make the region a dependable source of market revenue.
Southeast Asia is emerging as the fastest-growing region due to accelerating industrialization and rising investment in manufacturing and energy infrastructure. Several countries have expanded industrial parks, attracted foreign direct investment, and strengthened local production capabilities over the past few years. Growth in petrochemical projects, power generation facilities, and export-oriented manufacturing has created new opportunities for forged component suppliers. Between 2026 and 2033, this momentum is expected to attract additional investment, encourage capacity expansion, and create favorable conditions for new market entrants seeking long-term growth opportunities.
Who are the Key Players in the Asia Pacific Stainless Steel Forgings Market and How Do They Compete?
Competition in the Asia Pacific stainless steel forgings industry remains moderately fragmented, with a mix of large integrated manufacturers and specialized forging companies serving different end-use sectors. Market participants compete primarily on metallurgical expertise, product quality, certification standards, production capacity, and the ability to deliver customized components for demanding industrial applications. Established manufacturers continue to defend market share through long-term customer relationships and technical capabilities, while regional entrants seek opportunities in fast-growing industrial and energy projects. Buyers increasingly evaluate suppliers based on reliability, traceability, and lifecycle performance rather than purchase price alone.
Bharat Forge focuses on scale, manufacturing efficiency, and engineering capabilities that support large industrial and energy-sector contracts. Extensive production capacity and a strong presence in India provide advantages in serving infrastructure and industrial expansion projects. Scot Forge differentiates itself through custom-engineered forgings and the ability to produce complex, high-performance components for critical applications where material integrity is essential. Continued investment in advanced manufacturing technologies strengthens quality consistency and operational efficiency.
Nippon Steel competes through advanced metallurgical research and premium-grade materials designed for demanding operating environments. Strong relationships with industrial and engineering customers in East Asia support steady demand for specialized forged products. thyssenkrupp emphasizes high-value engineered solutions and technical expertise, particularly for energy and process-industry applications. Expansion through technology upgrades, customer-specific product development, and broader participation in industrial modernization projects helps these companies strengthen competitive positioning across the region.
Company List
- Scot Forge
- Bharat Forge
- Ellwood Group
- Nippon Steel
- Sumitomo Metal
- Sakamoto Tekko
- Synergy Forgings
- KOBELCO
- Thyssenkrupp
- ATI (Allegheny Technologies Incorporated)
- Finkl Steel
- Ramkrishna Forgings
- CFS Forge
- Kalyani Forge
- Pacific Forge
Recent Development News
"In April 2026, Bharat Forge approved the restructuring of the steel forging operations of its German subsidiary and authorized financing of up to EUR 30 million to support the initiative. The move is intended to improve operational efficiency and address cost pressures in European forging operations, reflecting ongoing portfolio optimization within the forging sector.https://m.economictimes.com
"In April 2026, Nippon Steel obtained SuMPO Environmental Product Declaration (EPD) certifications for its stainless hot extruded steel shapes. The certification strengthens the company's sustainability credentials and supports growing customer requirements for verified environmental performance in industrial and infrastructure supply chains.https://www.nipponsteel.com
"In April 2025, Nippon Steel entered a collaboration with TIER IV to automate heavy-duty transporters at its Nagoya Plant. The partnership advances industrial automation and digital manufacturing capabilities, supporting productivity improvements across steel and forging-related production operations.https://www.nipponsteel.com
What Strategic Insights Define the Future of the Asia Pacific Stainless Steel Forgings Market?
Over the next five to seven years, the market is likely to move toward higher-value, application-specific forging solutions rather than volume-driven growth. Industrial buyers are placing greater emphasis on lifecycle performance, reliability, and compliance with increasingly demanding operating standards. This shift will favor manufacturers capable of producing advanced stainless steel forgings for energy infrastructure, chemical processing, and next-generation industrial systems. As a result, technical capabilities and material expertise will become more important competitive factors than production scale alone.
A less visible risk lies in the concentration of critical alloy supply chains. Dependence on nickel and chromium sources in a limited number of regions could expose manufacturers to sudden cost volatility, procurement disruptions, and margin pressure even during periods of strong end-market demand. Headline growth figures may therefore mask increasing vulnerability within upstream supply networks.
One emerging opportunity is the development of forgings for hydrogen production, storage, and transport infrastructure, particularly in India and Southeast Asia. Market participants should prioritize investments in advanced metallurgy, regional supply partnerships, and certification capabilities to secure early positions in these specialized, high-growth applications before competition intensifies.
Asia Pacific Stainless Steel Forgings Market Report Segmentation
By Product Type
- Open Die Forgings
- Closed Die Forgings
- Rolled Rings
- Shafts
- Discs
- Flanges
- Others
By Grade
- Austenitic
- Ferritic
- Martensitic
- Duplex
- Others
By Application
- Oil & Gas
- Aerospace
- Automotive
- Power Generation
- Marine
- Others
By End User
- Industrial Manufacturers
- OEMs (Original Equipment Manufacturers)
- Energy Sector
- Others
Frequently Asked Questions
Find quick answers to common questions.
The Expected Asia Pacific Stainless Steel Forgings Market size for the Market will be USD 28.4 Billion in 2033.
Key Segments for the Asia Pacific Stainless Steel Forgings Market are By Product Type (Open Die Forgings, Closed Die Forgings, Rolled Rings, Shafts, Discs, Flanges, Others); By Grade (Austenitic, Ferritic, Martensitic, Duplex, Others); By Application (Oil & Gas, Aerospace, Automotive, Power Generation, Marine, Others); By End User (Industrial Manufacturers, OEMs, Energy Sector, Others).
Major Asia Pacific Stainless Steel Forgings Market Players are Scot Forge, Bharat Forge, Ellwood Group, Nippon Steel, Sumitomo Metal, Sakamoto Tekko, Synergy Forgings, KOBELCO, Thyssenkrupp, ATI, Finkl Steel, Ramkrishna Forgings, CFS Forge, Kalyani Forge, Pacific Forge.
The Current Asia Pacific Stainless Steel Forgings Market size is USD 17.2 Billion in 2025.
The Asia Pacific Stainless Steel Forgings Market CAGR is 6.65% from 2026 to 2033.
- Scot Forge
- Bharat Forge
- Ellwood Group
- Nippon Steel
- Sumitomo Metal
- Sakamoto Tekko
- Synergy Forgings
- KOBELCO
- Thyssenkrupp
- ATI (Allegheny Technologies Incorporated)
- Finkl Steel
- Ramkrishna Forgings
- CFS Forge
- Kalyani Forge
- Pacific Forge
About the Authors

Kartik bhong
I am Kartik Bhong, a Senior Research Analyst at Transpire Insight, specializing in the Packaging, Manufacturing, and Construction industry. My work focuses on analyzing market trends, emerging technologies, industry regulations, and competitive landscapes to deliver accurate, data-driven insights. I am passionate about transforming complex industry information into clear, practical content that helps businesses, professionals, and decision-makers stay informed and make confident strategic decisions. Through continuous research and a strong commitment to accuracy, I strive to create reliable, well-researched content that reflects the latest developments across these dynamic industries and supports the vision of Transpire Insight in delivering valuable market intelligence.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Handling and Lifting Equipment Market
Handling and Lifting Equipment Market Size, Share & Analysis Report By Product (Cranes and Hoists, Forklifts, Conveyor Systems, Aerial Work Platforms, Others), By Application (E-Commerce, Automotive and Railway, Food and Beverages, Aviation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
HVAC Equipment Market
HVAC Equipment Market Size, Share & Analysis Report By Heating Equipment Type (Boilers and Furnaces, Heat Pumps, and Unitary Heaters), By Ventilation Equipment (Air Handling Units, Humidifiers and Dehumidifiers, Air Filters, and Fan Coiling Units), By Air Conditioning Equipment (Unitary Air Conditioners, Room Air Conditioners, Packaged Terminal Air Conditioners, and Chillers), By End User (Commercial, Residential, Industrial, and others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Refrigeration Valves Market
Refrigeration Valves Market Size, Share & Analysis Report By Type (Solenoid Valves, Expansion Valves, Check Valves, Service Valves, Others), By Application (Commercial Refrigeration, Industrial Refrigeration, Transport Refrigeration, Residential Refrigeration, Air Conditioning Systems), By End User (Food and Beverage Industry, Pharmaceutical Industry, HVAC Industry, Chemical Industry, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
E-Commerce Packaging Materials Market
E-Commerce Packaging Materials Market By Material Type (Corrugated Boxes, Paper & Paperboard, Foam & Cushioning Materials, Plastic Packaging, Flexible Packaging, Protective Packaging, Others), By Product(Primary Packaging, Secondary Packaging, Tertiary Packaging), By Packaging Function (Protective Packaging, Branding & Presentation Packaging, Transit & Logistic Packaging, Sustainable Packaging, Tamper Evidence Packaging), By End-User (Retail & Consumer Goods, Electronic Appliances, Food & Beverages, Healthcare & Pharmaceutical, Fashion & Apparel, Home & Furnishing, Others); By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033