
Sep 28, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the pharmaceutical warehousing market size is projected to grow from USD 62.13 billion in 2026 to USD 94.39 billion by 2035, at a CAGR of 6.28% during the forecast period 2027-2035. Pharmaceutical warehousing growth is driven by the increasing demand for temperature-sensitive biologics, compliance with Good Distribution Practice regulations, a surge in cell therapy development, and a need for sophisticated cold-chain automation.
Introduction
Healthcare supply chains are undergoing a paradigm shift, with the pharmaceutical warehousing market changing as a result of the need to manage complex biopharmaceuticals, vaccines, and cell therapies that demand a very specific temperature range. The modern facilities combine automated storage systems, real-time monitoring through IoT, and specific environmental management to avoid any product degradation. Specialized warehousing is essential for ensuring the safety, efficacy, and smooth delivery of medication products from manufacturing facilities to healthcare providers around the globe, propelled by the need for regulatory compliance and international distribution networks.
Recent Development News
May 2026: Some of the top cold chain logistics firms announced multi-million-dollar investments in implementing automated guided vehicles (AGVs) that utilize AI.
August 2026: As Asia-Pacific regions saw a surge in personalized bio-warehousing requirements for gene therapies, major logistics players opened ultra-low-temperature warehouses in the region.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Pharmaceutical Warehousing Market Size & Statistics
The Market Size for Pharmaceutical Warehousing Was Estimated to be Worth USD 62.13 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 6.28% between 2026 and 2035.
The Pharmaceutical Warehousing Market Size is anticipated to reach USD 94.39 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 43% of the pharmaceutical warehousing market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 9.4% in the pharmaceutical warehousing market.
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance in pharmaceutical warehousing is anchored by a mature cold-chain network, stringent FDA current Good Manufacturing Practice enforcement, and rapid reshoring of vaccine and antibody production onto domestic soil. Automated, temperature-controlled distribution centers by major distributors like McKesson, Cardinal Health, and AmerisourceBergen are continuing to grow to meet an increasing number of specialty pharmacies and integrated health care providers. DHL's purchase of US-based pharma logistics specialist SDS Rx is a good example of how entities are merging last-mile delivery expertise to tackle increasing demand for biologics and specialty drugs in the region.
Asia-Pacific's rapid ascent is fueled by expanding pharmaceutical manufacturing in China and India, growing contract development and manufacturing activity, and rising government support for GDP-compliant storage infrastructure. The purchase of Keppel Logistics brought a significant multi-temperature warehouse space to GEODIS's footprint in the region, demonstrating how operators are seeking opportunities to create a cold chain footprint in the vicinity of new production centres. The push towards specialized pharmaceutical storage solutions in Southeast Asia and beyond is further gaining momentum with the adoption of ‘GDP-compliant ' warehousing equipment and the overall evolution of the warehousing industry towards the use of IoT for traceability.
Top 15 Trends in the Pharmaceutical Warehousing Market
Cold chain and temperature-controlled storage expansion
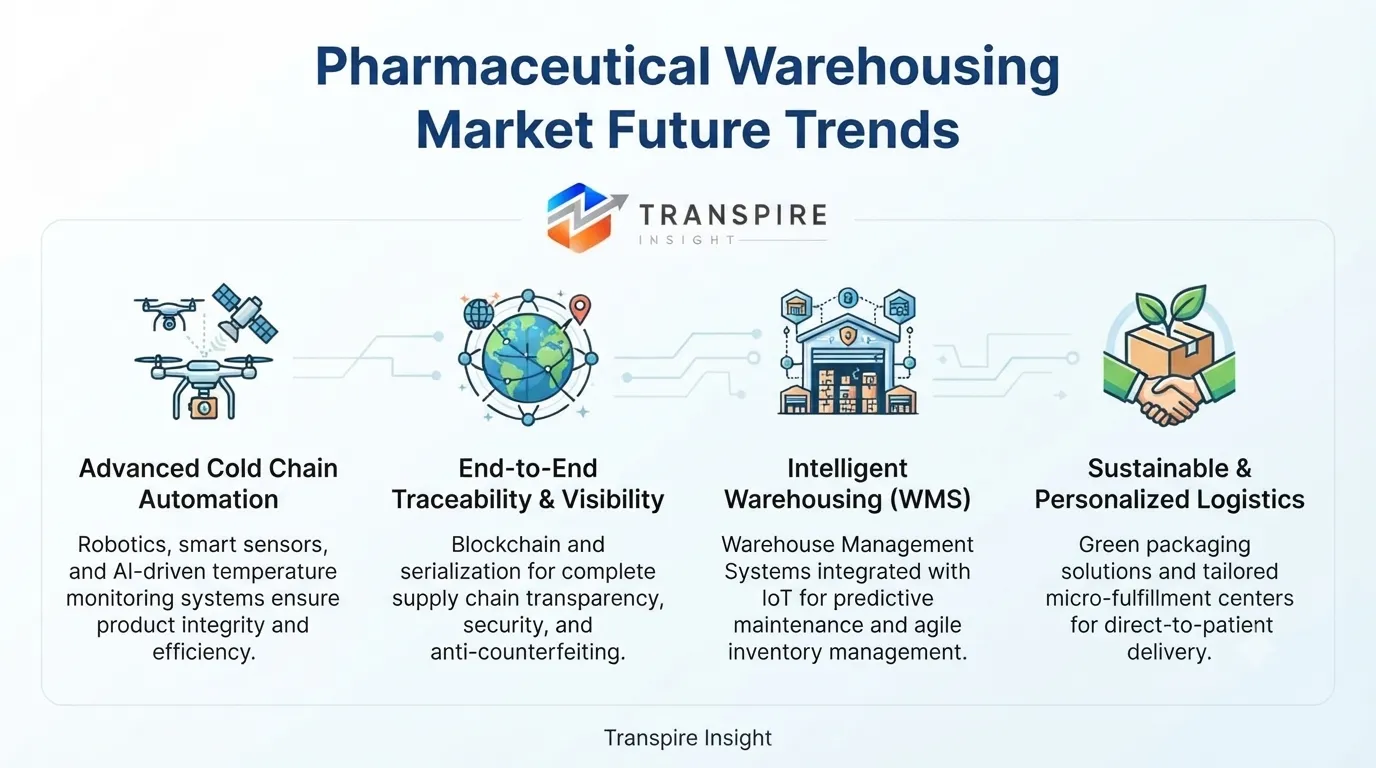
Rising biologics, vaccines, and specialty drugs demand strict thermal control, pushing warehouse operators to build multi-temperature zones with refrigerated and frozen capacity across major distribution hubs.
Automation and robotics in pharma warehouses
Labor shortages and rising throughput needs are pushing distributors toward robotic picking, automated storage systems, and AI-guided sorting to boost accuracy while cutting operational costs.
Rise of biologics and specialty drug storage
Biologics, cell and gene therapies, and specialty medications require ultra-low temperature, humidity-controlled environments, prompting warehouses to invest heavily in specialized racking, monitoring, and storage protocols.
Outsourcing to specialized third-party logistics providers
Manufacturers increasingly outsource storage and distribution to specialized 3PL partners, avoiding costly in-house infrastructure while gaining regulatory expertise, scalability, and access to established cold-chain networks.
Vaccine and cell/gene therapy storage infrastructure growth
Post-pandemic vaccine reshoring and expanding cell and gene therapy pipelines are driving construction of specialized ultra-cold storage facilities near manufacturing hubs to shorten distribution timelines.
Mergers and acquisitions among pharma logistics players
Major logistics providers are acquiring specialized pharma warehousing firms to expand cold-chain capacity, geographic reach, and last-mile delivery capabilities, consolidating a fragmented distribution market.
List of Top 25 Companies Leading the Pharmaceutical Warehousing Market
McKesson Corporation
Operates one of North America's largest and most technologically advanced distribution networks.
Founded: 1833 | HQ: Irving, Texas, USA.
Why It Ranks: Market dominance in North American pharmaceutical wholesale and specialized bio-storage distribution.
Regional Dominance: Strongest footprint across North America with extensive regional distribution center coverage.
Product Line: Bulk pharma storage, ambient warehousing, cold-chain handling, and automated fulfillment.
AmerisourceBergen (Cencora)
leader specializing in complex specialty pharmaceutical warehousing and distribution services.
Founded: 2001 | HQ: Conshohocken, Pennsylvania, USA.
Why It Ranks: Unmatched specialty logistics expertise and extensive cold-chain storage infrastructure.
Regional Dominance: Dominant presence across North America and growing operational scale in Europe.
Product Line: Cold-chain warehousing, specialty drug storage, clinical trial logistics, distribution services.
Cardinal Health
Key player offering integrated supply chain and specialized medical product storage solutions.
Founded: 1971 | HQ: Dublin, Ohio, USA.
Why It Ranks: Critical supply partner for hospital systems with massive automated warehouse capacity.
Regional Dominance: Major presence in North America with key strategic logistics hubs.
Product Line: Medical device warehousing, temperature-controlled drug storage, vault storage for controlled substances.
DHL Supply Chain (Deutsche Post DHL)
World’s premier contract logistics provider with dedicated Life Sciences and Healthcare facilities.
Founded: 1969 | HQ: Bonn, Germany.
Why It Ranks: leadership in end-to-end, GDP-compliant temperature-controlled pharmaceutical warehouse space.
Regional Dominance: Unmatched distribution footprint spanning Europe, the Americas, Asia, and the Middle East.
Product Line: Smart warehousing, cold-chain hubs, ambient storage, GDP-certified life science facilities.
Kuehne + Nagel International AG
Operates a vast, high-tech warehouse network certified under Pharma Chain protocols.
Founded: 1890 | HQ: Schindellegi, Switzerland.
Why It Ranks: Industry-leading technology integration and ultra-low temperature storage network for vaccines.
Regional Dominance: European market leader with rapidly expanding operations in North America and Asia.
Product Line: Air/sea pharma hubs, temperature-sensitive storage, GxP-compliant contract warehousing solutions.
UPS Healthcare
Delivers advanced healthcare logistics through dedicated, GDP-compliant, cold-chain-equipped facilities globally.
Founded: 1907 | HQ: Atlanta, Georgia, USA.
Why It Ranks: Rapidly expanding footprint dedicated exclusively to complex biopharmaceutical logistics.
Regional Dominance: Strong market position in North America, Europe, and key Latin American hubs.
Product Line: Ultra-freezer storage, cryogenic warehousing, cold-chain fulfillment, temperature-controlled distribution.
FedEx Supply Chain
Provides specialized life science logistics, deep frozen storage, and rapid delivery networks.
Founded: 1973 | HQ: Memphis, Tennessee, USA.
Why It Ranks: Seamless integration between high-speed express networks and specialized temperature-monitored hubs.
Regional Dominance: reach with heavy operational saturation across North America and Europe.
Product Line: Temperature-controlled warehousing, cold-chain storage, clinical trial material distribution services.
DB Schenker
Leading European logistics provider expanding state-of-the-art cold-chain healthcare hubs globally.
Founded: 1872 | HQ: Essen, Germany.
Why It Ranks: Exceptional European infrastructure and dedicated life-science logistics center capabilities.
Regional Dominance: Deeply rooted leadership across Europe with strong cross-border Asian logistics corridors.
Product Line: GDP-compliant warehousing, ambient storage, refrigerated facilities, customized healthcare supply solutions.
SF Express (SF Holding)
Asia's premier logistics giant aggressively expanding automated pharmaceutical cold-chain warehouse facilities.
Founded: 1993 | HQ: Shenzhen, China.
Why It Ranks: Massive domestic network dominance in China’s rapidly growing domestic pharmaceutical landscape.
Regional Dominance: Undisputed market leader across East Asia with growing Southeast Asian corridors.
Product Line: Pharmaceutical cold-storage, automated bio-warehousing, temperature-monitored local fulfillment centers.
DSV A/S
transport and logistics powerhouse providing scalable life science warehousing solutions worldwide.
Founded: 1976 | HQ: Hedehusene, Denmark.
Why It Ranks: Massive operational scale following strategic acquisitions, providing versatile multi-temperature sites.
Regional Dominance: Powerful operational footprint across Europe, North America, and Middle Eastern markets.
Product Line: Life science warehousing, dangerous goods storage, GDP cold-chain, inventory management.
Conclusion
The pharmaceutical warehousing industry continues to be a key component of the healthcare industry worldwide. Warehouse operators are constantly improving their capacity in today's fast-evolving temperature-sensitive biologics landscape, strict international compliance requirements, and digital automation. In the future, strategic investment in regions and cutting-edge IoT cold chain integration will be the key to market leadership, enabling life-saving therapies to be safely stored and quickly delivered to meet the growing healthcare needs.


Send us a brief description of your challenge and we'll get back to you within 24 hours.
 [email protected]
 APAC:+91 7666513636
 Address


