
Middle East and Africa Clean Technology Market Size & Forecast:
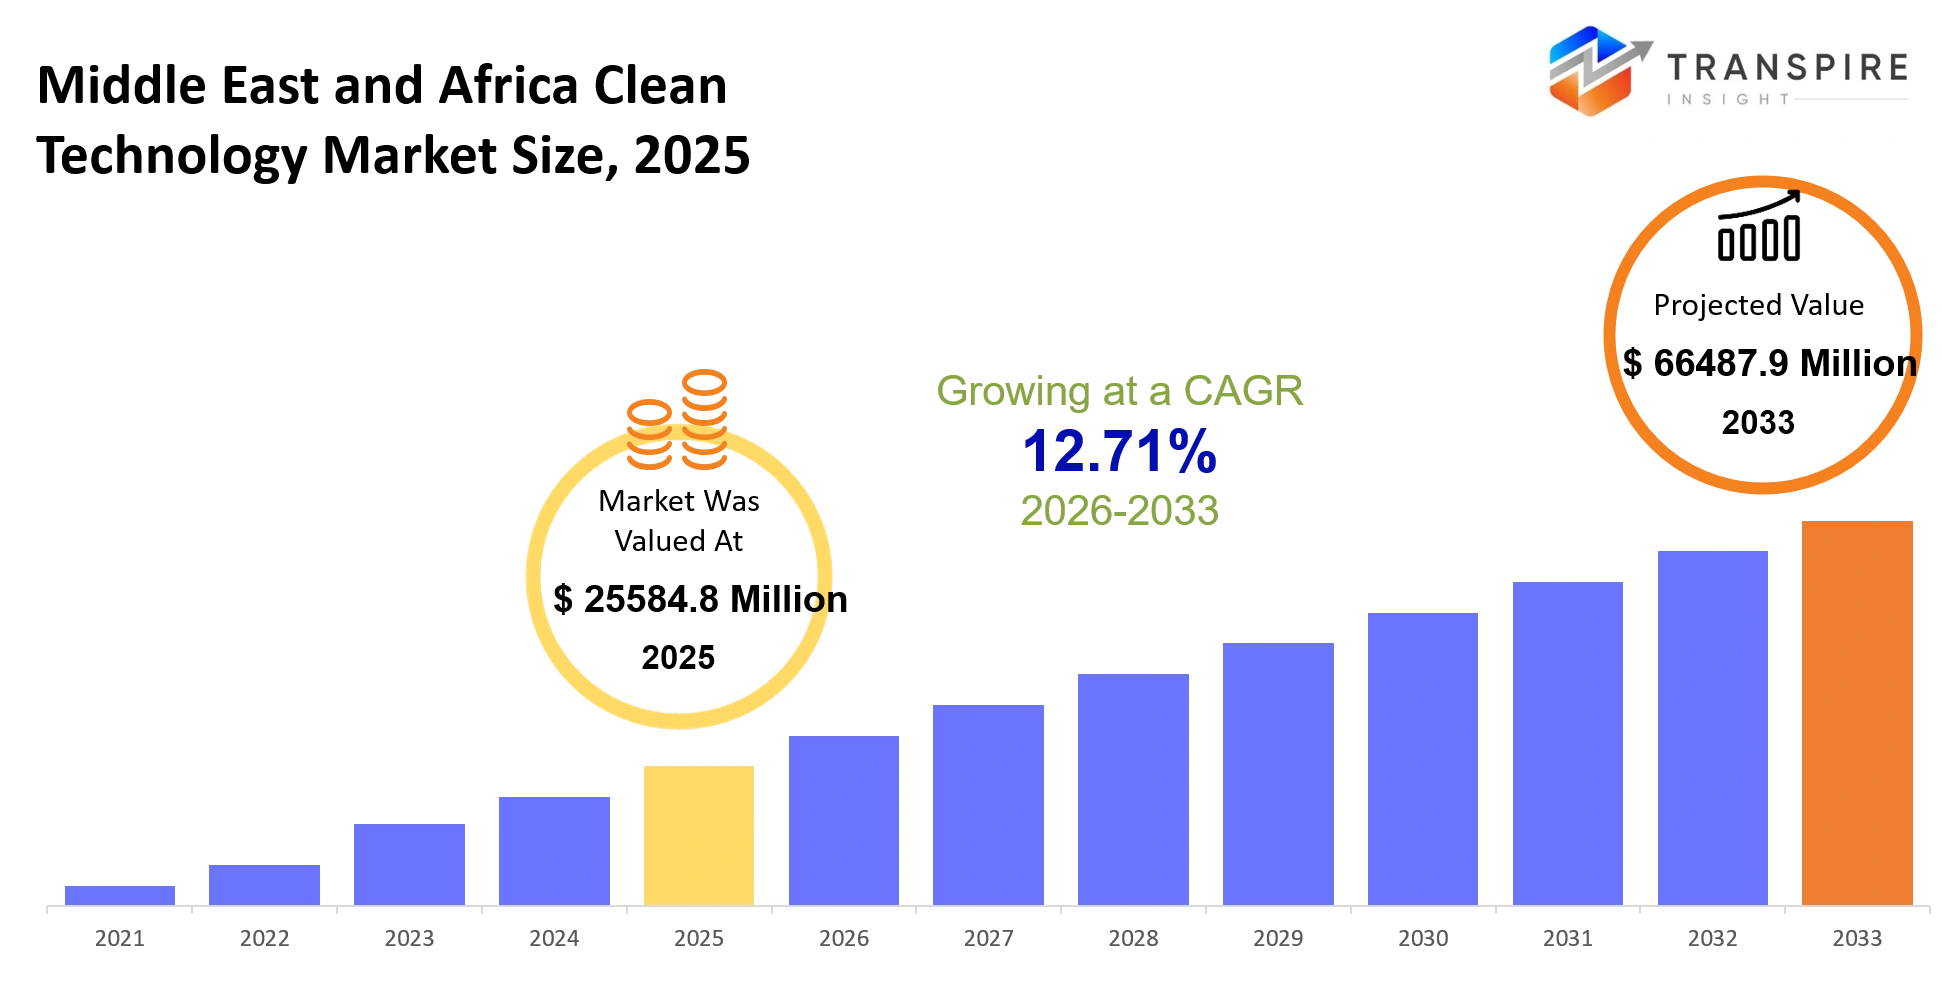
- Middle East and Africa Clean Technology Market Size 2025: USD 25584.8 Million
- Middle East and Africa Clean Technology Market Size 2033: USD 66487.9 Million
- Middle East and Africa Clean Technology Market CAGR: 12.71%
- Middle East and Africa Clean Technology Market Segments: By Technology (Renewable Energy, Energy Storage, Water Treatment, Waste Management, Green Building, Others); By Application (Power Generation, Industrial, Residential, Commercial, Others); By End User (Utilities, Industries, Government, Others); By Deployment (On-grid, Off-grid, Hybrid, Others)
To learn more about this report,  Download Free Sample Report
Middle East and Africa Clean Technology Market Summary
The Middle East and Africa Clean Technology Market was valued at USD 25584.8 Million in 2025. It is forecast to reach USD 66487.9 Million by 2033. That is a CAGR of 12.71% over the period.
Clean technology in the Middle East and Africa is really about lowering emissions coming out of power generation, water systems, waste handling, plus industrial activity that still leans heavily on fossil fuels and sort of laggy infrastructure. In real life, it helps utilities, cities, and industrial operators move toward renewable integration, more efficient water purification systems, and low-emission energy networks, all while still having to satisfy those tightening environmental compliance rules, which can be well, kind of strict
Over the past 3–5 years there’s been a big structural change where the region has drifted away from small pilot-style renewable projects into utility-scale solar, desalination-linked energy optimization, and broader grid modernization initiatives. One of the main reasons this happened is stricter national decarbonization roadmaps, most noticeably in Gulf countries. That was paired with volatility in global energy supply chains, and it kinda pushed governments to localize cleaner energy production too. So, basically capital is now flowing more toward scalable solar projects, energy storage, and smart grid systems, which is speeding up deployment across public utilities and also private industrial users who want steadier operating expenses and also measurable emissions reduction.
Key Market Insights
- The Middle East and Africa Clean Technology Market pulled in USD 25,584.8 Million in 2025, sort of pushed by utility-scale solar build outs in GCC countries, and yeah that momentum matters.
- By 2033 the forecast lands at USD 66,487.9 Million, this points to stronger infrastructure modernization, plus more decarbonization investments coming in steadily.
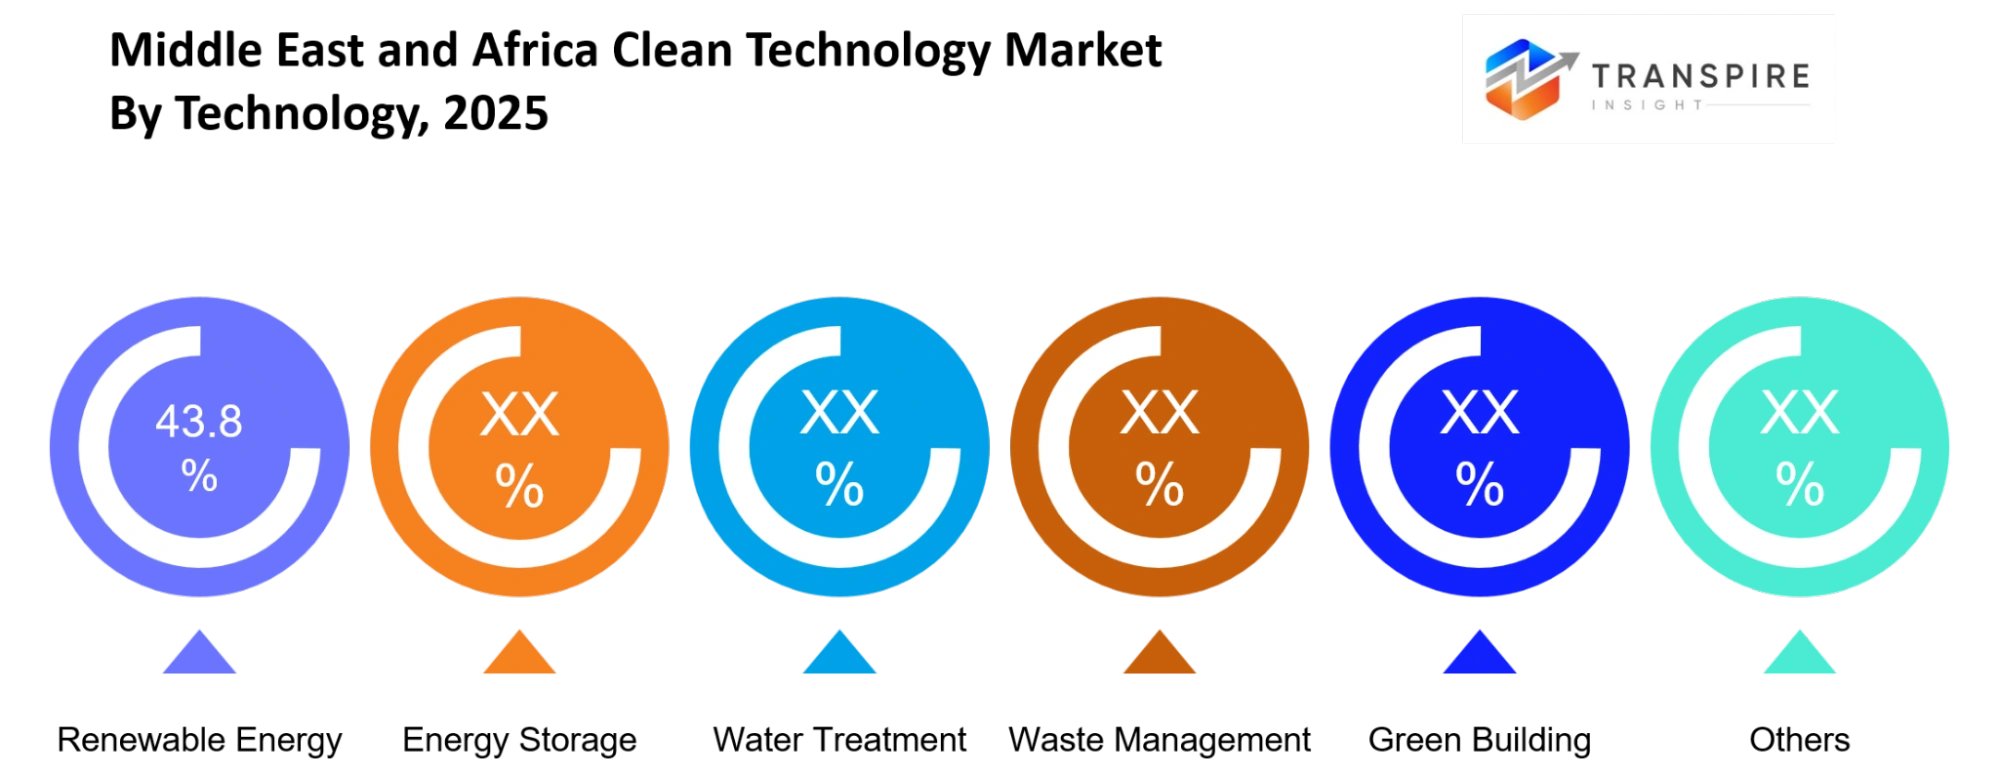
- Renewable energy is still the main player with a dominant slice over 35% in 2025, and it’s backed by solar megaprojects across Saudi Arabia and UAE.
- Energy storage is showing up as the fastest-growing segment all the way through 2033 because grid balancing becomes critical in areas with heavy solar penetration, basically when the grid needs calm balancing.
- Industrial uses take nearly 40% share, mostly shaped by oil & gas emissions reduction, and refinery efficiency upgrades that keep operations optimized.
- For end users, utilities stay at the front, supported by state backed clean energy procurement initiatives, which help keep demand visible.
- On-grid deployment dominates because centralized power infrastructure keeps expanding across North Africa and the GCC states.
- Meanwhile off-grid systems are growing quickly in Sub-Saharan Africa due to electrification gaps and a rising rural energy demand that can’t be ignored.
- Companies like Siemens Energy, Schneider Electric, and ABB are pushing digital grid plus automation innovation, giving the network a more responsive feel.
- Strategic expansion into water treatment along with green hydrogen ecosystems helps lock in long-term market competitiveness, and it strengthens the overall positioning.
What are the Key Drivers, Restraints, and Opportunities in the Middle East and Africa Clean Technology Market?
Large-scale government decarbonization programs kinda act as the main growth driver in the Middle East and Africa Clean Technology Market. National strategies like the UAE Net Zero 2050 and Saudi Vision 2030 have already triggered structured investment in solar parks, smart grids,and industrial emission control systems. That kind of policy push then basically turns into procurement pipelines for utilities, plus EPC contractors. So clean technology providers get more revenue visibility. Also, the growing integration of renewable energy into desalination plants and oil-linked industrial operations , makes adoption even more likely across these capital-heavy sectors.
The big issue is high upfront capital requirements, they still stay a sort of structural barrier that limits faster adoption. Deploying clean tech , especially energy storage, grid modernization,and advanced water treatment systems often means longer payback periods. On top of that, many African economies have constrained fiscal space, so large scale infrastructure rollouts slow down. In practice this can lead to delayed procurement cycles, and a stronger dependence on international financing institutions. That, in turn, can reduce project velocity and suppress
Green hydrogen, and even hybrid renewable desalination systems , look like a major emerging opportunity. Gulf countries are building integrated hydrogen export hubs that connect to solar and wind generation, especially around Saudi Arabia’s NEOM ecosystem. Those initiatives create fresh demand for electrolyzers, storage systems,and digital energy management platforms. And as export-oriented clean fuels start getting more policy support, technology providers may gain access to long-term contracts and more vertically integrated infrastructure ecosystems across the region.
What Has the Impact of Artificial Intelligence Been on the Middle East and Africa Clean Technology Market?
Artificial intelligence is sort of reshaping operational efficiency across the Middle East and Africa clean technology market, by tuning energy systems, emissions tracking and basically infrastructure performance. In grid operations, AI-led control systems help smooth out the swingy solar and wind contributions , which supports stability in high-renewable pockets like the UAE and Saudi Arabia. For water treatment plus industrial plants, machine learning models can automate those operational tweaks, so chemical usage drops and output stays more consistent.
Predictive maintenance is now being used on turbines , inverters , and even desalination units. The setup reads sensor streams and projects likely failures, which cuts down on unplanned downtime and also stretches the useful life of assets. Operators often mention real-world improvements in operational efficiency, such as better uptime and less fuel or energy waste in hybrid power plants.
Still, AI adoption has limits because data quality is sometimes inconsistent and connectivity is not always reliable, especially in remote offshore or desert sites. Also, when older infrastructure doesn’t offer strong, real-time sensor integration, the model tends to be less accurate. Then there’s the integration spend for legacy industrial systems, which can be high which delays rollouts , particularly in some African utility networks where modernization timelines stay uneven.
Key Market Trends
- Utility-scale solar projects sort of expanded more than 30% from 2022–2025 across the UAE and Saudi Arabia, kind of reshaping the way people talk about generation portfolios.
- Energy storage adoption actually picked up speed during 2024–2025, mainly to help stabilize grids that now have high intermittent renewable penetration, which is a mouthful but yeah.
- Water-energy integration systems also moved up in GCC desalination plants, to cut down the energy intensity and lower operational costs a bit.
- Digital grid adoption rose sharply too, as utilities rolled out smart meters and AI-based load forecasting systems, it felt like everything was connected all at once .
- Meanwhile industrial decarbonization contracts expanded across oil & gas refineries, mostly as they pursue emissions compliance upgrades and related improvements.
- Off-grid solar deployment surged in Sub-Saharan Africa, driven by rural electrification gaps and mini-grid expansion that just keeps growing.
- Hydrogen pilot projects scaled in 2025, especially in Saudi Arabia’s industrial corridors, where demand seems steadier.
- Competitive intensity increased as global players—Hitachi Energy and GE Vernova for example—expanded grid solutions, offering more choices.
- Also, regulatory tightening on emissions pushed faster adoption of clean fuel transition technologies.
- Finally, public-private partnerships increased infrastructure financing for renewable megaprojects across the region, even when timelines got a little messy sometimes.
Middle East and Africa Clean Technology Market Segmentation
By Technology
In the Middle East and Africa Clean Technology Market, by Technology, there will be noticeable alignment toward renewable energy systems, energy storage solutions , water treatment technologies, waste management systems, green building solutions and other kind of hybrid sustainability technologies, you know. Renewable energy is expected to lead this space because of the huge solar installations across GCC countries, plus the North African wind corridors that keep showing strong potential.
Energy storage will likely grow as grid balancing becomes more important, and also because of the intermittent nature of renewables, which is kinda a persistent headache. Water treatment will stay very critical, since desalination demand is still high in arid economies. Waste management solutions should also keep moving up in urban centers, where industrial and municipal waste volumes are rising , steadily, almost year after year.
Green building technologies will pick up momentum through smart city projects, like NEOM and Masdar City. Then the other related techs will cover carbon capture systems, and some emerging hydrogen-linked solutions that aim to support long-term decarbonization goals, even when timelines feel a bit stretched.
To learn more about this report, Download Free Sample Report
By Application
In the Middle East and Africa, the Clean Technology Market by Application, kind of like, will cover power generation, industrial operations, residential use, commercial facilities, and a few extra supporting use cases. For power generation it should stay the top choice because massive renewable integration is still happening into national grids. Then the industrial side is expected to widen especially with emissions reduction systems in oil & gas, petrochemicals, and heavy manufacturing, kind of where compliance really matters.
Residential adoption should also pick up in more urban housing developments, using rooftop solar plus smart energy systems, because people want reliability and tighter control. For commercial spaces the uptake will climb in malls, offices and hospitality venues, with an emphasis on energy efficiency, and direct cost reduction. The remaining applications will lean on transport-linked electrification and municipal infrastructure upgrades, which back up broader sustainability mandates, in a more practical way
By End User
Middle East and Africa Clean Technology Market by End User will be made up of utilities , industries , government entities and other institutional users. Utilities will dominate, partly because there is centralized control over power generation and the whole distribution systems, so renewable adoption sort of moves faster. Industries will show solid pull from energy intensive sectors, they want to meet emission reduction frameworks , and that compliance pressure matters.
Government bodies will also play a big part via funding, policy enforcement and infrastructure development programs . The “other” group is usually a mix of private developers and independent power producers , they step in through renewable energy auctions and decentralized energy systems participation.
By Deployment
Middle East and Africa Clean Technology Market by deployment covers on-grid, off-grid, hybrid, and a few other setups that people often group together. The on grid options should lead, mainly because there’s already solid transmission infrastructure across GCC and the North Africa regions. Off grid systems will likely grow fast across rural Africa, especially where electrification gaps still persist, and where access is still kind of uneven.
Hybrid arrangements will pick up steam too, since they blend solar, wind, plus storage, so service stays steadier and overall costs can look better. For the other deployment models, think microgrids and distributed energy systems that are meant to support remote industrial use, as well as community needs in more isolated places.
What are the Key Use Cases Driving the Middle East and Africa Clean Technology Market?
Power generation still sits as the dominant use case, where clean techs back those big solar farms, wind parks, and connected grid systems that feed city and industrial demand. This tends to drive the highest demand, because national energy diversification programs keep pushing it along, in a sort of steady way.
Industrial applications are the second big bucket, especially across oil refineries , petrochemical facilities, and heavy manufacturing units that adopt emissions mitigation together with energy efficiency systems. In practice, utilities and industrial end users increasingly align day to day operations with carbon reduction targets, not just on paper.
Then there are the emerging scenarios, like hydrogen production ecosystems and smart desalination plants where renewable power is paired with water generation. These are getting more attention in Gulf infrastructure projects, and they are expected to scale as export oriented clean fuel markets keep expanding.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 25584.8 Million |
|
Market size value in 2026 |
USD 28783.2 Million |
|
Revenue forecast in 2033 |
USD 66487.9 Million |
|
Growth rate |
CAGR of 12.71% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Middle East and Africa (Saudi Arabia, United Arab Emirates, South Africa, Rest of Middle East and Africa) |
|
Key company profiled |
Siemens Energy, Schneider Electric, ABB, Tesla, First Solar, Vestas, Enel Green Power, Veolia, Suez, GE Vernova, Sungrow, BYD, Hitachi Energy, Honeywell, Johnson Controls |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Technology (Renewable Energy, Energy Storage, Water Treatment, Waste Management, Green Building, Others); By Application (Power Generation, Industrial, Residential, Commercial, Others); By End User (Utilities, Industries, Government, Others); By Deployment (On-grid, Off-grid, Hybrid, Others) |
Which Regions are Driving the Middle East and Africa Clean Technology Market Growth?
Gulf Cooperation Council (GCC) keeps on being the leading region, mainly because of solid policy structures , strong sovereign investment ability, and those mega renewable efforts like big solar parks and hydrogen corridors. You see advanced grid infrastructure, plus centralized utilities, which makes clean tech deployment faster and more coordinated. Also, the heavy involvement from state-owned enterprises kind of speeds up the project execution, while building long-term technical know-how too
North Africa counts as a steady contributor, driven by ongoing solar and wind rollouts in places like Egypt and Morocco. The economic ties with Europe help enable cross-border power exchange and renewable financing. In addition, the slow but clear regulatory alignment with worldwide climate frameworks keeps investment coming in at a steady pace, so the area acts like a trustworthy long-term growth base
Sub-Saharan Africa looks like the fastest-growing region, mostly due to the rise in off-grid solar uptake and the push for rural electrification . New infrastructure funding, along with mini-grid deployments, has improved energy access in a noticeable way. This momentum creates good entry chances for decentralized energy providers and microgrid technology developers during 2026–2033, yes through that whole window too
Who are the Key Players in the Middle East and Africa Clean Technology Market and How Do They Compete?
The Middle East and Africa Clean Technology Market is kind of moderately fragmented, with global tech providers going head to head with regional utilities , and EPC contractors too. For most of it, competition is pushed by things like technology efficiency, overall cost competitiveness , and how well companies can weave large scale renewable systems into the existing grid setup. More and more, firms seem to be leaning on digital energy management along with cross sector decarbonization solutions, not just standalone installs or the usual stuff.
Siemens Energy puts emphasis on high efficiency grid systems and turbines that are hydrogen-ready, and it differentiates by using integrated energy infrastructure capabilities. Schneider Electric is trying to strengthen its place with advanced automation, smart grid software , and energy management platforms, which help utilities see operations more clearly in practice. ABB leans on electrification and robotics know how to support grid stabilization as well as industrial electrification solutions, especially across bigger infrastructure projects.
GE Vernova is growing by leaning into gas-to-renewable transition technologies and hybrid energy systems, aiming at utility scale decarbonization efforts. Hitachi Energy differentiates with high voltage transmission systems and grid integration solutions that support cross border renewable energy flows. Collectively, these players are expanding through strategic partnerships with Gulf utilities, joint ventures in hydrogen development, and technology localization initiatives across African power networks, even when timelines feel tight .
Company List
- Siemens Energy
- Schneider Electric
- ABB
- Tesla
- First Solar
- Vestas
- Enel Green Power
- Veolia
- Suez
- GE Vernova
- Sungrow
- BYD
- Hitachi Energy
- Honeywell
- Johnson Controls
Recent Development News
In February 2026, INOX Clean Energy and RJ Corp Limited in conjunction with SkyPower launched a multi-gigawatt renewable energy platform focused on Africa. The partnership includes acquisition of SkyPower Services MENA and development of over 10 GW solar capacity, strengthening large-scale utility renewable deployment across emerging African power markets.http://www.uaebusinessdaily.com
In April 2026, TotalEnergies and Masdar launched a $2.2 billion renewable energy joint venture covering Asia and extended clean energy portfolios from Middle East-linked operations. The JV consolidates solar, wind, and battery storage assets, strengthening cross-border clean technology investment flows and scaling utility-grade renewable infrastructure.http://sis.gov.eg
In January 2026, ENGIE and Masdar achieved financial close on the 1.5 GW Khazna Solar Project in the UAE. The project advances one of the region’s largest utility-scale solar developments, reinforcing long-term renewable power supply contracts with Emirates Water and Electricity Company.http://engiemiddleeast.com
What Strategic Insights Define the Future of the Middle East and Africa Clean Technology Market?
The Middle East and Africa Clean Technology Market is kind of slowly moving toward integrated energy ecosystems, where renewable generation, hydrogen production, and digital grid management all sort of work as one unified infrastructure layer. This movement comes from sovereign decarbonization commitments and long-term energy export diversification strategies, especially in Gulf economies, and it’s not just a trend, it feels more structural now.
There’s also a hidden risk sitting there quietly, which is the supply chain concentration for key components like semiconductors, electrolyzers, and high-voltage grid equipment. That concentration can delay deployment schedules , even when demand looks strong and consistent. At the same time, there’s an emerging opportunity too: the expansion of cross-border renewable energy trading corridors, linking North Africa with Europe, which might reshape the regional energy economics in a pretty noticeable way.
So market players should lean into vertically integrated partnerships, combining generation, storage, and digital management in a single operational package. Companies that localize manufacturing and tighten up regional supply chains will likely get better resilience and steadier long-term contract terms across 2026–2033, even if conditions shift.
Middle East and Africa Clean Technology Market Report Segmentation
By Technology
- Renewable Energy
- Energy Storage
- Water Treatment
- Waste Management
- Green Building
- Others
By Application
- Power Generation
- Industrial
- Residential
- Commercial
- Others
By End User
- Utilities
- Industries
- Government
- Others
By Deployment
- On-grid
- Off-grid
- Hybrid
- Others
Frequently Asked Questions
Find quick answers to common questions.
The expected Middle East and Africa Clean Technology Market size for the market will be USD 66487.9 Million in 2033.
Key segments for the Middle East and Africa Clean Technology Market are By Technology (Renewable Energy, Energy Storage, Water Treatment, Waste Management, Green Building, Others); By Application (Power Generation, Industrial, Residential, Commercial, Others); By End User (Utilities, Industries, Government, Others); By Deployment (On-grid, Off-grid, Hybrid, Others)
Major Middle East and Africa Clean Technology Market players are Siemens Energy, Schneider Electric, ABB, Tesla, First Solar, Vestas, Enel Green Power, Veolia, Suez, GE Vernova, Sungrow, BYD, Hitachi Energy, Honeywell, Johnson Controls
The Middle East and Africa Clean Technology Market size is USD 25584.8 Million in 2025.
The Middle East and Africa Clean Technology Market CAGR is 12.71% from 2026 to 2033.
- Siemens Energy
- Schneider Electric
- ABB
- Tesla
- First Solar
- Vestas
- Enel Green Power
- Veolia
- Suez
- GE Vernova
- Sungrow
- BYD
- Hitachi Energy
- Honeywell
- Johnson Controls
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Active Power Filter Market
Active Power Filter Market Size, Share & Analysis Report By Type (Shunt Active Power Filters, Series Active Power Filter, Hybrid Active Power Filter), By Application (Harmonics Mitigation, Reactive Power Compensation, Voltage Regulation, Power Factor Correction), By Phase (Single Phase, Three Phase), By End-User Industry (Manufacturing, Healthcare, Commercial, Automotive, Oil and Gas, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Electrical Transformer Market
Electrical Transformer Market Size, Share & Analysis Report By Core (Closed, Shell, and Berry), By Insulation (Gas, Oil, Solid, Air, and Other), By Phase (Single, and Three), By Rating (100 MVA to 500 MVA, 501 MVA to 800 MVA, and 801 MVA to 1200 MVA), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Hydraulic Piston Pumps Market
Hydraulic Piston Pumps Market Size, Share & Analysis Report By Type (Axial Piston Pumps, Radial Piston Pumps), By Operating Pressure (Low Pressure, Medium Pressure, High Pressure), By Application (Construction, Mining, Agriculture, Automotive, Oil & Gas, Industrial Machinery, Others), By End-User (OEMs, Aftermarket), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Laboratory Gas Generators Market
Laboratory Gas Generators Market Size, Share & Analysis Report By Product (Nitrogen Gas Generator, Hydrogen Gas Generator, Zero Air Gas Generator, Purge Gas Generator, TOC Gas Generators, Others), By Application (Gas Chromatography, Liquid Chromatography-mass Spectrometry (LC-MS), Gas Analyzers, Others), By End-user (Life Science, Chemical & Petrochemical, Food & Beverage, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031