
Aug 13, 2026
Market Forecast
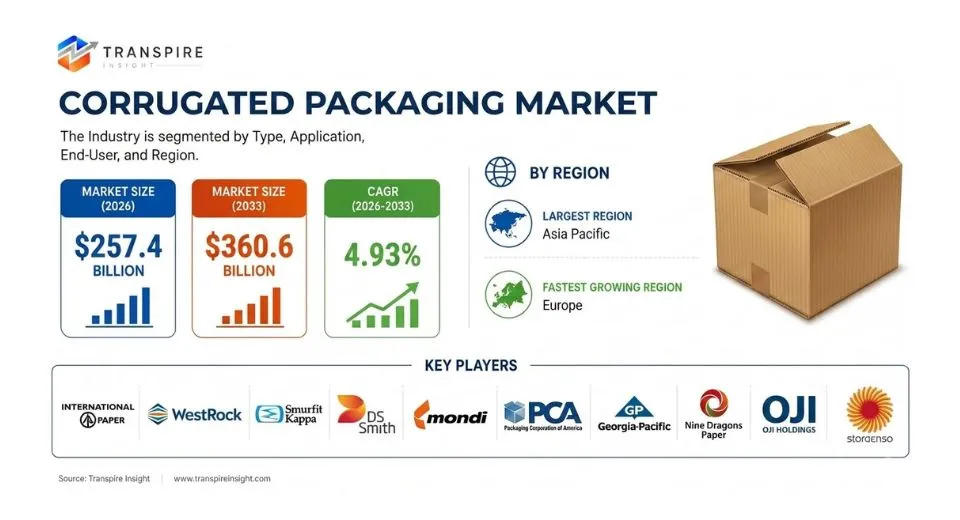
The corrugated packaging market was valued at USD 245.3 billion in 2025 and is projected to grow from USD 257.4 billion in 2026 to USD 360.6 billion by 2033, at a CAGR of 4.93% through the forecast period, according to a new report by Transpire Insights.
E-commerce growth, sustainability-driven material substitution away from plastics, and expanding food and beverage production in emerging markets are the central forces behind this trajectory. Corrugated packaging sits at the intersection of structural demand from trade and logistics and the accelerating consumer and regulatory push toward recyclable, paper-based packaging — a combination that gives the market durable long-term momentum.
Corrugated Packaging Market Growth & Trends
Online retail has structurally transformed the corrugated packaging demand landscape. Every parcel shipped through an e-commerce fulfillment network requires corrugated protection, and parcel volumes are still growing year on year across North America, Europe, and Asia Pacific. Major logistics operators and e-commerce platforms are simultaneously driving demand and pushing for lightweighting and material efficiency, which is creating pressure on box makers to develop higher-performing paper grades that deliver equivalent protective performance with less fibre.
Sustainability is reshaping procurement decisions at brand owner level. Large FMCG companies with plastic reduction commitments are converting secondary and tertiary packaging to corrugated board, adding demand beyond the traditional shipping box market. The high recyclability and well-established collection infrastructure for corrugated materials makes it the default choice when plastic alternatives are phased out, and regulatory packaging targets in the EU and UK are accelerating that substitution dynamic.
Emerging Economies & Technology
Asia Pacific dominates corrugated packaging production and consumption, with China alone accounting for a disproportionate share of world fibre processing capacity. India is the fastest-growing major domestic market within the region, driven by its rapidly expanding e-commerce sector, growing organised retail, and increasing adoption of corrugated distribution packaging by food and consumer goods manufacturers who are upgrading from traditional loose-fill and wooden crate logistics.
Digital printing technology is enabling shorter print runs, faster brand changeovers, and greater customisation on corrugated boards — capabilities that are particularly valued by e-commerce brands and consumer goods companies running large SKU portfolios across multiple markets. Automated box-on-demand systems that cut and crease corrugated board to exact parcel dimensions at the point of packing are reducing void fill requirements and cardboard waste in distribution environments, creating both a cost and sustainability argument that large fulfillment operators find compelling.
Single Wall Corrugated Segment
Single wall corrugated board holds 41% of the corrugated packaging market — the largest product segment. Its combination of adequate crush resistance, light weight, and cost-effective manufacture makes it the default specification for the vast majority of consumer goods shipping boxes, e-commerce mailers, and retail-ready packaging formats. Single wall board processes easily on high-speed converting lines, is well-suited to digital and flexographic printing, and meets the structural requirements of most domestic and international logistics applications without the cost premium of multi-wall constructions.
Innovation in single wall boards is concentrating on reducing basis weight while maintaining or improving compression and burst strength through advances in paper furnish composition and manufacturing process control. A lighter board that meets the same performance specification reduces fibre consumption, transport cost, and carbon footprint per unit — a combination that resonates strongly with sustainability-committed packaging buyers and helps paper mills and box makers meet their own environmental commitments.
Double Wall Corrugated: Fastest-Growing Segment
Double wall corrugated board is growing at a CAGR of 8.9% — the fastest rate across all product types. Its superior stacking strength, vibration resistance, and moisture performance relative to single wall make it the specification of choice for heavy industrial goods, large appliances, chemical drums, and automotive components — segments that are all expanding their use of corrugated packaging as alternatives to wooden crates and expanded polystyrene are phased out under sustainability pressure.
Growing export trade in manufactured goods — particularly electronics, machinery, and automotive parts shipped over longer supply chains — is also driving double wall adoption, since extended transit times and multimodal handling increase the structural demands on transit packaging. The reshoring and near-shoring of manufacturing in North America and Europe is paradoxically also supporting double wall demand, as new manufacturing facilities establish domestic supply chains that require protective packaging for component and finished goods movement.
Asia Pacific – Largest Regional Market
Asia Pacific holds 46% of the corrugated packaging market — the largest regional share. China's packaging industry is the world's largest by output volume, with a well-developed fibre recycling and processing infrastructure that feeds a massive converting base serving domestic consumer goods, electronics, and food production. Nine Dragons Paper, Oji Holdings, and other Asian packaging producers operate at a scale that influences recovered fibre prices and corrugated board cost structures.
India and Southeast Asia are the highest-growth markets within the region, both driven by expanding middle-class consumption, organised retail growth, and rapidly scaling e-commerce logistics networks. Vietnam, Indonesia, and Thailand are all attracting manufacturing investment that generates corrugated packaging demand for both domestic distribution and export shipping — a demand profile that is growing faster than the regional average and pulling investment in new corrugated converting capacity.
Europe – Fastest-Growing Region
Europe is advancing at a CAGR of 9.5% — the highest regional growth rate in this market. The EU Packaging and Packaging Waste Regulation, with its mandatory recycled content targets and packaging reduction requirements, is creating the most significant structural shift in European packaging procurement in a generation. Corrugated board, with its high recyclability and strong recovery infrastructure, is one of the primary beneficiaries as brands and retailers convert packaging formats to meet compliance deadlines.
Smurfit Kappa, DS Smith, Mondi, and Stora Enso — all European-headquartered — are the dominant players in this market and are investing in capacity, digital printing capability, and specialty board grades to serve the accelerating demand. The strength of these producers' customer relationships with major European FMCG, food, and logistics companies gives them a competitive position that is reinforced by the sustainability credentials of paper-based packaging in a regulatory environment that is moving decisively against non-recyclable alternatives.
What Are the Recent Developments in the Corrugated Packaging Market?
Q4 2024 – Smurfit Kappa: Commissioned a new high-speed corrugated converting line in Poland targeting the Central and Eastern European e-commerce packaging market, incorporating digital printing capability for short-run customised box production.
Q4 2024 – International Paper: Completed the merger process with DS Smith following regulatory approval, creating one of the largest corrugated packaging operations in the world with combined capacity across North America and Europe.
Q1 2025 – WestRock: Launched a lightweighted single wall board grade achieving equivalent compression performance to standard grades at 8% lower basis weight, targeting e-commerce customers with volume-driven sustainability packaging commitments.
Q2 2025 – Mondi: Opened a new corrugated packaging plant in Egypt targeting the growing North African food and consumer goods sector, incorporating automated flatbed die-cutting and digital printing capability from commissioning.
Q2 2025 – Nine Dragons Paper: Announced expansion of corrugated converting capacity at two Chinese facilities to serve growing domestic e-commerce packaging demand from major platform operators including JD.com and Alibaba.
Q3 2025 – Packaging Corporation of America: Introduced an on-demand box manufacturing system for distribution centre installation, enabling same-shift corrugated box production in custom dimensions to eliminate void fill and reduce outbound packaging weight per shipment.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: inquiry@transpireinsight.com
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates
 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


