
Global Semiconductor Substrate Market Summary:
According to Transpire Insights, a detailed research report on the market reflects that the consumer electronics application segmentdominates the Global Semiconductor Substrate Market, accounting for the largest share of the total market worldwide. Shin-Etsu Chemical Co., Ltd.leads the market with approximately around USD 16.8 billion in annual revenue and an estimated 18–22%global market share, making it the leading contributor to global market development, innovation, advanced semiconductor substrate production, expanding manufacturing capabilities, and growth dynamics.
Market Snapshot
- Global Market Value (2025): USD 17.4 Billion.
- Expected Market Value (2026): USD 18.9 Billion.
- Estimated Market Value (2033): USD 33.8 Billion.
- Forecast CAGR (2026–2033): 8.66%.
- Leading Region in 2025: Asia Pacific
- Second-largest Region: North America
- Fastest Growing Region: Europe
Introduction
The semiconductor substrate market is the foundational base material used in wafer fabrication and packaging to build integrated circuits (ICs) is currently valued at over USD 14 billion and projected to surpass USD 30 billion by the mid-2030s, driven by rapid growth in AI, 5G, and electric vehicles (EVs). Semiconductor substrate, the fundamental material used to build active electrical circuits and transistors, often a thin slice of silicon, silicon carbide (SiC), gallium arsenide (GaAs), or glass. It offers heat control and mechanical support. Packaging substrate, The specialized, multi-layered board that allows delicate semiconductor chips (dies) to interface with other parts of an electronic device by connecting them to a larger printed circuit board (PCB). Heterogeneous integration, a sophisticated packaging method that installs several independently produced parts (like a CP). High-power applications are dominated by silicon carbide (SiC). SiC is essential for 5G infrastructure and data centers because it provides better electrical performance and heat resistance than conventional silicon. Glass core materials, AI and high-performance computing (HPC) are emerging. For sophisticated multi-chip integration, glass substrates offer exceptional signal integrity, great heat dissipation, and outstanding dimensional stability. Organic substrates are inexpensive and very versatile for high-density applications like wearables and smartphones. They are composed of materials like epoxy resin and polyimide.
- For instance: The semiconductor industry in the UK brings in more than £10.3 billion. Investment is heavily concentrated on compound semiconductors, R&D, and packaging substrates, supported by a £1 billion National Semiconductor Strategy.

Key Market Highlights: -
- Asia Pacific is anticipated to hold approximately61% share of the Global Semiconductor Substrate Market over the predicted timeframe.
- North America is expected to grow at a rapid CAGR in the Global Semiconductor Substrate Market by holding approximately20% of the share during the forecast period.
- Europe is anticipated to hold approximately 15% share of the Global Semiconductor Substrate Market over the predicted timeframe.
- By Material type, the Silicon Substrates segment dominated the market and holds approximately 52% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- By application, the Integrated Circuits segment dominated the market and holds approximately 55% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- By end user, the Consumer Electronics Manufacturers segment dominated the market and holds approximately 30% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- India: The government is strengthening the semiconductor ecosystem through ISM initiatives, offering fiscal incentives for semiconductor manufacturing, packaging, and design activities, thereby supporting advanced substrate demand, local capabilities, and supply chain development.
How is Technology Driving Growth in the Global Semiconductor Substrate Market?
Due to rising demand for AI, high-performance computing, and sophisticated data center applications that call for 2.5D/3D packaging, chiplets and High Bandwidth Memory (HBM) technologies, the global semiconductor substrate market is expanding significantly. The use of advanced substrates like silicon carbide (SiC) and gallium nitride (GaN) for better power efficiency and thermal control is being accelerated by the growth of electric vehicles and ADAS. Additionally, the need for high-density, dependable, and performance-enhanced semiconductor substrates is being driven by the expansion of 5G, smartphones, and small electronic devices.
Market Drivers
AI and High-Performance Computing (HPC), high connection density is necessary to accommodate multi-die chiplet architectures due to the increase in demand for accelerator-class silicon (such as Nvidia) in data centers. Next-generation substrate materials, Glass core substrates, which offer ten times the interconnect density of conventional organic boards, are the main emphasis. The glass substrate market is expected to evolve into a multi-billion dollar segment. The automotive transition, the quick uptake of battery-electric vehicles and advanced driver-assistance systems (ADAS) significantly raises the amount of silicon in each vehicle, which fuels the rapid adoption of metal-core and ceramic substrates that can handle high heat and severe power outputs. Government localization, more than $100 billion is being invested in the localization of sophisticated fabrication and packaging facilities through initiatives like the U.S. CHIPS Act and European subsidy programs. 5G and consumer electronics miniaturization, high-density IC substrates are becoming more and more necessary as smartphones and wearables become lighter, smaller, and more powerful. These cutting-edge substrates manage on-device AI capabilities and many bands, including 5G, in extremely limited places without depleting battery life. Gallium Nitride (GaN), very beneficial for RF (radio frequency), 5G, and electric vehicles (EVs). GaN significantly lowers energy losses in power management systems, can handle higher power densities, and enables three times faster charging.
- For Instance: - The market for semiconductor packaging substrates is expected to grow to $48.70 billion worldwide. The AI infrastructure boom, heterogeneous integration, and large capital injections from the U.S. CHIPS Act are driving the market's rapid rise in North America.
- AI, 5G, and EV demand are expected to propel the $40 billion global semiconductor substrate industry to over $70 billion by 2030. With more than 58% of the market, Asia-Pacific leads thanks to enormous foundry hubs in Taiwan, South Korea, China, and Japan. Record greenfield investments are being driven by government subsidies that can cover up to 75% of eligible costs.
Restrain
Complex production methods, high capital requirements, supply chain unpredictability, geopolitical constraints, and stringent environmental rules are some of the issues facing the global semiconductor substrate market. These elements raise production costs, restrict scalability, erect obstacles to entrance, and hinder the growth of smaller market players.
Analysis of Prices and Consumer Behaviour
The market for advanced semiconductor substrates is dominated by organic IC substrates (approximately 70% of total market revenue, primarily due to strong demand from consumer electronics, automotive semiconductors, high-performance computing, and networking applications). The price of advanced substrates, such as flip-chip ball grid array (FC-BGA) substrates and high-density interconnect (HDI) substrates, is generally 30–50% higher than conventional substrates, driven by complex manufacturing processes, advanced materials, stringent quality requirements, and higher performance capabilities. Approximately 45% of semiconductor substrate demand is associated with package substrates used in applications including processors, GPUs, AI accelerators, and high-end electronic devices. The semiconductor manufacturing and electronics industries represent around 70% of the overall demand for advanced substrate solutions. The purchasing behavior of consumers indicates that approximately 55% of semiconductor manufacturers prioritize substrate reliability, electrical performance, thermal management capabilities, and supply consistency when selecting suppliers. Another 33% of buyers prefer long-term supply agreements and strategic partnerships to reduce procurement risks, control costs, and ensure a stable supply of semiconductor substrates amid ongoing global supply chain challenges.
Top Companies in the Global Semiconductor Substrate Market
- Shin-Etsu Chemical
- SUMCO Corporation
- GlobalWafers
- SK Siltron
- Soitec
- Coherent Corp.
- Wolfspeed
- Resonac Holdings
- Siltronic AG
- Wafer Works Corporation
- Okmetic
- Ferrotec Holdings
- Mitsubishi Materials
- Toshiba Materials
- IQE plc
Market Segmentation
The Global Semiconductor Substrate Market share is divided into five categories: material type, wafer size, application, end user and manufacturing process
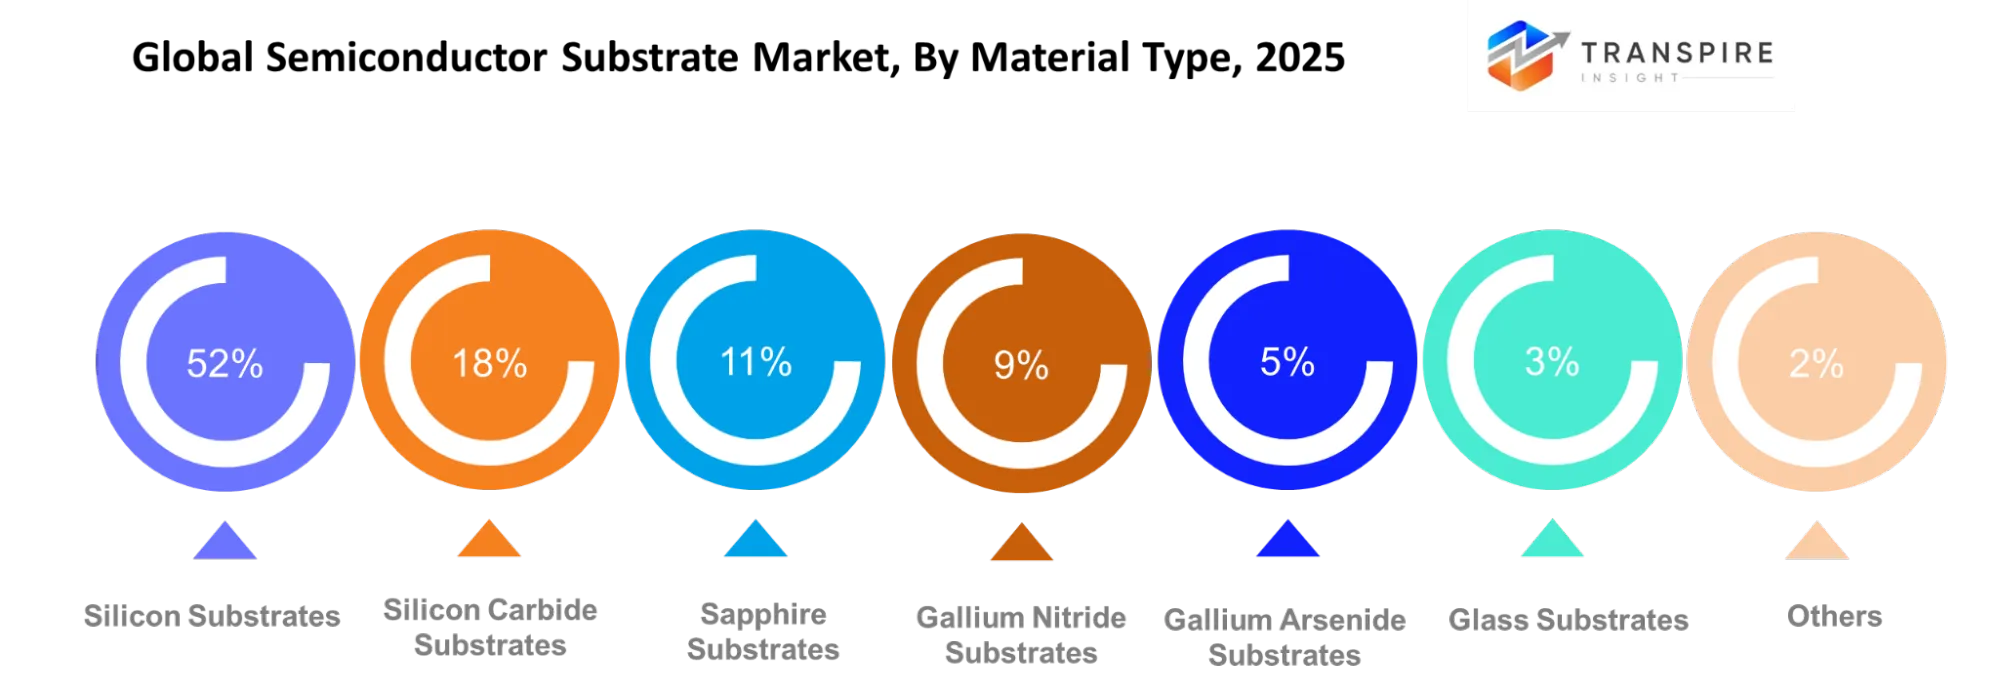
The Silicon Substrates dominated the market, accounting for nearly 52% in 2025 and is expected to rise at a significant CAGR during the forecast period.
The Global Semiconductor Substrate Market is segmented by material type into, Silicon Substrates, Silicon Carbide Substrates, Sapphire Substrates, Gallium Nitride Substrates, Gallium Arsenide Substrates, Glass Substrates, Diamond Substrates, Others. Among these, the Silicon Substrates segment dominated the market, accounting for nearly 52% in 2025 and expected to increase at a significant CAGR during the forecast period. Because of its superior electrical performance, cost-effectiveness, established production environment, and broad usage across integrated circuits, power devices, MEMS, and advanced packaging, the Silicon Substrates segment led the market, accounting for about 52% in 2025. Its notable market expansion is also fueled by ongoing technical developments and rising semiconductor demand.
The Integrated Circuits dominated the market, accounting for nearly 55% in 2025, and is expected to rise at a significant CAGR during the forecast period.
The Global Semiconductor Substrate Market is segmented by application into, Power Electronics, RF Devices, LEDs, MEMS, Sensors, Integrated Circuits, Optoelectronics, Others. Among these, the Integrated Circuits segment dominated the market, accounting for nearly 55% in 2025 and expected to increase at a significant CAGR during the forecast period. Due to their extensive use in consumer electronics, automotive systems, industrial automation, and telecommunications, integrated circuits dominated the industry and accounted for about 55% of sales in 2025. Over the course of the projection period, their high processing efficiency, small size, low power consumption, and ongoing technical breakthroughs are anticipated to sustain strong CAGR growth.
The Consumer Electronics Manufacturers dominated the market, accounting for nearly 30% in 2025 and is expected to rise at a significant CAGR during the forecast period.
The Global Semiconductor Substrate Market is segmented by end user into, Foundries, IDMs, OSAT Companies, Consumer Electronics Manufacturers, Automotive Electronics, Industrial Electronics, Telecom Equipment Manufacturers, Others. Among these, the Consumer Electronics Manufacturers segment dominated the market, accounting for nearly 30% in 2025 and expected to increase at a significant CAGR during the forecast period. Due to increased manufacturing of smartphones, wearables, laptops, and smart home appliances, consumer electronics manufacturers had about 30% of the market in 2025. Over the course of the projected period, substantial CAGR growth is anticipated to be supported by rising demand for high-performance, compact, and energy-efficient electronic components.
Regional Segment Analysis of the Global Semiconductor Substrate Market:
- North America (U.S., Canada, Mexico)
- Europe (Germany, France, U.K., Italy, Spain, Rest of Europe)
- Asia-Pacific (China, Japan, India, Rest of APAC)
- South America (Brazil and the Rest of South America)
- The Middle East and Africa (UAE, South Africa, Rest of MEA)
Asia Pacific is the fastest-growing region in the Global Semiconductor Substrate Market during the period, holding approximately 61% share.
Asia pacific is the fastest-growing region in the Global Semiconductor Substrate Market during the forecast period, holding approximately 61% share during the forecast period. With 61% of the Global Semiconductor Substrate Market, Asia Pacific is the fastest-growing region. This is due to a number of factors, including strong semiconductor manufacturing capacity, growing electronics production, rising investments in cutting-edge packaging technologies, supportive government initiatives, and rising demand from the automotive, consumer electronics, and 5G industries.
North America is the fastest-growing region in the Global Semiconductor Substrate Market during the period, holding approximately 20% share.
North America is expected to grow at a rapid CAGR in the Global Semiconductor Substrate Market holding approximately 20% share during the forecast period. With a 20% market share, North America is the fastest-growing region in the world for semiconductor substrates. This is due to a number of factors, including growing investments in domestic semiconductor manufacturing, expanding advanced packaging facilities, strong demand from AI, data centers, and automotive electronics, as well as government initiatives that support regional chip production.
Europe is expected to grow at a rapid CAGR in theGlobal Semiconductor Substrate Market, holding approximately 15% of the share during the forecast period.
Europe is expected to grow at a rapid CAGR in the Global Semiconductor Substrate Market holding approximately 15% share during the forecast period. Due to the growing use of AI-driven analytics, growing cloud-based solutions, strict regulatory compliance, robust digital transformation initiatives, and growing demand for revenue optimization and operational efficiency across the retail, hospitality, healthcare, and manufacturing sectors, Europe is predicted to grow at a rapid compound annual growth rate (CAGR) in the global market for revenue management software.
Strategies for Market Growth in Non-Leading Regions:
The Global Semiconductor Substrate Market is projected to see significant opportunities for growth in developing economies thanks to the implementation of cost-effective and technologically advanced semiconductor substrate manufacturing solutions. The creation of regional manufacturing plants, packaging and testing facilities, and supply chains are predicted to resolve issues of production and decrease costs of operation. To enhance the penetration into the market and facilitate the acceptance of technologies, there would be strategic ties with semiconductor manufacturers, foundries, OSAT providers, materials suppliers, and electronics manufacturers. Investments in the development of human resources, educational programs, and semiconductor engineering are predicted to help to decrease lack of skilled labor and improve manufacturing efficiency. Moreover, the growing tendency to implement flexible investment schemes, joint ventures, and local manufacturing is expected to provide better access to advanced semiconductor substrate technologies. Finally, it is predicted that the support of governments in the area of developing domestic semiconductor industry, launching investments into the construction of semiconductor fabrication facilities, and increasing electronics manufacture will contribute to faster implementation of trends observed in the Global Semiconductor Substrate Market.
Future Market Trends for the Global Semiconductor Substrate Market: -
- Transition to Compound Substrates: Silicon carbide (SiC) and gallium nitride (GaN) are gradually supplementing or replacing conventional silicon substrates. SiC substrates' improved breakdown voltages and thermal management are making them the industry standard for power electronics and EV inverters.
- Growth of Glass Core Substrates: The industry is using glass core substrates extensively to get beyond the physical and thermal constraints of conventional organic PCB substrates. Extreme flatness, reduced signal loss, and the capacity to manage much larger transistor densities essential for high-performance computing (HPC) and artificial intelligence (AI) chips are made possible by this transition.
- Support for Advanced Packaging & Chiplets: Manufacturers of substrates are concentrating on packaging innovations including Multi-Chip-Modules (MCM), System-in-Package (SiP), and 3D stacking. In order to reduce costs and speed up time-to-market, engineers are eschewing traditional monolithic chip designs, which is driving up demand for substrates that can span several dies (chiplets).
- Automotive Electrification: The transition to electric vehicles (EVs) and advanced driver-assistance systems (ADAS) is significantly increasing the amount of silicon and substrate in each vehicle. This calls for extremely dependable, automotive-grade substrates that can withstand high-power conditions.
Recent Development
- In May 2026: The Government of Odisha, Intel Corporation, and US-based 3D Glass Solutions (3DGS) signed a strategic USD 3.3 billion memorandum of understanding (MoU) to establish an advanced glass core substrate manufacturing facility in the Bhubaneswar–Khurda region. The initiative is expected to strengthen India’s semiconductor ecosystem by accelerating advanced packaging capabilities, supporting next-generation substrate technologies, and enhancing domestic semiconductor supply chain development.
- In June 2026: Taiwan Semiconductor Manufacturing Company (TSMC) advanced its next-generation semiconductor packaging initiatives by focusing on glass core substrate technologies for future artificial intelligence (AI) and high-performance computing (HPC) applications. These developments aim to enhance package scalability, improve thermal performance, reduce signal integrity challenges, and support the evolution of advanced CoWoS-based architectures, contributing to the growth of the Global Semiconductor Substrate Market.
Market Segment
This study forecasts revenue at global, regional and country levels from 2020 to 2033. Transpire Insights has segmented the Global Semiconductor Substrate Market based on the below-mentioned segments:
Global Semiconductor Substrate Market, By Material type
- Silicon Substrates
- Silicon Carbide Substrates
- Sapphire Substrates
- Gallium Nitride Substrates
- Gallium Arsenide Substrates
- Glass Substrates
- Diamond Substrates
- Others
Global Semiconductor Substrate Market, By Wafer Size
- 150 mm Wafers
- 200 mm Wafers
- 300 mm Wafers
- 450 mm Wafers
- 6-inch Wafers
- 8-inch Wafers
- 12-inch Wafers
- Others
Global Semiconductor Substrate Market, By Application
- Power Electronics
- RF Devices
- LEDs
- MEMS
- Sensors
- Integrated Circuits
- Optoelectronics
- Others
Global Semiconductor Substrate Market, By End User
- Foundries
- IDMs
- OSAT Companies
- Consumer Electronics Manufacturers
- Automotive Electronics
- Industrial Electronics
- Telecom Equipment Manufacturers
- Others
Global Semiconductor Substrate Market, By Manufacturing Process
- Epitaxial Growth
- Czochralski Process
- Float Zone Process
- Wafer Polishing
- Wafer Bonding
- Thin-film Deposition
- Advanced Substrate Processing
- Others
Global Semiconductor Substrate Market, By Regional Analysis
North America
- United States
- Canada
- Mexico
Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
South America
- Brazil
- Argentina
- Rest of South America
Middle East & Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- South Africa
- Rest of the Middle East & Africa
Frequently Asked Questions
Find quick answers to common questions.
The market is projected to reach USD 33.8 billion by 2033, growing from USD 17.4 billion in 2025 at a CAGR of 8.66%, driven by AI, HPC, EVs, and advanced packaging.
Silicon Substrates dominate with approximately 52% share in 2025, supported by cost efficiency, established manufacturing infrastructure, and extensive applications in integrated circuits, power devices, MEMS, and advanced semiconductor technologies.
Asia-Pacific leads with approximately 61% market share, driven by strong semiconductor manufacturing capacity, major foundry ecosystems, electronics production, government support, and increasing investments in advanced packaging and substrate technologies.
Growth is driven by rising demand for AI, HPC, 5G, EVs, chiplets, advanced packaging, and compound semiconductor technologies, along with increasing adoption of SiC, GaN, and glass substrates.
Key players include Shin-Etsu Chemical, SUMCO Corporation, GlobalWafers, SK Siltron, Soitec, Coherent Corp., Wolfspeed, Resonac Holdings, Siltronic AG, and IQE plc, focusing on advanced substrate development and capacity expansion.
- Shin-Etsu Chemical
- SUMCO Corporation
- GlobalWafers
- SK Siltron
- Soitec
- Coherent Corp.
- Wolfspeed
- Resonac Holdings
- Siltronic AG
- Wafer Works Corporation
- Okmetic
- Ferrotec Holdings
- Mitsubishi Materials
- Toshiba Materials
- IQE plc
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Fiber Optic Faceplates Market
Fiber Optic Faceplates Market Size, Share & Analysis Report By Type (< 300 mm2, 300-350 mm2, and > 350 mm2, By Application (Night Vision, Holographic Imaging, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
High Temperature Superconductors Market
High Temperature Superconductors Market Size, Share & Analysis Report By Type (1G HTS, and 2G HTS), By Application (Power Cable, Fault Current Limiter, and Transformer), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Industrial Plugs and Socket Market
Industrial Plugs and Socket Market Size, Share & Analysis Report By Type (Industrial Plugs, Industrial Sockets), By Current (Up to 32 A, 32 to 125 A, Above 125 A), By Protection (Dustproof and Splash Proof, Waterproof, Explosion Proof), By End User (Heavy Industries, Oil and Gas, Chemicals and Pharmaceuticals, Power Generation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
InGaAs Avalanche Photodiodes Market
InGaAs Avalanche Photodiodes Market Size, Share & Analysis Report By Type (1100 - 1700 nm, and 1000 - 1600 nm), By Application (Missile Warning System, Muzzle Flash Detection, Wafer Defect Inspection, Laser Rangefinders, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031