
Middle East and Africa GaN Substrate Market Summary
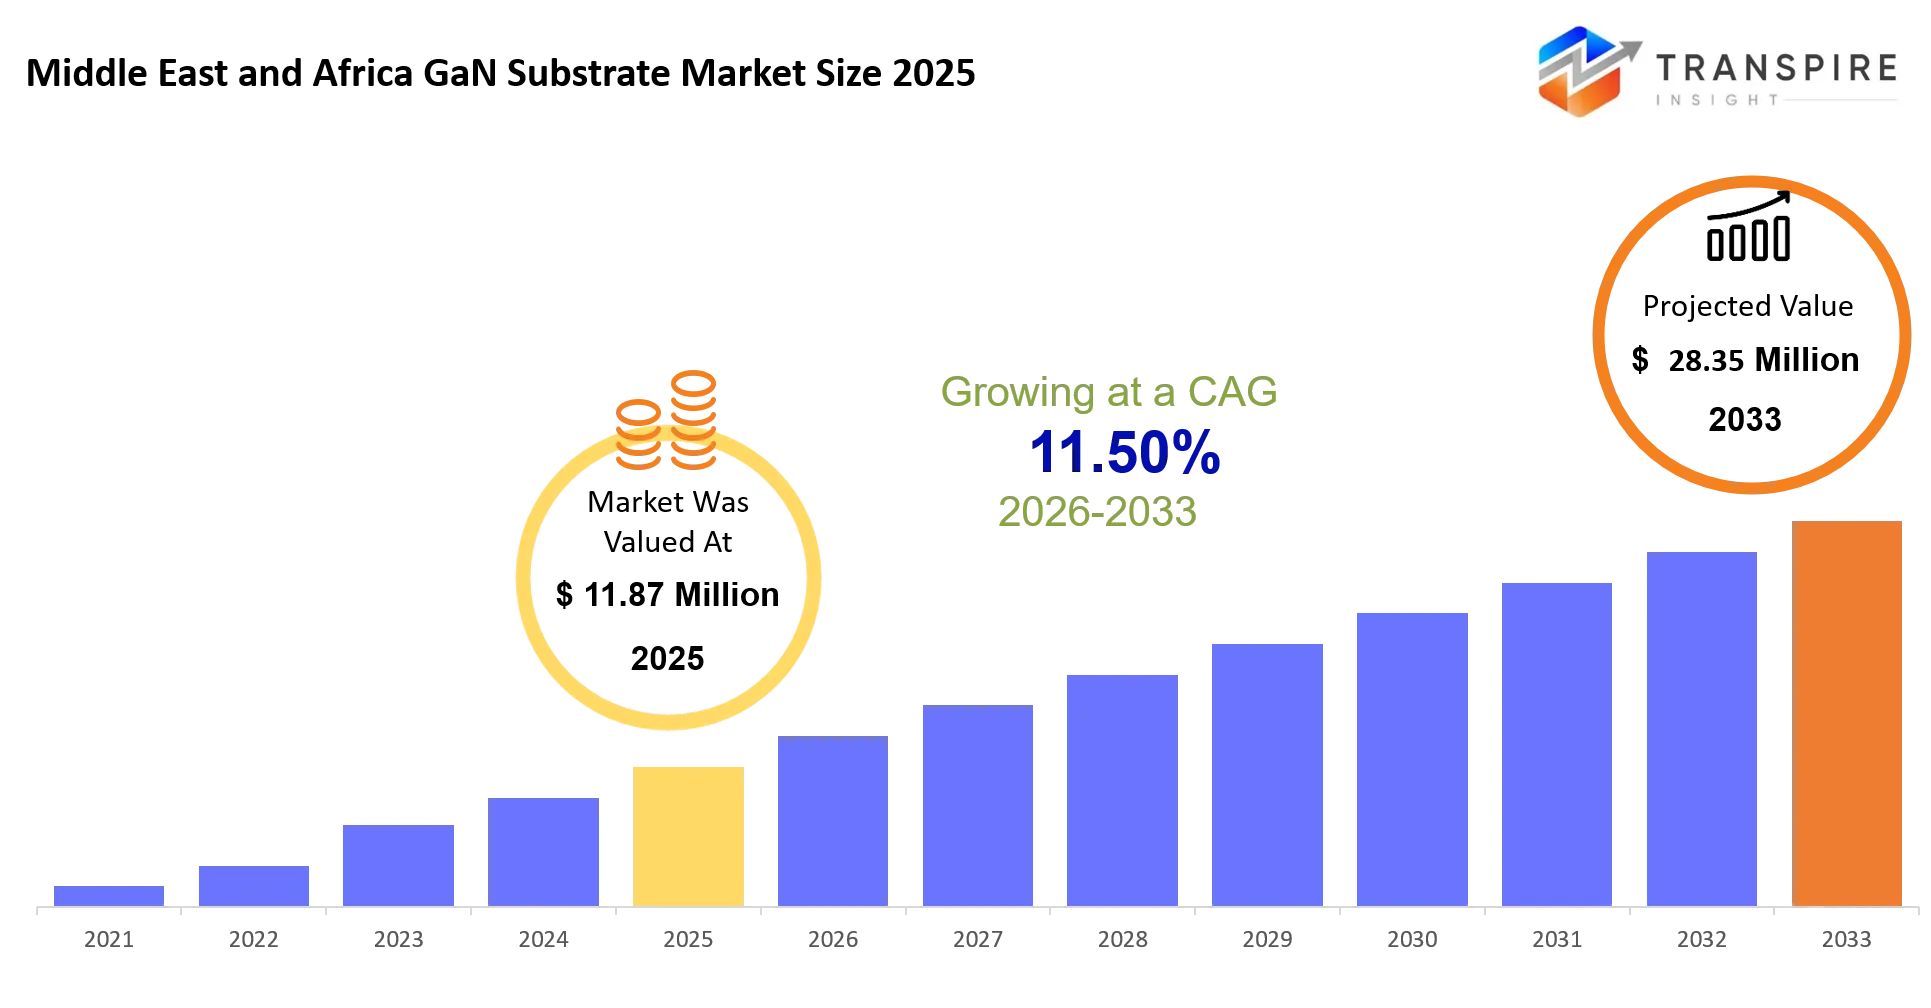
As per Transpire Insight Analysis the Middle East and Africa GaN Substrate Market size is estimated at USD 11.87 Million in 2025 and is anticipated to reach USD 28.35 Million by 2033, growing at a CAGR of 11.50% from 2026 to 2033.
The Middle East and Africa GaN Substrate Market helps more or less with the manufacture of high-performance semiconductor devices, which are used across power electronics, RF communications, defense systems, electric vehicles, and also advanced telecommunications, sort of.GaN substrates handle some key performance issues by letting higher power density happen, faster switching speeds, and better thermal control versus older semiconductor materials. Over the last five years, the market has been moving toward bigger wafer formats, plus improved grade GaN-on-SiC and bulk GaN substrates, because manufacturers are aiming at next-generation 5G infrastructure and defense electronics.
At the same time, supply chain interruptions during the broader semiconductor shortage, kind of really showed how much the whole industry was leaning on a small set of substrate suppliers. So, governments and tech firms started pushing harder on semiconductor sourcing plans not only in theory , but really in practice. Meanwhile, as regional budgets for digital infrastructure, renewable power, and aerospace electronics keep increasing, the need for dependable GaN wafers just keeps climbing too, and that basically nudges supplier partnerships, manufacturing upgrades, and a more decisive movement toward premium substrate types across both industrial and defense uses.
Middle East and Africa GaN Substrate Market Size & Forecast:
- Middle East and Africa GaN Substrate Market Size 2025: USD 11.87 Million
- Expected Market Value 2033: USD 28.35 Million
- Forecast CAGR: 11.50%
- Leading region in 2025:
- Fastest Growing region:
- Key Profile: Wolfspeed, Qorvo, IQE, Sumitomo Electric, Soitec, ROHM Semiconductor, Infineon Technologies, Coherent, Mitsubishi Electric, Toshiba, NXP Semiconductors, STMicroelectronics, Kyma Technologies, Odyssey Semiconductor, Samsung Electronics
Key Market Insights
- So, the Middle East and Africa GaN Substrate Market basically benefits from Gulf Cooperation Council countries, they’re around 58% of regional revenue in 2025, tied to semiconductor and defense investments, and it keeps pulling capital in.
- South Africa seems to be the fastest growing area during the forecast period, mainly because electronics manufacturing is expanding there and research partnerships are getting more active, bit by bit.
- For substrate formats, GaN-on-SiC ends up dominating with close to 42% market share in 2025, since it brings higher thermal conductivity for RF work and defense use cases.
- GaN-on-Silicon comes in as the second-largest segment at roughly 30% share, it’s mainly valued for reduced production costs when you’re looking at commercial power electronics and repeat manufacturing.
- Meanwhile bulk GaN substrates are projected to show the quickest growth through 2033, pushed by the rising need for premium power solutions and high-frequency devices.
- On the application side, power electronics is near 36% of application revenue in 2025, supported by renewable energy systems, industrial automation, and electric mobility.
- Telecommunications is also emerging as the most swiftly expanding use case, because 5G roll out is really speeding up investments in high frequency RF parts across the region.
- Industrial electronics still kind of leads among end users, sitting at around 34% market share, while aerospace and defense keep gaining momentum, pushed along by modernization programs and all the connected upgrades.
- Main players like Wolfspeed, Sumitomo Electric, Soitec, Infineon Technologies, Qorvo, and Coherent are moving toward larger wafer output, plus better substrate quality, and also those regional collaborations that make both sourcing and delivery smoother.
- All in all, technology leadership is getting more and more tied to improved crystal growth approaches, supply chain diversification, plus partnerships that raise wafer yield, support better production scalability, and secure longer term customer agreements.
What are the Key Drivers, Restraints, and Opportunities in the Middle East and Africa GaN Substrate Market?
The main thing that moves the market forward is the quick uptake of wide bandgap semiconductors, especially for high efficiency power conversion, and also for high frequency communications. In many places, national digital transformation programs, defense modernization efforts, plus investments in renewable energy infrastructure have pushed the use of GaN based power devices. And you can see why—these initiatives kinda need substrates that can take higher voltages and run at hotter temperatures than ordinary silicon. So, equipment makers end up leaning toward more premium GaN materials. As more industrial and telecom projects request GaN tech, substrate suppliers generally get bigger contract sizes, and a steadier loop of ongoing orders, not just one time sales.
On the flip side, the biggest restraint is a kind of hard structural limit tied to how much global GaN substrate manufacturing can actually do. Making defect free bulk GaN and high quality GaN on SiC wafers needs specialized crystal growth approaches, sophisticated processing tools, and a lot of capital spending. Only a small set of manufacturers have all that know how and machinery, so supply tightens up, and production costs stay elevated. Also the qualification timeline is long, particularly in aerospace, defense, and telecommunications. That slows down commercialization, it tends to restrict quicker regional rollout, and it makes some cost sensitive industries hesitate, even if the performance benefits are attractive.
There is a real opportunity, though, in widening regional semiconductor ecosystems through government supported investment, plus international technology partnerships. Saudi Arabia and the United Arab Emirates, for example, are building up advanced manufacturing strength while pulling in semiconductor research, and even packaging facilities.
What Has the Impact of Artificial Intelligence Been on the Middle East and Africa GaN Substrate Market?
Artificial intelligence plus advanced digital technologies are, slowly but surely, improving efficiency across GaN substrate making and semiconductor production steps. A lot of manufacturers now use AI inspection systems that look at wafer surface issues, crystal imperfections, and process deviations with more steady results than the old manual checks. Machine learning models then help tune crystal growth parameters, they even forecast when equipment might need maintenance, and they raise yield by catching the production variables that often show up before the actual defects do. With those predictive abilities, downtime gets reduced, wafer quality goes up, and material waste is lower, so overall production efficiency improves and profitability follows.
On top of that, digital twins together with AI based process control support real-time tuning of temperature profiles, deposition conditions, and polishing operations in substrate manufacturing. This kind of setup increases process stability, while also making it easier to qualify high performance wafers sooner for power electronics and RF uses. Semiconductor makers also rely on advanced analytics to estimate demand, refine inventory levels, and strengthen supply chain resilience after the recent semiconductor shortages.
Still, even with all these upsides, adoption is not totally smooth because integrating advanced analytics into specialized semiconductor fabrication environments costs a lot. There’s also a shortage of high quality production datasets, and the GaN crystal growth process itself is, frankly, complex—so predictive models can struggle with accuracy, especially in newer or emerging manufacturing flows. So many regional manufacturers end up blending AI suggestions with real engineering supervision, just to keep the product quality consistent.
Key Market Trends
- Since around 2021, manufacturers have drifted toward 6-inch and 8-inch wafers, in effect it boosts production efficiency and makes device manufacturing costs a bit lower.
- GaN-on-SiC adoption has grown by over 20% across RF uses, because telecom ,and defense systems really do need superior thermal performance.
- Because of recent supply disruptions worldwide, governments are putting more weight on semiconductor resilience now, so they’re nudging localized partnerships and doing more technology transfer initiatives as well.
- Since 2022, defense modernization programs have sped up procurement of high-frequency semiconductor components, and that’s also been helping premium substrate demand.
- In advanced fab environments, manufacturers have been putting money into automated wafer inspection systems , which cuts defect rates by roughly 15% or so.
- Firms like Wolfspeed, Soitec, Sumitomo Electric, and Infineon Technologies keep broadening their technology portfolios through strategic collaborations, plus product innovation in general.
- Buyers now tend to prefer suppliers that can offer long-term supply agreements, rather than relying on spot purchasing after those recent semiconductor shortages.
- For telecommunications infrastructure, procurement has swung toward higher-frequency GaN materials, aimed at next-generation 5G and satellite communication systems.
- Renewable energy and electric mobility projects increasingly pull in GaN power devices, since they improve conversion efficiency and also reduce system heat.
- Research partnerships involving universities, semiconductor firms, and government agencies continue to reinforce regional know-how, especially in advanced wide-bandgap semiconductor technologies.
Middle East and Africa GaN Substrate Market Segmentation
By Substrate Type
GaN-on-Silicon basically fits cost sensitive power devices since silicon wafers are still widely on hand , and the way they’re produced matches pretty well with facilities that already exist. GaN-on-SiC gives strong thermal conductivity and also high frequency behavior, so it tends to fit RF systems , radar gear, and modern communication equipment. GaN-on-SS gets used when people want economical manufacturing for a few particular industrial products. Bulk GaN on the other hand gives low defect density and great crystal quality, which helps premium electronic devices where superior electrical performance is the goal.
Free-Standing GaN brings improved material stability, and it supports tougher power plus optoelectronic use cases, while keeping efficiency a bit better. GaN-on-Sapphire is still a common selection for LED fabrication because sapphire offers stable optical traits and dependable production quality . Other substrate options show up for more specialized research work and niche industrial products, where unusual material qualities or a customized fabrication workflow can actually add extra value.
By Wafer Size
The 2-inch wafer keeps on supporting research activities and smaller volume production as fabrication costs are still pretty manageable , especially for the development work. The 4-inch wafer is used more in commercial production, it also helps balance manufacturing efficiency with the level of investment it takes. The 6-inch wafer has been getting wider acceptance because bigger wafer formats basically allow more output, and they can also lower the production cost per device. The 8-inch wafer now backs high-volume manufacturing, which helps semiconductor makers reach stronger production efficiency overall.
For wafer sizes beyond 8-inch, that is kind of the next manufacturing phase, since semiconductor companies want bigger economies of scale. Prototype wafers are used for product validation, material testing, and process refinement before anything starts at full commercial scale. Other wafer sizes also exist , they meet custom manufacturing requirements where the standard dimensions just don’t line up well with what the application needs, or with the customer’s specifications.
By Application
Power Electronics makes a big deal of demand because, in practice, high-efficiency power conversion stays basically essential for renewable energy setups, industrial automation, and even electric mobility. RF Devices seem to depend on GaN substrates so they can push strong high-frequency output that wireless infrastructure really needs , as well as satellite communication, and defense electronics too. LEDs keep leaning on GaN materials since solid optical output helps lighting and display technologies work well. Automotive Electronics is still growing, you know, because electric vehicles plus advanced driver assistance systems demand efficient semiconductor parts.
Meanwhile Consumer Electronics gets a clear advantage from compact, energy-savvy devices that improve charging systems and also the power management functions. In Aerospace & Defense, the story relies on GaN substrates for radar systems, electronic warfare equipment, and secure communication platforms. Telecommunications continues getting funded for high-frequency infrastructure tied to newer wireless networks. There are also other uses like medical equipment, industrial sensors, and scientific instruments where dependable semiconductor performance matters a lot.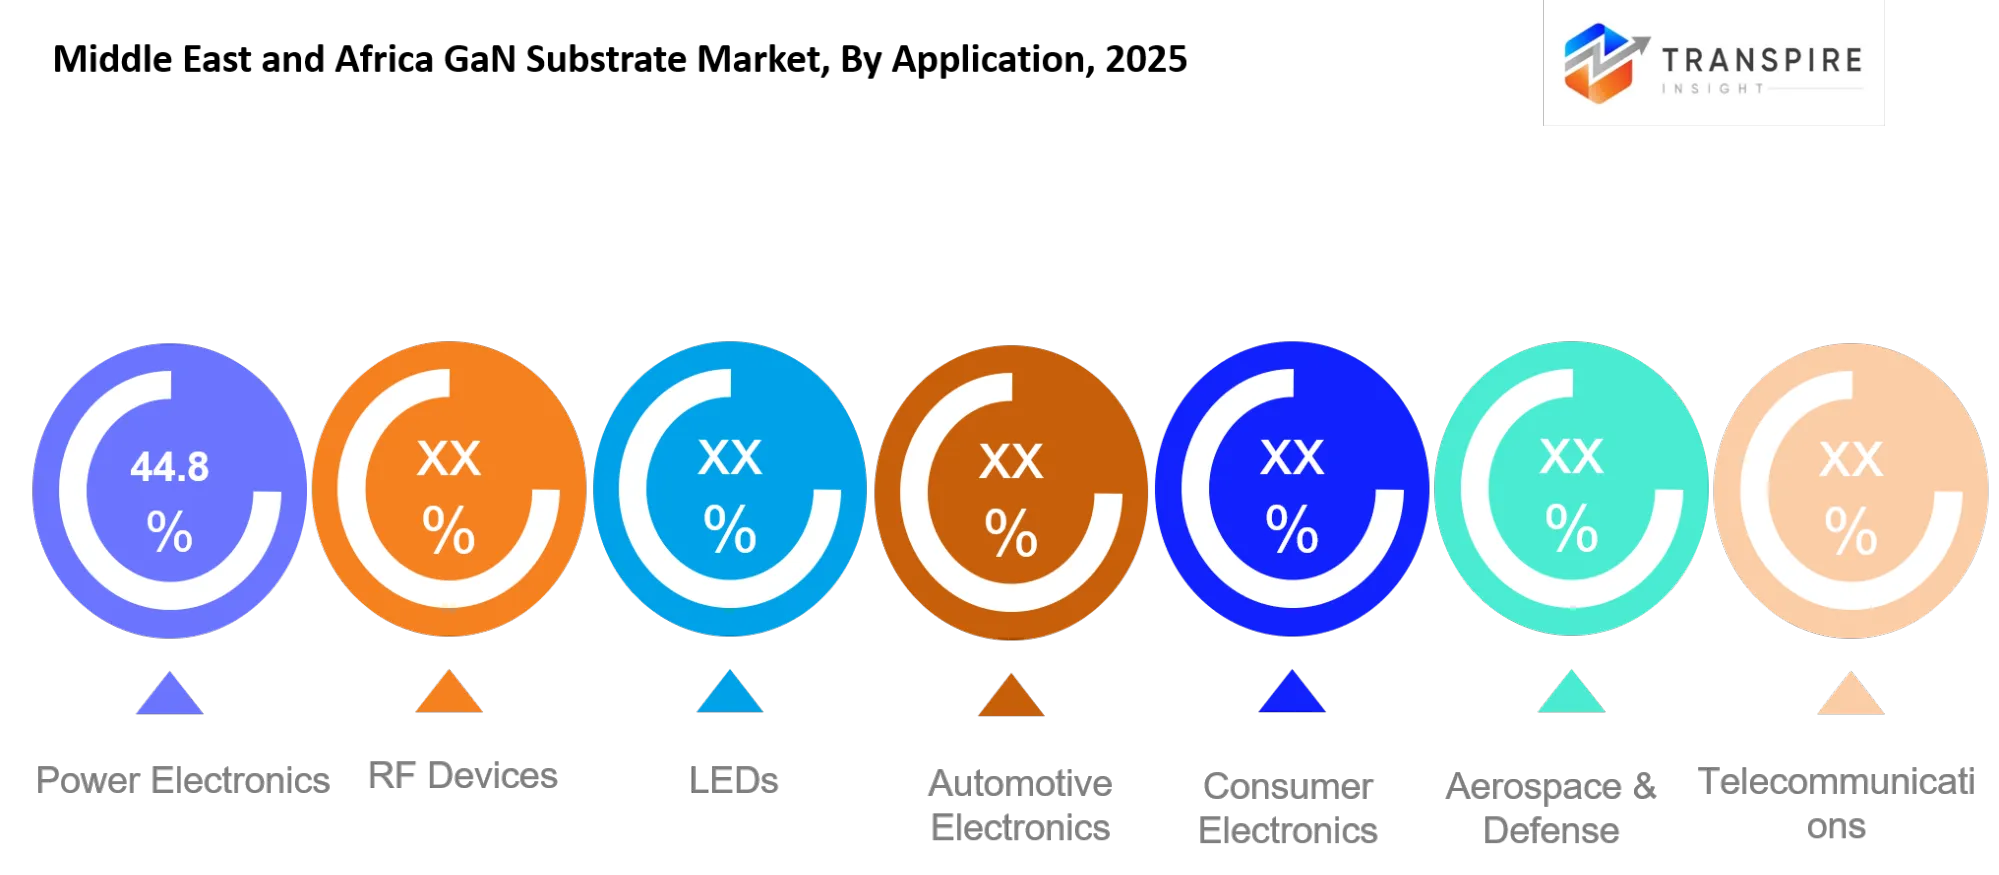
By End User
Semiconductor Manufacturers show up as the biggest customer group, because fabrication facilities basically need high-quality substrates, for making devices across a bunch of industries. Automotive OEMs, go for GaN-based components so vehicles can run more efficiently, plus they get better charging capability, and stronger electronic control systems. Consumer Electronics Companies slot GaN devices into chargers adapters and these smaller electronic gadgets, where higher energy efficiency matters a lot. Telecom Equipment Providers also push GaN technology, aiming to boost wireless network performance, and keep signal transmission more steady.
Defense Organizations rely on advanced GaN substrates for radar, surveillance, and secure communication systems. These use cases demand dependable operation even when conditions get rough, so it cant be “meh”. Research Institutes back material innovation too, including wafer development and the next wave semiconductor technologies, mostly via lab testing and joint projects. Other end users, include industrial equipment manufacturers and specialized electronics companies, that are building custom semiconductor solutions, for their particular needs.
By Manufacturing Process
MOCVD still looks like the main manufacturing process because it keeps crystal growth pretty consistent and also it can scale up for commercial semiconductor manufacturing. Then there is HVPE, it tends to push faster crystal growth rates , and it also backs the production of thicker GaN materials, which are wanted for a set of higher performance use cases. Ammonothermal Growth, on the other hand, makes bulk crystals that are higher in quality, with fewer defects, so this approach fits well when people work on more advanced semiconductor development, really.
Molecular Beam Epitaxy helps a lot too by enabling careful layer deposition , especially for research activities and for specialized electronic devices where accurate material control matters a lot. Hydride Growth also contributes to GaN material production, through guided crystal formation, which in turn supports certain industrial applications. And for the rest, other manufacturing processes get used when specialized production needs show up, cases where the usual fabrication methods don’t meet the performance or design goals. Overall, steady upgrades in manufacturing methods help raise wafer quality, boost production yield, and lower processing costs, across commercial semiconductor production, so yeah.
What are the Key Use Cases Driving the Middle East and Africa GaN Substrate Market?
Power conversion equipment is basically the leading use case because renewable energy plants, industrial automation systems, and electric vehicle charging infrastructure all want efficient semiconductor materials that can run at higher voltages and temperatures. Also, high performance substrates help energy efficiency quite a bit, while at the same time cutting back on heat generation, so in practice, power electronics ends up being the biggest application area, more or less.
At the same time, RF communication systems, plus more advanced defense electronics, keep getting wider adoption across telecommunications providers and defense organizations. With fifth generation network rollout, satellite communication setups, and radar installations moving forward, they’re needing GaN based components that hold up stable performance at high frequencies with better signal clarity.
Some emerging use cases are hydrogen energy infrastructure, smart grid equipment, and advanced aerospace electronics, all of which need rugged semiconductor materials with higher power density. Then there’s the whole quantum research track and next generation sensing technologies, those look like longer term opportunities too as research institutes and technology developers continue investing in advanced wide bandgap semiconductor solutions.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 11.87 Million |
|
Market size value in 2026 |
USD 13.23 Million |
|
Revenue forecast in 2033 |
USD 28.35 Million |
|
Growth rate |
CAGR of 11.50% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Middle East and Africa (Saudi Arabia, United Arab Emirates, South Africa, Rest of Middle East and Africa) |
|
Key company profiled |
Wolfspeed, Qorvo, IQE, Sumitomo Electric, Soitec, ROHM Semiconductor, Infineon Technologies, Coherent, Mitsubishi Electric, Toshiba, NXP Semiconductors, STMicroelectronics, Kyma Technologies, Odyssey Semiconductor, Samsung Electronics |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Substrate Type (GaN-on-Silicon, GaN-on-SiC, GaN-on-SS, Bulk GaN, Free-Standing GaN, GaN-on-Sapphire, Others); By Wafer Size (2-inch, 4-inch, 6-inch, 8-inch, Above 8-inch, Prototype Wafers, Others); By Application (Power Electronics, RF Devices, LEDs, Automotive Electronics, Consumer Electronics, Aerospace & Defense, Telecommunications, Others); By End User (Semiconductor Manufacturers, Automotive OEMs, Consumer Electronics Companies, Telecom Equipment Providers, Defense Organizations, Research Institutes, Others); By Manufacturing Process (MOCVD, HVPE, Ammonothermal Growth, Molecular Beam Epitaxy, Hydride Growth, Others) |
Which Regions are Driving the Middle East and Africa GaN Substrate Market Growth?
The Gulf Cooperation Council, guided mostly by Saudi Arabia along with the United Arab Emirates , stands out as the biggest regional market for GaN substrates. Government programs backing semiconductor know how, defense modernization, advanced fabrication, plus digital backbone infrastructure keep pulling investment into higher performance electronics. Big aerospace and defense purchasing plans, more data center capacity, and quick 5G network rollouts keep a steady demand going for advanced semiconductor materials. There are also solid research collaborations, technology investment funds , and industrial diversification efforts , which together build an ecosystem that kind of locks in long-term market leadership.
South Africa comes next as the second-largest regional contributor , but the momentum looks a bit different compared with the Gulf economies. Ongoing stability in industrial manufacturing, well known research organizations, and fairly steady spending on telecommunications infrastructure generate a reliable customer base for semiconductor tech. Local universities and technical centers keep working with international semiconductor companies, which improves research capacity and supports workforce training. So overall, this balanced industrial setup leads to more predictable buying behavior , not the fast, project based surges you might see elsewhere.
The remaining parts of Africa are projected to show the quickest growth between 2026 and 2033 , mostly because digital infrastructure spending is ramping up across nations like Egypt, Morocco, and Kenya. Policy supported electronics manufacturing pushes, renewable energy initiatives that are widening, and more general broadband coverage are opening new doors for advanced power semiconductor uptake.
Who are the Key Players in the Middle East and Africa GaN Substrate Market and How Do They Compete?
Competition is still pretty concentrated, well, because getting top-tier GaN substrates really needs advanced crystal growth know-how, big upfront capital, and some pretty niche manufacturing experience. And yeah, “competitive success” is kind of more about technology leadership, wafer quality, overall production yield, and those long-term customer ties than it is about price. The established semiconductor material suppliers keep upping their manufacturing abilities, while also forming strategic collaborations with device manufacturers so they can lock in demand later on, across telecommunications, power electronics, and defense end-uses.
Wolfspeed leans hard into advanced wide-bandgap materials, and it also keeps pushing continuous investment into bigger wafer technologies, plus high-performance substrate development. Sumitomo Electric, on the other hand, puts extra weight on crystal quality and manufacturing steadiness, which helps it serve the tougher power electronics and RF uses where reliability, honestly, stays non negotiable. Soitec grows via engineered substrate technologies, and also by working through research partnerships that back next generation semiconductor manufacturing, while in parallel, it strengthens the relationships it already has with long-term customers across advanced communications markets.
Infineon Technologies blends substrate know-how with integrated power semiconductor offerings, and the value comes from how tightly material development lines up with device manufacturing. Qorvo boosts competitiveness by concentrating on high-frequency RF applications for customers in telecommunications, aerospace, and defense, who need really strong signal performance.
Company List
• Wolfspeed
• Qorvo
• IQE
• Sumitomo Electric
• Soitec
• ROHM Semiconductor
• Infineon Technologies
• Coherent
• Mitsubishi Electric
• Toshiba
• NXP Semiconductors
• STMicroelectronics
• Kyma Technologies
• Odyssey Semiconductor
• Samsung Electronics
Recent Development News
In March 2026, Soitec announced a partnership with Nanyang Technological University (NTU Singapore) to accelerate 6G research using advanced GaN technologies. The collaboration strengthens next-generation GaN ecosystem development and supports future high-frequency semiconductor innovation. https://www.soitec.com
In March 2026, Wolfspeed unveiled a 300 mm silicon carbide technology platform designed for next-generation AI and high-performance computing packaging. The development expands advanced substrate capabilities and supports future high-density semiconductor integration.https://www.wolfspeed.com
What Strategic Insights Define the Future of the Middle East and Africa GaN Substrate Market?
The market seems to be edging toward higher value semiconductor materials that can actually support power electronics, newer wireless links, aerospace systems, and digital infrastructure not just, you know, expanding output for the sake of it. Over the next five to seven years, national semiconductor plans, industrial diversification initiatives, and the ongoing build out of high performance electronics investment are likely to steer where things go.
One quieter worry—well, not talked about a lot— is that global GaN substrate production keeps clustering with only a handful of suppliers. That situation could leave regional buyers facing pricing pressure, plus the occasional supply disruption, especially when geopolitical uncertainty shows up and everything gets jittery.
Still, there’s an emerging opening here too, establishing regional semiconductor packaging, testing, and research capabilities that pair well with imported wafer output. Firms trying to enter should, in practice, focus on partnerships with regional research organizations, telecommunications equipment manufacturers, and technology programs backed by government funding, while also putting money into technical support. That kind of on the ground help tends to fortify long term relationships, and it helps reduce reliance on purely transactional sales approaches.
Middle East and Africa GaN Substrate Market Report Segmentation
By Substrate Type
• GaN-on-Silicon
• GaN-on-SiC
• GaN-on-SS
• Bulk GaN
• Free-Standing GaN
• GaN-on-Sapphire
• Others
By Wafer Size
• 2-inch
• 4-inch
• 6-inch
• 8-inch
• Above 8-inch
• Prototype Wafers
• Others
By Application
• Power Electronics
• RF Devices
• LEDs
• Automotive Electronics
• Consumer Electronics
• Aerospace & Defense
• Telecommunications
• Others
By End User
• Semiconductor Manufacturers
• Automotive OEMs
• Consumer Electronics Companies
• Telecom Equipment Providers
• Defense Organizations
• Research Institutes
• Others
By Manufacturing Process
• MOCVD
• HVPE
• Ammonothermal Growth
• Molecular Beam Epitaxy
• Hydride Growth
• Others
Frequently Asked Questions
Find quick answers to common questions.
The Expected Middle East and Africa GaN Substrate Market size for the Market will be USD 28.35 Million in 2033.
Key Segments for the Middle East and Africa GaN Substrate Market are By Substrate Type (GaN-on-Silicon, GaN-on-SiC, GaN-on-SS, Bulk GaN, Free-Standing GaN, GaN-on-Sapphire, Others); By Wafer Size (2-inch, 4-inch, 6-inch, 8-inch, Above 8-inch, Prototype Wafers, Others); By Application (Power Electronics, RF Devices, LEDs, Automotive Electronics, Consumer Electronics, Aerospace & Defense, Telecommunications, Others); By End User (Semiconductor Manufacturers, Automotive OEMs, Consumer Electronics Companies, Telecom Equipment Providers, Defense Organizations, Research Institutes, Others); By Manufacturing Process (MOCVD, HVPE, Ammonothermal Growth, Molecular Beam Epitaxy, Hydride Growth, Others)
Major Middle East and Africa GaN Substrate Market players are Wolfspeed, Qorvo, IQE, Sumitomo Electric, Soitec, ROHM Semiconductor, Infineon Technologies, Coherent, Mitsubishi Electric, Toshiba, NXP Semiconductors, STMicroelectronics, Kyma Technologies, Odyssey Semiconductor, Samsung Electronics.
The Current Middle East and Africa GaN Substrate Market size is USD 11.87 Million in 2025.
• Wolfspeed
• Qorvo
• IQE
• Sumitomo Electric
• Soitec
• ROHM Semiconductor
• Infineon Technologies
• Coherent
• Mitsubishi Electric
• Toshiba
• NXP Semiconductors
• STMicroelectronics
• Kyma Technologies
• Odyssey Semiconductor
• Samsung Electronics
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Fiber Optic Faceplates Market
Fiber Optic Faceplates Market Size, Share & Analysis Report By Type (< 300 mm2, 300-350 mm2, and > 350 mm2, By Application (Night Vision, Holographic Imaging, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
High Temperature Superconductors Market
High Temperature Superconductors Market Size, Share & Analysis Report By Type (1G HTS, and 2G HTS), By Application (Power Cable, Fault Current Limiter, and Transformer), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Industrial Plugs and Socket Market
Industrial Plugs and Socket Market Size, Share & Analysis Report By Type (Industrial Plugs, Industrial Sockets), By Current (Up to 32 A, 32 to 125 A, Above 125 A), By Protection (Dustproof and Splash Proof, Waterproof, Explosion Proof), By End User (Heavy Industries, Oil and Gas, Chemicals and Pharmaceuticals, Power Generation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
InGaAs Avalanche Photodiodes Market
InGaAs Avalanche Photodiodes Market Size, Share & Analysis Report By Type (1100 - 1700 nm, and 1000 - 1600 nm), By Application (Missile Warning System, Muzzle Flash Detection, Wafer Defect Inspection, Laser Rangefinders, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031