
General Electronic Components Market Summery:
According to Transpire Insights, a detailed research report on the market reflects that the consumer electronics application segment dominates the General Electronic Components Market, accounting for approximately 39% of the total market share worldwide. Murata Manufacturing Co., Ltd. leads the market with approximately USD 12.6 billion in annual revenue and an estimated 10–13% market share, making it one of the leading contributors to market development through continuous innovation, advanced electronic component manufacturing technologies, expanding production capabilities, and strong investments in next-generation semiconductor, passive component, and connectivity solutions.
Market Snapshot
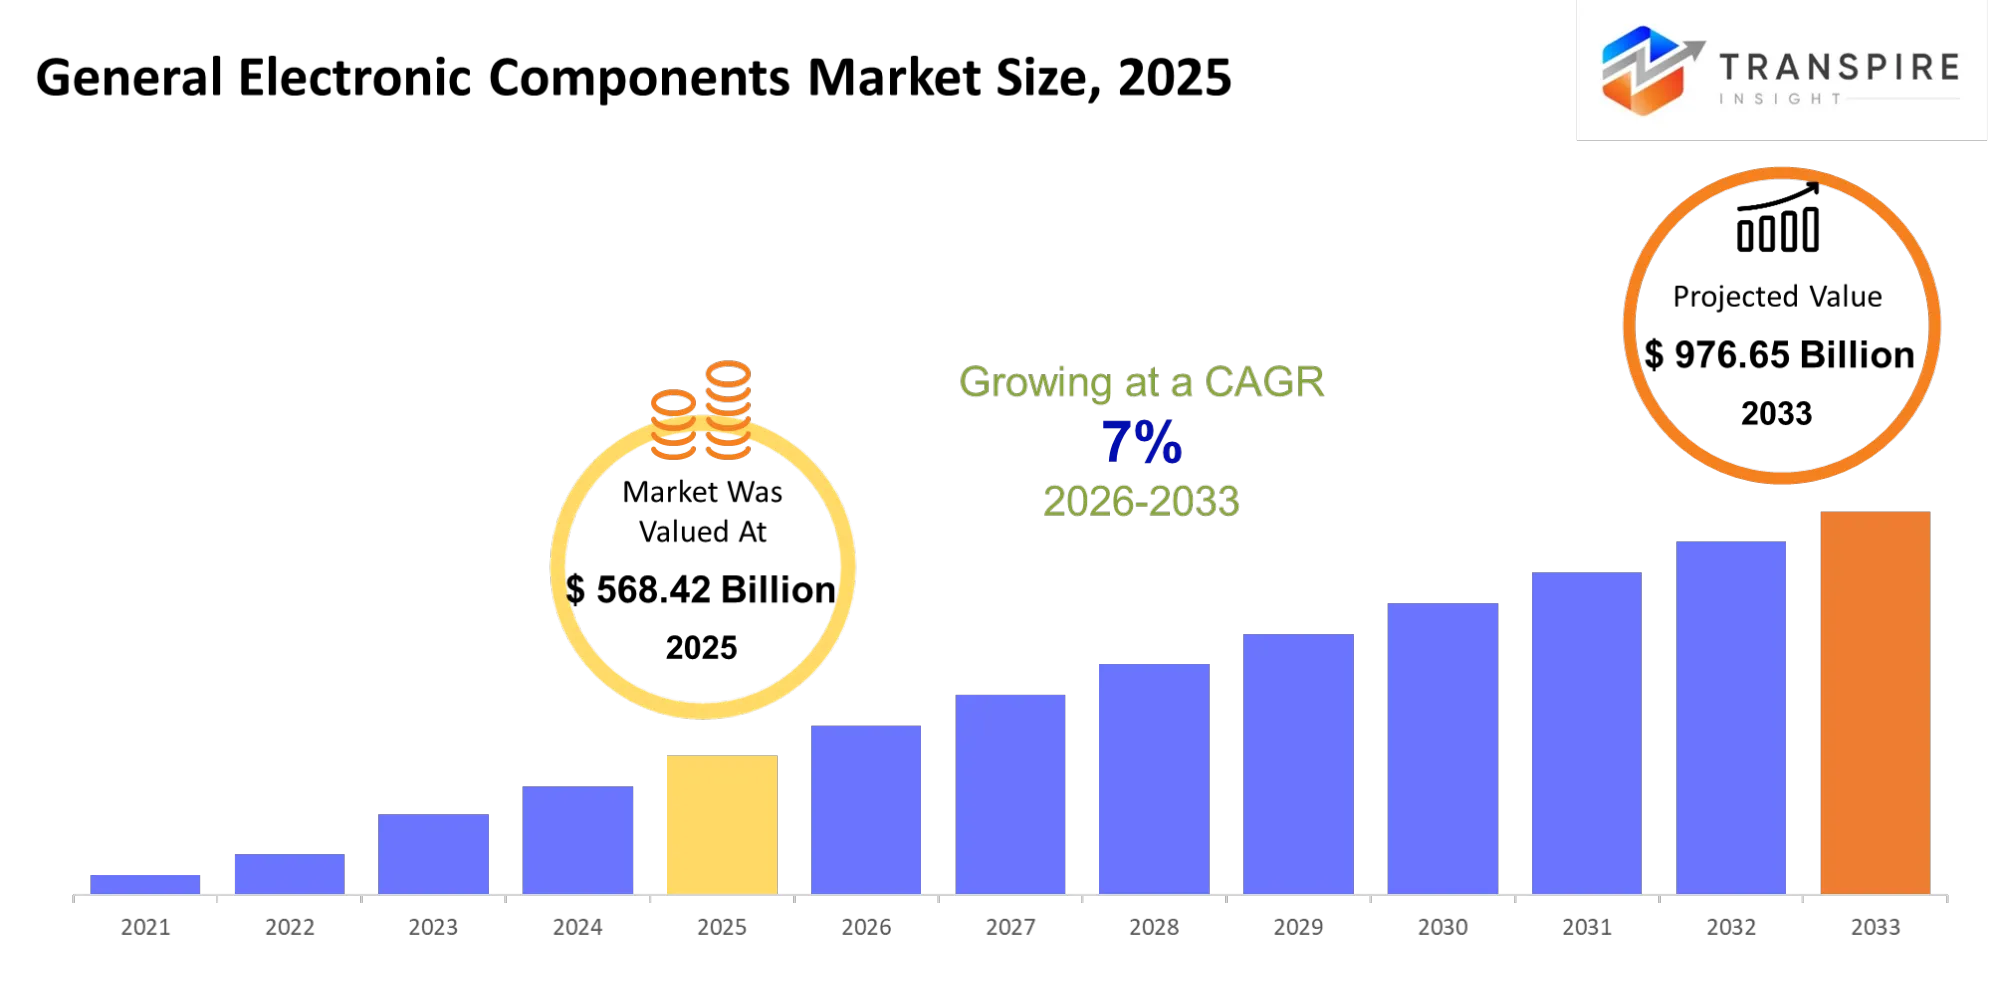
- Market Value (2025): USD 568.42 Billion.
- Expected Market Value (2026): USD 608.21 Billion.
- Estimated Market Value (2033): USD 976.65 Billion.
- Forecast CAGR (2026–2033): 7%.
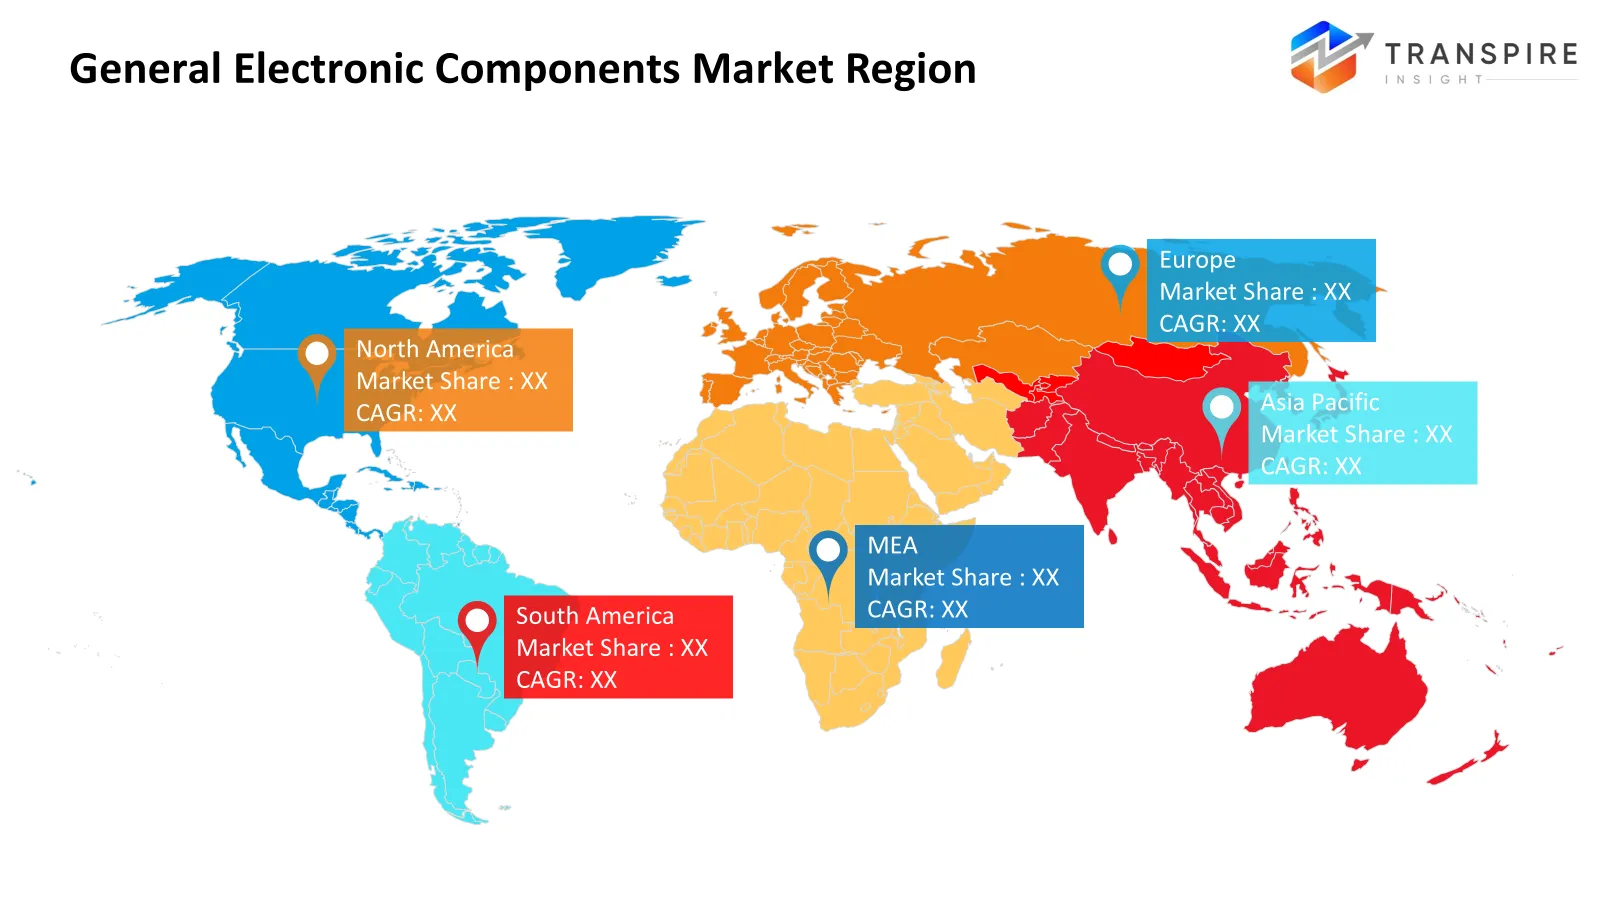
- Leading Region in 2025: Asia-Pacific.
- Second-largest Region: Europe.
- Fastest Growing Region: North America.
Introduction
General Electronic Components are fundamental building blocks used in electronic devices and systems, including passive components (resistors, capacitors, inductors), active components (diodes, transistors, integrated circuits), electromechanical components (connectors, relays, switches), sensors, and power management devices. These components enable signal processing, power distribution, communication, automation, and control across a wide range of industries, including consumer electronics, automotive, industrial automation, telecommunications, aerospace & defense, healthcare, and renewable energy. The General Electronic Components Market is driven by rapid digital transformation, increasing semiconductor integration, growing demand for smart electronic devices, expansion of electric vehicles (EVs), industrial automation, IoT adoption, and continuous technological advancements in miniaturization and high-performance electronic systems.
- For Instance:- Asia Pacific, Market Outlook: Asia Pacific is expected to remain the largest regional market for General Electronic Components, supported by extensive electronics manufacturing ecosystems in China, Japan, South Korea, Taiwan, and India. The regional market is projected to surpass USD 420 billion during the forecast period, driven by expanding semiconductor fabrication, consumer electronics production, and automotive electronics manufacturing.
- Europe, Sustainability & Innovation: Electronic component manufacturers across Europe are investing heavily in energy-efficient manufacturing, recyclable materials, lead-free components, advanced semiconductor packaging, AI-enabled quality inspection, and carbon-neutral production facilities to comply with environmental regulations while enhancing product performance and supply chain resilience.
Market Highlights:-
- Asia Pacific is expected to grow at a rapid CAGR in the General Electronic Components Market, holding approximately 46% of the market share during the forecast period.
- North America is anticipated to be the fastest-growing region, accounting for approximately 25% of the market due to increasing investments in semiconductor manufacturing, AI infrastructure, aerospace electronics, and electric vehicle technologies.
- Europe is projected to hold approximately 22% share of the General Electronic Components Market over the forecast period.
- By component Type, the Passive Components segment dominated the market, accounting for approximately 41% share in 2025 and is projected to expand at a substantial CAGR during the forecast period.
- By Application, the Consumer Electronics segment dominated the market and accounted for approximately 39% share in 2025 and is expected to maintain strong growth throughout the forecast period.
- By End User, the Electronics Manufacturing Companies (EMS & OEMs) segment dominated the market with approximately 37% share in 2025 and is projected to witness significant growth during the forecast period.
- Government Semiconductor Initiatives: Governments worldwide are supporting domestic electronics manufacturing through semiconductor incentive programs, localization initiatives, advanced manufacturing investments, and electronics production-linked incentive (PLI) schemes, encouraging large-scale production of electronic components and strengthening resilient supply chains.
How is Technology Driving Growth in the General Electronic Components Market?
The General Electronic Components Market is experiencing significant growth due to rapid technological advancements in semiconductor fabrication, miniaturization, automation, and advanced manufacturing processes. Manufacturers are increasingly adopting AI-powered production monitoring, robotics, precision surface-mount technology (SMT), Industry 4.0 solutions, digital twins, and automated optical inspection systems to improve manufacturing efficiency, reduce defects, and enhance product reliability. Furthermore, innovations in high-density packaging, advanced materials, wide-bandgap semiconductors, flexible electronics, and low-power component technologies are enabling the development of next-generation consumer electronics, electric vehicles, industrial automation systems, telecommunications infrastructure, and medical devices. Continuous investments in R&D and smart manufacturing are further accelerating market expansion worldwide.
Market Drivers
Growing Demand from Consumer Electronics, Automotive & Industrial Automation.The General Electronic Components Market is primarily driven by the increasing production of smartphones, laptops, wearable devices, electric vehicles, industrial automation equipment, telecommunications infrastructure, medical electronics, and smart home technologies. Rising adoption of AI, IoT, 5G connectivity, cloud computing, renewable energy systems, and autonomous vehicles is significantly increasing demand for advanced electronic components with higher efficiency, improved reliability, and compact form factors. Additionally, continuous investments in semiconductor manufacturing, PCB assembly technologies, and electronics supply chain expansion are supporting sustained market growth.
- For Instance:- India, the Production Linked Incentive (PLI) Scheme for Large Scale Electronics Manufacturing and the India Semiconductor Mission are encouraging investments in semiconductor fabrication, electronic component manufacturing, and domestic electronics production, strengthening India's role in the electronics supply chain.
Restrain
The primary challenge for the General Electronic Components Market is the volatility in semiconductor raw material prices, geopolitical trade uncertainties, and disruptions across supply chains. Additionally, increasing manufacturing costs, dependence on rare earth materials, stringent environmental regulations, rapid technological obsolescence.
Analysis of Prices and Consumer Behaviour
Consumer Electronics applications dominate the General Electronic Components Market, contributing approximately 39% of total revenue due to increasing production of smartphones, laptops, wearable devices, home appliances, gaming systems, and connected devices. High-performance electronic components designed for automotive, industrial automation, aerospace, and AI applications are typically priced 25–35% higher than conventional components due to their enhanced durability, precision, reliability, and advanced manufacturing technologies. Consumer electronics account for nearly 39% of total component consumption, followed by automotive electronics and industrial automation applications. Approximately 74% of market demand is generated by electronics manufacturing companies (OEMs and EMS providers). Buyer preferences indicate that nearly 70% of customers prioritize high reliability, miniaturization, energy efficiency, supply chain stability, and compliance with international quality standards, while growing investments in smart technologies, electric mobility, AI infrastructure, and digital transformation continue to drive long-term expansion of the General Electronic Components Market.
Top Companies in the General Electronic Components Market
- Murata Manufacturing
- TDK Corporation
- Yageo
- TE Connectivity
- Amphenol
- Vishay Intertechnology
- Infineon Technologies
- STMicroelectronics
- NXP Semiconductors
- Samsung Electro-Mechanics
- AVX Corporation
- Littelfuse
- Kyocera AVX
- Molex
- Panasonic Industry
Market Segmentation
The General Electronic Components Market share is divided into five categories: Product Type, Application, End User, Packaging Type, and Distribution Channel.
The Passive Components segment dominated the market, accounting for approximately 34% in 2025, and is expected to grow at a significant CAGR during the forecast period.
The General Electronic Components Market is segmented by product type into Passive Components, Active Components, Electromechanical Components, Printed Circuit Boards (PCBs), Connectors, Sensors, Power Components, and Others. Among these, the Passive Components segment dominated the market, accounting for approximately 34% in 2025 and is expected to expand at a significant CAGR during the forecast period. The segment's leadership is attributed to the widespread use of capacitors, resistors, and inductors across consumer electronics, automotive systems, industrial equipment, telecommunications infrastructure, and medical devices. Their cost-effectiveness, high reliability, miniaturization capabilities, and essential role in virtually every electronic circuit continue to drive strong demand.
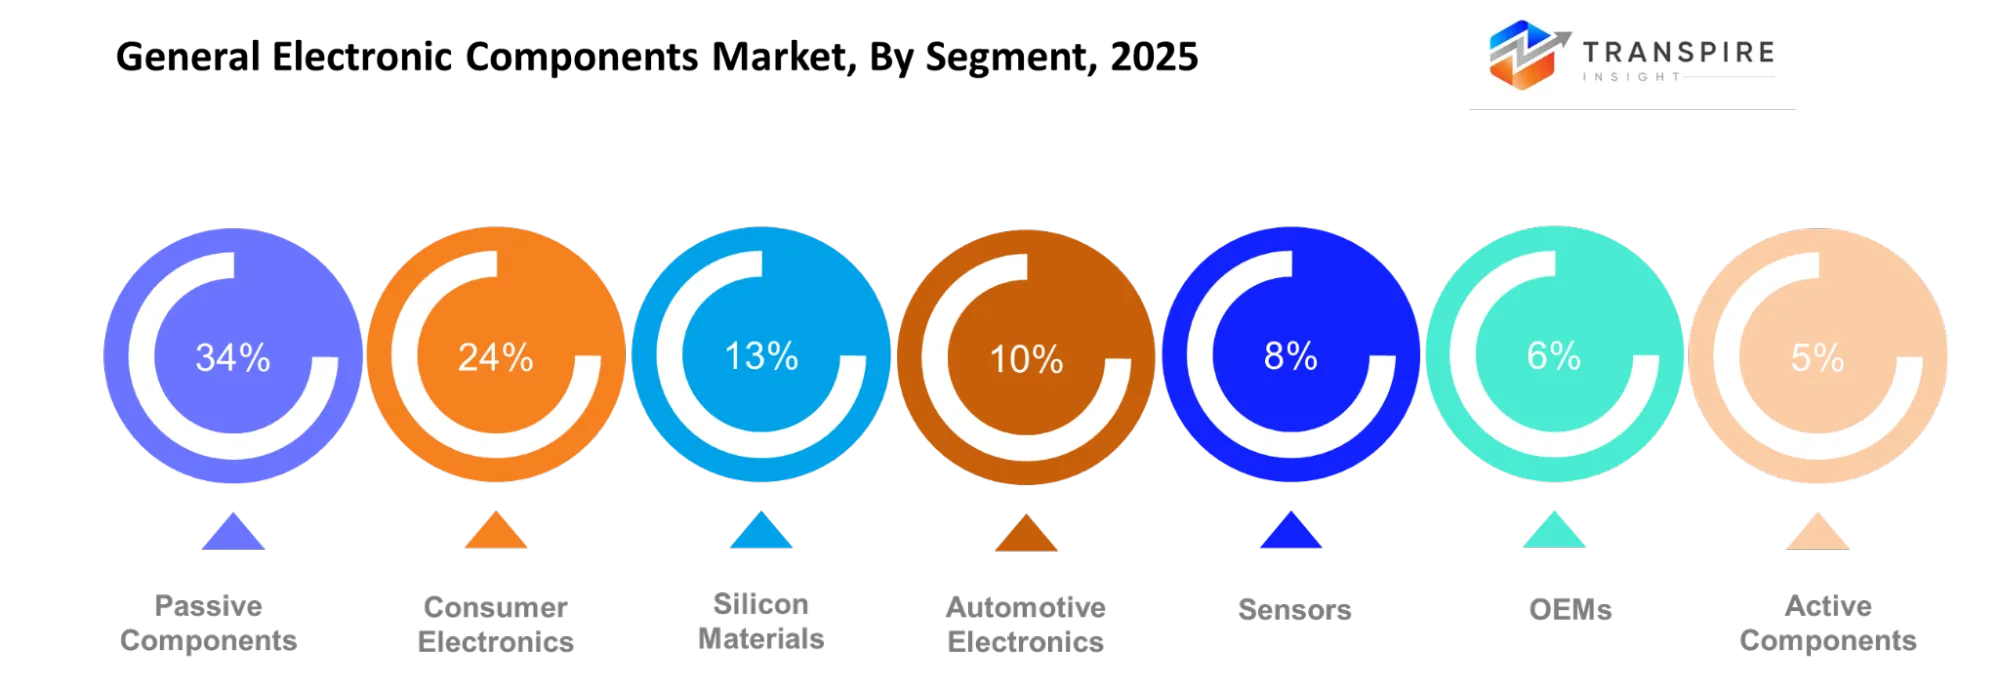
The Consumer Electronics segment held the largest share of approximately 39% in 2025 and is expected to grow at a substantial CAGR over the forecast period.
The General Electronic Components Market is segmented by application into Consumer Electronics, Automotive Electronics, Industrial Automation, Telecommunications, Healthcare & Medical Devices, Aerospace & Defense, Energy & Power, and Others. Among these, the Consumer Electronics segment accounted for approximately 39% of the market in 2025 and is projected to witness substantial CAGR growth during the forecast period. Increasing production of smartphones, laptops, tablets, wearable devices, gaming consoles, smart TVs, home appliances, and IoT-enabled products continues to generate significant demand for advanced electronic components. Continuous product innovation, shorter replacement cycles, and growing adoption of smart connected devices are further accelerating segment growth.
The Electronics Manufacturing Companies (OEMs & EMS Providers) segment held the largest share of approximately 37% in 2025 and is expected to grow at a high CAGR over the forecast period.
The General Electronic Components Market is segmented by end user into Electronics Manufacturing Companies (OEMs & EMS Providers), Automotive Manufacturers, Industrial Equipment Manufacturers, Telecommunications Companies, Healthcare Device Manufacturers, Aerospace & Defense Companies, Energy & Utility Companies, and Others. Among these, the Electronics Manufacturing Companies (OEMs & EMS Providers) segment held approximately 37% market share in 2025 and is expected to register a considerable CAGR throughout the forecast period. The segment's dominance is supported by increasing electronics production, contract manufacturing expansion, high-volume component procurement, automation in manufacturing facilities, and continuous investments in advanced production technologies to meet rising demand.
Regional Segment Analysis of the General Electronic Components Market
- North America (U.S., Canada, Mexico)
- Europe (Germany, France, U.K., Italy, Spain, Rest of Europe)
- Asia-Pacific (China, Japan, India, South Korea, Taiwan, Rest of APAC)
- South America (Brazil, Argentina, Rest of South America)
- Middle East & Africa (UAE, Saudi Arabia, South Africa, Rest of MEA)
Asia Pacific is expected to grow at a rapid CAGR in the General Electronic Components Market by holding approximately 46% of the market share during the forecast period.
Asia Pacific dominates the General Electronic Components Market due to its strong electronics manufacturing ecosystem, extensive semiconductor fabrication capacity, and leadership in consumer electronics production. China, Japan, South Korea, Taiwan, and India continue to invest heavily in semiconductor manufacturing, printed circuit board production, electric vehicles, industrial automation, and telecommunications infrastructure. Growing government support for domestic electronics manufacturing, increasing investments in AI, IoT, and 5G technologies, along with expanding export capabilities, continue to strengthen the region's leadership.
North America is the fastest-growing region in the General Electronic Components Market, holding approximately 25% market share.
North America is experiencing rapid market growth owing to significant investments in semiconductor manufacturing, artificial intelligence infrastructure, cloud computing, aerospace & defense electronics, electric vehicles, and next-generation communication technologies. Government initiatives supporting semiconductor localization, increasing R&D investments, and strong presence of leading technology companies continue to accelerate innovation and demand for advanced electronic components. The region also benefits from growing adoption of automation, industrial digitalization, and high-performance computing technologies.
Europe is anticipated to hold approximately 22% share of the General Electronic Components Market over the forecast period.
Europe maintains a strong position in the General Electronic Components Market due to its advanced automotive electronics industry, industrial automation leadership, renewable energy infrastructure, and precision manufacturing capabilities. Germany, France, Italy, and the United Kingdom continue investing in electric mobility, Industry 4.0, semiconductor research, and sustainable electronics manufacturing. Strict environmental regulations and increasing adoption of energy-efficient electronic systems further support long-term regional growth.
Strategies for Market Growth in Non-Leading Regions
Emerging economies can accelerate growth by strengthening domestic electronics manufacturing capabilities, encouraging semiconductor localization, expanding PCB assembly facilities, and supporting electronic component production through financial incentives and industrial policies. Strategic partnerships between component manufacturers, OEMs, research institutions, and government agencies can enhance technology transfer and manufacturing expertise. Investments in skilled workforce development, automation technologies, supply chain modernization, and digital manufacturing will improve competitiveness. Additionally, government-backed semiconductor incentive programs, export promotion initiatives, and foreign direct investment (FDI) policies will help establish resilient electronics ecosystems and reduce dependence on imports.
Future Market Trends for the General Electronic Components Market
1. Miniaturization and High-Density Electronic Components
Manufacturers are increasingly developing compact, lightweight, and high-performance electronic components for smartphones, wearable electronics, automotive systems, medical devices, and IoT applications. Advanced packaging technologies and miniaturized passive components are becoming key growth drivers.
2. AI, Electric Vehicles & Industrial Automation Expansion
Growing deployment of artificial intelligence, autonomous vehicles, robotics, industrial automation, and electric mobility is significantly increasing demand for advanced semiconductors, sensors, power modules, connectors, and intelligent electronic components capable of supporting high-performance applications.
3. Sustainable Electronics Manufacturing and Advanced Semiconductor Technologies
Manufacturers are investing heavily in environmentally sustainable manufacturing processes, lead-free electronic components, recyclable materials, energy-efficient production facilities, silicon carbide (SiC) and gallium nitride (GaN) technologies, and AI-enabled smart factories to improve operational efficiency while meeting environmental regulations.
Recent Developments
- In June 2026 – Murata Manufacturing Co., Ltd.: Expanded production capacity for multilayer ceramic capacitors (MLCCs) through investments in advanced automated manufacturing facilities to support growing demand from automotive electronics, AI servers, industrial automation, and next-generation consumer electronics.
- In November 2025 – TDK Corporation: Announced expansion of its advanced electronic component manufacturing capabilities, focusing on high-performance sensors, passive components, and power solutions for electric vehicles, renewable energy systems, industrial automation, and next-generation communication infrastructure, strengthening its supply chain and production capacity.
Market Segment
This study forecasts revenue at global, regional, and country levels from 2020 to 2033. Transpire Insights has segmented the General Electronic Components Market based on the below-mentioned segments:
General Electronic Components Market, Component Type
- Passive Components
- Active Components
- Electromechanical Components
- Printed Circuit Boards
- Sensors
- Connectors
- Power Components
- Others
General Electronic Components Market, By Material
- Ceramic
- Silicon
- Copper
- Aluminum
- Plastic
- Composite Materials
- Glass
- Others
General Electronic Components Market, By Application
- Consumer Electronics
- Automotive Electronics
- Industrial Equipment
- Telecommunications
- Medical Devices
- Aerospace & Defense
- Energy Systems
- Others
General Electronic Components Market, By Distribution Channel
- OEMs
- Electronic Distributors
- Online Sales
- Direct Sales
- Retail Electronics Stores
- Value-added Resellers
- Contract Manufacturers
- Others
General Electronic Components Market, By End User
- Consumer Electronics
- Automotive
- Industrial
- Healthcare
- Telecom
- Aerospace & Defense
- Energy & Utilities
- Others
General Electronic Components Market, By Regional Analysis
North America
- United States
- Canada
- Mexico
Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Rest of Europe
Asia Pacific
- Japan
- China
- Australia & New Zealand
- South Korea
- India
- Rest of Asia Pacific
South America
- Brazil
- Argentina
- Rest of South America
Middle East & Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Rest of the Middle East & Africa
Frequently Asked Questions
Find quick answers to common questions.
Rising demand for consumer electronics, electric vehicles (EVs), industrial automation, IoT devices, 5G infrastructure, AI technologies, and continuous advancements in semiconductor and electronic component manufacturing are driving the growth of the General Electronic Components Market.
Asia Pacific dominates the market due to its strong electronics manufacturing ecosystem, large-scale semiconductor production, expanding consumer electronics industry, increasing investments in electric vehicles, and supportive government initiatives for electronics manufacturing.
General Electronic Components provide reliable power management, signal processing, connectivity, circuit protection, sensing, and control functions, making them essential for consumer electronics, automotive systems, industrial automation, telecommunications, healthcare devices, and aerospace applications.
The Consumer Electronics segment leads the market, driven by increasing demand for smartphones, laptops, tablets, wearable devices, smart home products, gaming systems, and connected electronic devices.
Major companies include Murata Manufacturing Co., Ltd., TDK Corporation, Yageo Corporation, Vishay Intertechnology, Kyocera Corporation, TE Connectivity, Amphenol Corporation, ABB Ltd., Schneider Electric SE, and Molex LLC.
- Murata Manufacturing
- TDK Corporation
- Yageo
- TE Connectivity
- Amphenol
- Vishay Intertechnology
- Infineon Technologies
- STMicroelectronics
- NXP Semiconductors
- Samsung Electro-Mechanics
- AVX Corporation
- Littelfuse
- Kyocera AVX
- Molex
- Panasonic Industry
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Fiber Optic Faceplates Market
Fiber Optic Faceplates Market Size, Share & Analysis Report By Type (< 300 mm2, 300-350 mm2, and > 350 mm2, By Application (Night Vision, Holographic Imaging, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
High Temperature Superconductors Market
High Temperature Superconductors Market Size, Share & Analysis Report By Type (1G HTS, and 2G HTS), By Application (Power Cable, Fault Current Limiter, and Transformer), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Industrial Plugs and Socket Market
Industrial Plugs and Socket Market Size, Share & Analysis Report By Type (Industrial Plugs, Industrial Sockets), By Current (Up to 32 A, 32 to 125 A, Above 125 A), By Protection (Dustproof and Splash Proof, Waterproof, Explosion Proof), By End User (Heavy Industries, Oil and Gas, Chemicals and Pharmaceuticals, Power Generation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
InGaAs Avalanche Photodiodes Market
InGaAs Avalanche Photodiodes Market Size, Share & Analysis Report By Type (1100 - 1700 nm, and 1000 - 1600 nm), By Application (Missile Warning System, Muzzle Flash Detection, Wafer Defect Inspection, Laser Rangefinders, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031