
Asia Pacific Self-amplifying RNA (saRNA) Market Summary
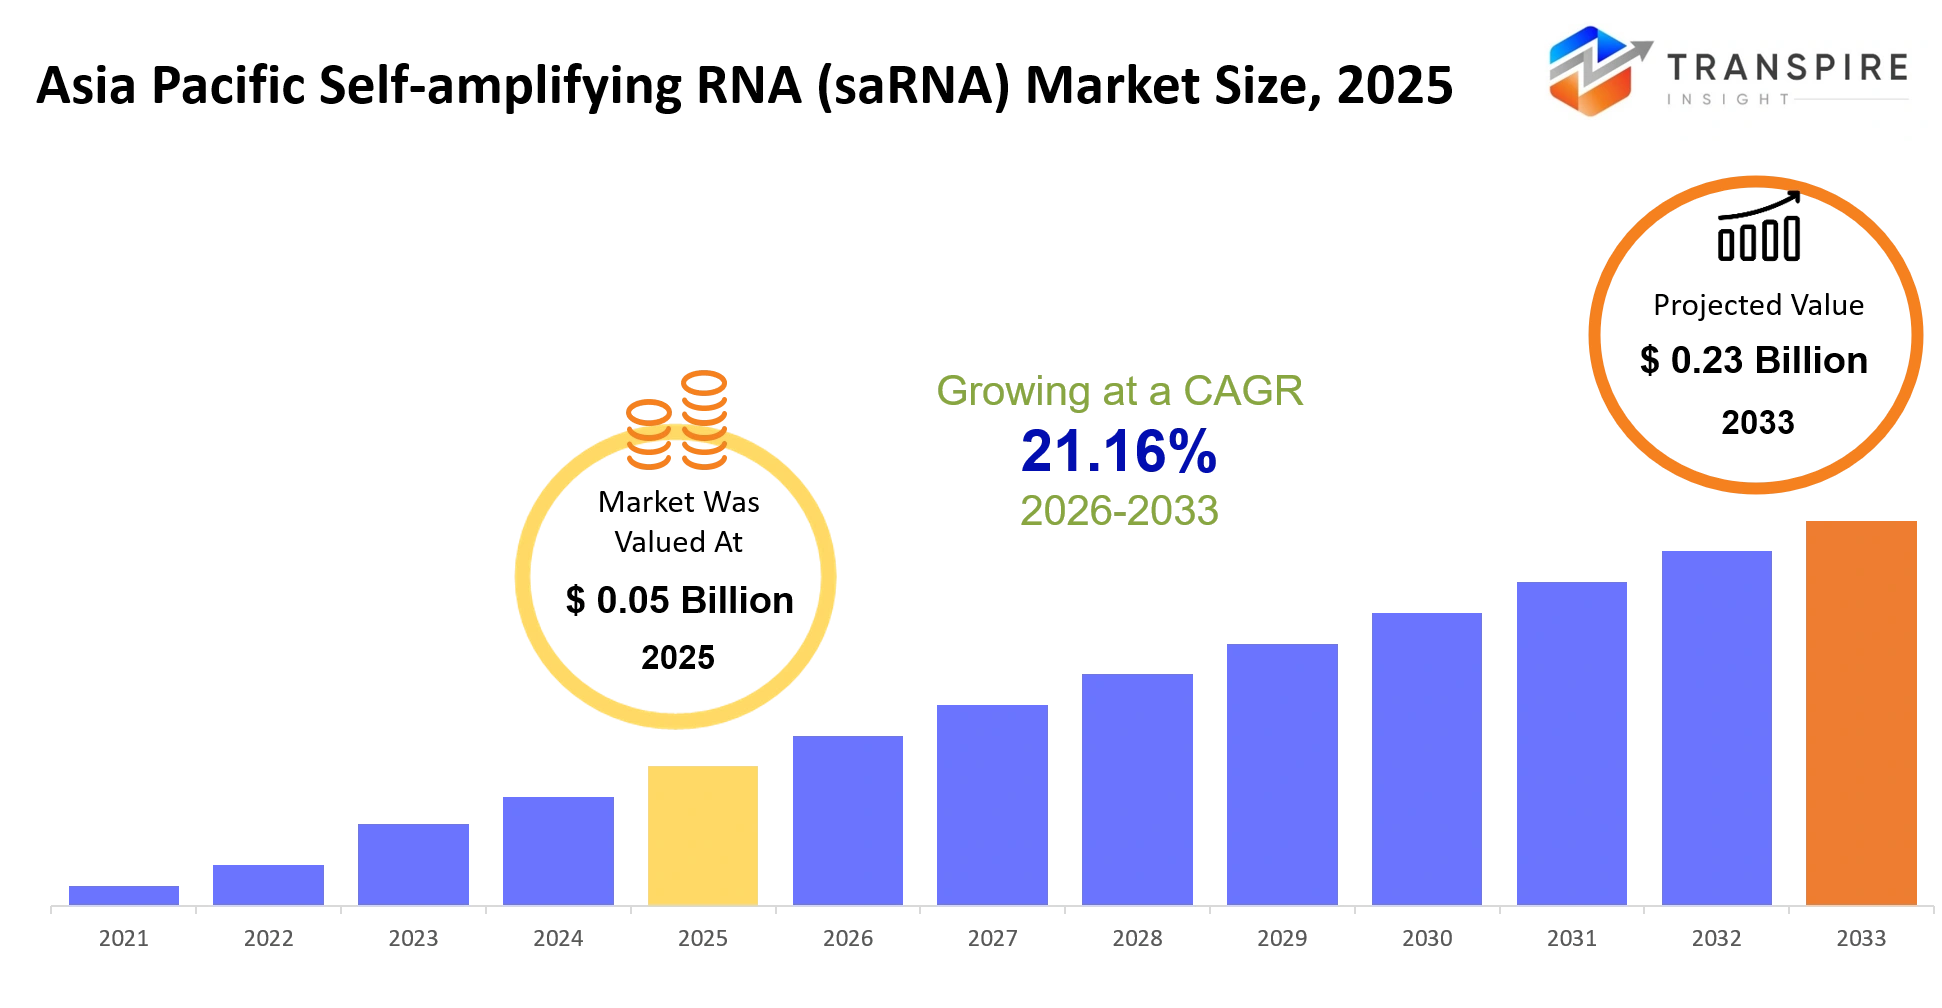
As per Transpire Insight Analysis the Asia Pacific Self-amplifying RNA (saRNA) Market size is estimated at USD 0.05 Billion in 2025 and is anticipated to reach USD 0.23 Billion by 2033, growing at a CAGR of 21.16% from 2026 to 2033.
The Asia Pacific Self-amplifying RNA (saRNA) Market helps drive next generation vaccines and therapeutics in a fairly direct way, because it can push stronger immune responses, using RNA doses that are often way lower than what conventional mRNA platforms typically need. For that reason, manufacturers tend to see improved production efficiency, they reduce manufacturing costs and they can move faster when it comes to emerging infectious diseases, cancer immunotherapies, and those uncommon genetic disorders across the region.
Over the last five years , the entire focus has kind of loosened, drifting away from pandemic only vaccine research into more diversified therapeutic pipelines that are backed not just by government biotech funding, but also by regional manufacturing expansion. The strong performance of mRNA vaccines during the COVID-19 pandemic really did boost attention toward saRNA technologies. That then encouraged pharmaceutical companies and research institutions to invest in local development know how. And as delivery systems like lipid nanoparticles keep getting better, while clinical validation keeps expanding, developers can proceed with broader product line ups while still leaning on lower production requirements. This builds stronger commercial potential , and it also supports more partnerships among biotech companies, academic organizations and contract manufacturing outfits.
Asia Pacific Self-amplifying RNA (saRNA) Market Size & Forecast:
- Asia Pacific Self-amplifying RNA (saRNA) Market Size 2025: USD 0.05 Billion
- Expected Market Value 2033: USD 0.23 Billion
- Forecast CAGR: 21.16%
- Leading region in 2025:
- Fastest Growing region:
- Key Profile: Arcturus Therapeutics, CSL Seqirus, GSK, Sanofi, Moderna, Pfizer, Replicate Bioscience, eTheRNA, BioNTech, CureVac, Imperial College London, Gennova Biopharmaceuticals, HDT Bio, Precision NanoSystems, TriLink BioTechnologies
Key Market Insights
- Asia Pacific Self-amplifying RNA (saRNA) market is sort of led by East Asia , and in 2025 it holds around 47% market share, this is mainly pushed by bigger biotechnology investments and vaccine manufacturing capacity.
- South Asia meanwhile is expected to show the fastest growth all the way through 2033 , backed by expanding clinical research, contract manufacturing, and government-led biotechnology initiatives, kind of a compounding effect over time.
- On the product side, saRNA Vaccines basically dominate the landscape with close to 58% market share in 2025, supported by infectious disease priorities, plus pandemic readiness programs.
- saRNA Therapeutics sits next as the second-largest segment at roughly 22%, with momentum from oncology efforts and rare disease pipeline expansion.
- For delivery, Lipid Nanoparticle (LNP)-based systems are forecast to grow the quickest through 2033 , as developers keep improving intracellular delivery efficiency and stability.
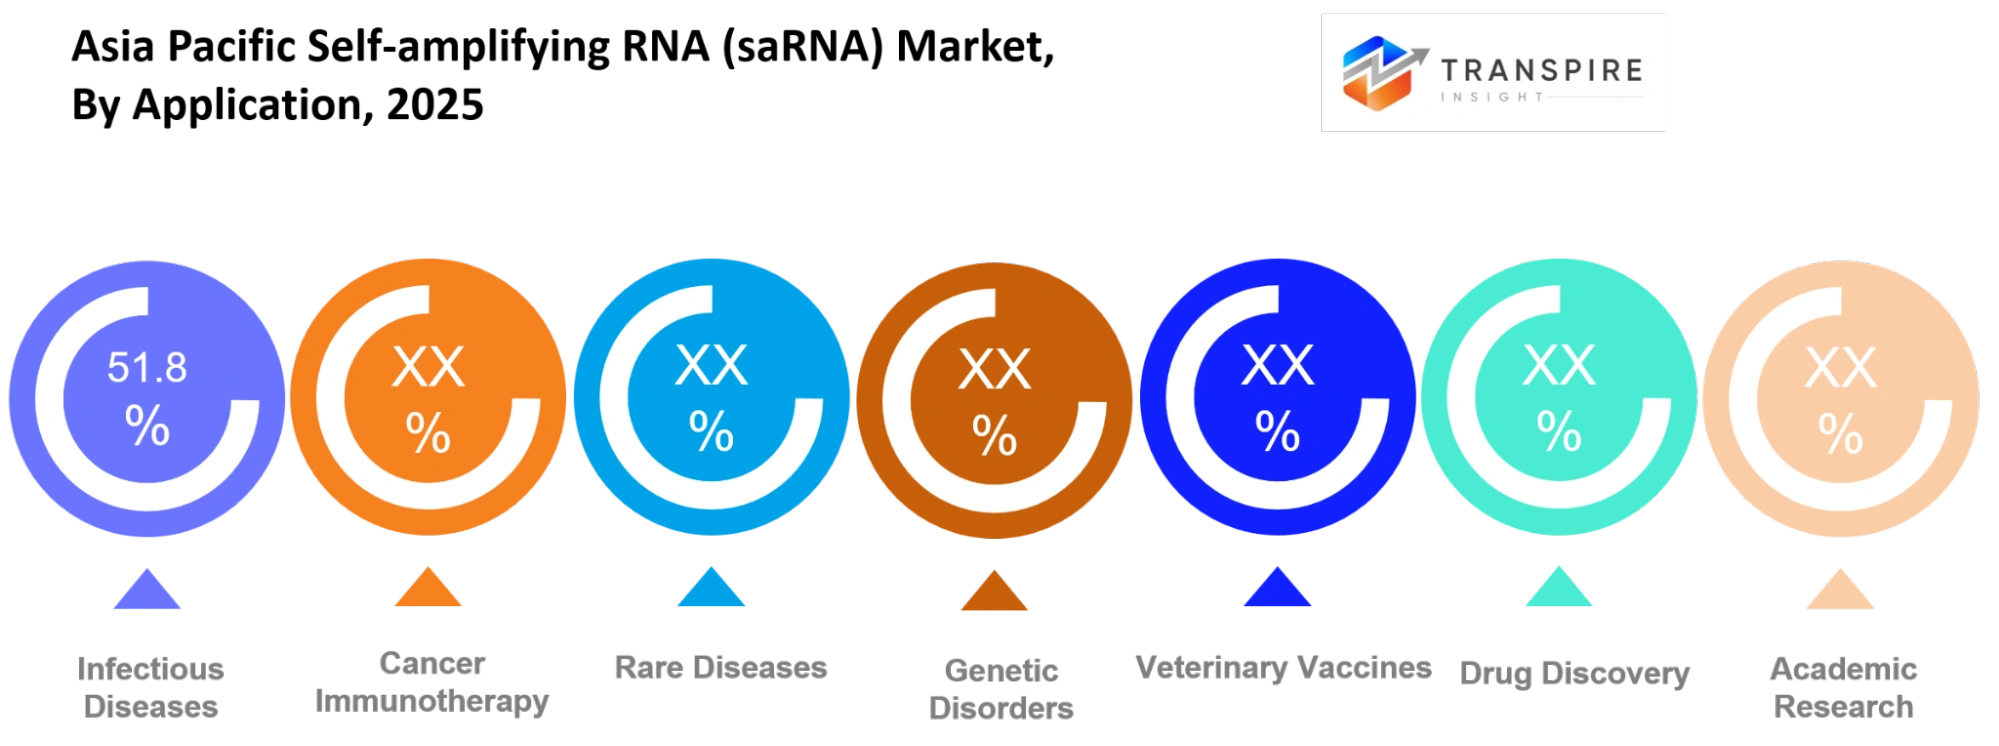
- When you look at applications, Infectious disease use cases contribute nearly 46% of total market revenue , while oncology programs keep expanding their clinical-stage investments across the Asia Pacific region.
- For demand, academic and research institutes make up roughly 41% of end user activity, and in the same time biotechnology companies are starting to show up as the fastest-growing commercial users throughout the forecast period.
- Players such as Arcturus Therapeutics , Moderna, Pfizer , BioNTech, GSK, and CSL Seqirus keep strengthening their competitive position through strategic alliances, RNA platform innovation, and programs that are tailored to specific regions in clinical settings.
- Finally, tech partnerships are trending more and more toward scalable GMP manufacturing, improved RNA synthesis platforms, and next generation lipid nanoparticle formulations , so getting to commercialization becomes easier, quicker, and more repeatable.
What are the Key Drivers, Restraints, and Opportunities in the Asia Pacific Self-amplifying RNA (saRNA) Market?
The most forceful growth driver is basically the move toward next-generation RNA therapeutics, able to deliver similar biological activity but with way lower RNA doses than the usual conventional mRNA approaches. This change has been sped up by government funding initiatives that showed up after the COVID-19 pandemic, and also by pharmaceutical companies looking for more efficient manufacturing platforms. When material needs go down, production costs drop , manufacturing scales better, and developers can broaden both vaccine and treatment pipelines across infectious diseases, oncology, and rare genetic disorders. As a consequence, licensing deals have grown, collaborative research is more frequent, and investment keeps flowing into regional production facilities.
Still, the biggest structural hurdle is the complicated clinical proof work and the large-scale manufacturing side. Self-amplifying RNA needs advanced delivery systems, specialized manufacturing infrastructure, and also a lot of regulatory review before it can be sold. All of that stretches the development calendar, raises capital spending, and can become a serious technical obstacle for smaller biotechnology companies. On top of that, limited GMP capacity across several Asia Pacific countries also postpones product launches, and it tends to suppress near-term commercial revenue.
Looking ahead, the strongest long-term opening seems to be personalized cancer immunotherapy paired with an expansion of regional vaccine manufacturing. Nations such as India, Singapore, South Korea, and Australia keep putting money into advanced biotechnology infrastructure, while newer lipid nanoparticle techniques make broader therapeutic uses more realistic.
What Has the Impact of Artificial Intelligence Been on the Asia Pacific Self-amplifying RNA (saRNA) Market?
Artificial intelligence is currently reshaping self-amplifying RNA research in a kind of self-boosting way, especially as it improves molecular design, formulation development, and even the clinical decisions made through the whole product lifecycle. Machine learning methods sift through RNA sequence stability, anticipate secondary structures, and juggle codon selection so protein expression goes up while the number of wet-lab tries goes down, it’s all pretty iterative but faster. AI also speeds lipid nanoparticle formulation by modeling particle makeup and delivery efficiency before anyone touches the benchtop, which shortens those early stage development stretches.
On top of that, advanced digital platforms enable semi-automated lab routines where robotic screening, high-throughput sequencing, and cloud based data analysis all get stitched together. This makes it possible for teams to test thousands of RNA candidates at once, which helps with pick-and-choose selection, and often reduces development expenses. Predictive analytics meanwhile supports manufacturers by estimating production quality, flagging process drift, and tuning GMP manufacturing performance, so outcomes stay steadier and operations run more smoothly. Clinical researchers also lean on AI to spot which patient cohorts fit best, forecast likely responses to therapy, and simplify trial architecture, overall increasing development throughput.
Still, despite all these improvements, broad AI use is not fully everywhere, mostly because biological datasets are fragmented, standardized clinical records aren’t always available, and it can be expensive to connect advanced computational infrastructure with biotechnology teams. Plus variability between experimental datasets tends to erode model accuracy, so labs must keep validating results continuously, before AI derived predictions can really be trusted for regulatory submissions or for commercial-scale product development.
Key Market Trends
- Pharmaceutical companies kind of shifted away from pandemic-only vaccine programs, and more into oncology and rare disease pipelines between 2022 and 2025, so commercial chances get a bit more diverse.
- Lipid nanoparticle technologies improved delivery efficiency by about 25–30% in multiple preclinical studies, which sort of backs wider therapeutic use.
- Across Japan, South Korea, India, and Australia, governments expanded biotechnology funding after 2021, aiming to bolster domestic RNA manufacturing capabilities.
- Also the contract development and manufacturing organizations (CDMOs) have been putting more money into regional RNA production, up over 20% since 2023, which should improve commercialization readiness in practice.
- Strategic collaborations among Moderna, BioNTech, Arcturus Therapeutics, Pfizer, and GSK have been focusing more and more on next-generation RNA platform work, plus regional clinical expansion, and not just near-term pipelines.
- AI-assisted RNA sequence optimization seems to have shortened early-stage candidate screening timelines, so researchers can test much bigger therapeutic libraries, faster.
- Academic research organizations are partnering more often with biotechnology companies, this is helping technology transfer move quicker from lab discovery to clinical development.
- Personalized cancer vaccine research has become a major investment priority, as precision medicine initiatives keep maturing through Asia Pacific healthcare systems.
- Regulatory agencies introduced clearer frameworks for advanced RNA therapeutics, this is encouraging earlier engagement between developers and health authorities.
- Finally manufacturing strategies increasingly emphasize scalable GMP facilities and regional supply chain resilience, just to reduce dependence on imported RNA production capabilities.
Asia Pacific Self-amplifying RNA (saRNA) Market Segmentation
By Product Type
The product landscape is basically split across saRNA Vaccines, saRNA Therapeutics, saRNA Research Reagents, saRNA Delivery Systems, saRNA Kits, Custom saRNA Products, GMP saRNA Products, and Others. saRNA Vaccines are still taking the biggest share, mostly because low-dose RNA tech helps efficient vaccine development for infectious diseases and also quick outbreak reaction. saRNA Therapeutics keeps growing too, especially in oncology and rare disease programs , as biotechnology companies push their clinical pipelines forward. Then there’s saRNA Research Reagents and saRNA Kits which cover laboratory experiments , target validation and early-stage development in both university labs and commercial research contexts.
Custom saRNA Products give tailored RNA constructs for more specialized study programs and preclinical studies, and they bring that extra experimental flexibility. GMP saRNA Products back clinical manufacturing , since they align with strict quality requirements needed for human trials and later commercial production. saRNA Delivery Systems remain important , because intracellular delivery success directly sways therapeutic outcomes and overall product effectiveness. The Others group covers specialized research materials and newer platform technologies, that tackle specific niche development needs across the biotechnology space.
By Application
Application areas like Infectious Diseases, Cancer Immunotherapy, Rare Diseases , Genetic Disorders , Veterinary Vaccines , Drug Discovery, Academic Research, and Others show up a lot. Infectious Diseases are still the leading slice , mainly because fast vaccine development along with scalable manufacturing really helps with preparedness against new or emerging pathogens. Cancer Immunotherapy keeps drawing investment too, especially now that personalized RNA therapies are moving into wider clinical assessment.
Rare Diseases and Genetic Disorders also add new chances, mostly via focused therapeutic development for ailments where options are limited . Veterinary Vaccines are getting more interest because animal health programs are adopting these advanced RNA technologies for livestock disease prevention. Drug Discovery benefits from faster target verification and more efficient screening during the early stages of pharmaceutical research.
Academic Research kind of keeps fueling everything through university labs and government funded biotechnology programs. And the “Others” part covers exploratory treatment initiatives and fresh RNA applications that keep growing as scientific progress continues, kind of steadily.
By Delivery Technology
Delivery technology includes Lipid Nanoparticles , Polymer-Based Delivery , Viral Vectors , Nanoemulsions , Liposomes , Electroporation , Hybrid Delivery Systems, and Others. Lipid Nanoparticles seem to lead this segment, mainly due to strong cellular uptake, better stability,and solid manufacturing workflows that already exist which helps in broad clinical development. Polymer-Based Delivery gives flexibility for controlled release, plus it fits specialized therapeutic formulations pretty well. Viral Vectors are still useful for selected research uses where high delivery efficiency is still the big deal.
Nanoemulsions along with Liposomes are kind of alternative routes, they help with formulation stability and biological distribution but only under certain therapeutic conditions. Electroporation supports lab and preclinical research by enabling direct nucleic acid delivery into target cells. Hybrid Delivery Systems mix several technologies so the delivery performance goes up, while also lowering some biological constraints. The Others bucket covers newer carrier platforms aimed at improving RNA protection, boosting targeting accuracy,and increasing overall therapeutic effectiveness.
By End User
End users usually include Biotechnology Companies, Pharmaceutical Companies, CROs, Academic Institutes, Government Research Organizations, Hospitals, Research Laboratories, and Others. Biotechnology Companies take the biggest share because active RNA platform development, product innovation, and clinical pipeline expansion basically need continuous research investment all the time. Pharmaceutical Companies also help with commercialization via large scale manufacturing capabilities, plus global development partnerships. CROs make it easier for biotechnology developers by supporting preclinical studies, clinical trials, and regulatory documentation.
Academic Institutes together with Government Research Organizations contribute in more fundamental ways, like basic research, technology development, and publicly funded innovation programs. Hospitals join in clinical evaluation and translational medicine projects where lab discoveries get connected with patient treatment, somehow. Research Laboratories handle formulation studies, analytical testing, and biological validation throughout the entire product development cycle. The Others segment is more mixed, it includes nonprofit organizations and specialized research centers that back cooperative biotechnology initiatives
By Development Stage
The development stages i nclude Preclinical Research, Phase I Trials , Phase II Trials, Phase III Trials, Commercial Manufacturing, Technology Platforms, Translational Research, and Others. Preclinical Research is often the biggest chunk because thorough lab validation really has to come first, to show safety, biological behavior, and delivery efficiency before any clinical check. Phase I Trials focus on the very first safety picture, though not much else, while Phase II Trials start producing more solid clues about therapeutic impact and dosing style. Phase III Trials then work to get the more promising candidates ready for regulatory review , using broader patient studies.
Commercial Manufacturing tends to grow as successful products head toward market entry, with more standardized output and quality assurance frameworks. Technology Platforms help multiple therapeutic candidates move forward, thanks to reusable RNA design and manufacturing know how, kind of a shared foundation. Translational Research acts like a connector between bench discoveries and real clinical use, by raising treatment readiness and product fine tuning. The Others segment covers more exploratory development efforts, which basically back future RNA technologies, plus some specialized therapeutic concepts.
What are the Key Use Cases Driving the Asia Pacific Self-amplifying RNA (saRNA) Market?
The biggest use case is sort of vaccine development for infectious diseases, where self-amplifying RNA technology helps produce stronger immune responses with lower RNA doses, and manufacturing stays more efficient overall, or at least that’s the intent. At the same time national immunization programs, pandemic preparedness initiatives, and regional vaccine production facilities keep backing adoption, across public health systems as well as biotechnology manufacturers.
Cancer immunotherapy and drug discovery are also getting more attention, because biotechnology companies and pharmaceutical companies are pushing personalized treatments and screening novel therapeutic targets. Meanwhile academic institutes and contract research organizations are leaning in too, applying self-amplifying RNA platforms for translational work, preclinical validation, and early-stage clinical development, too.
There are emerging use cases like personalized cancer vaccines, rare genetic disorder therapies, and veterinary vaccine development that are starting to show momentum. Progress in lipid nanoparticle delivery, artificial intelligence-assisted RNA sequence design, and regional GMP manufacturing infrastructure will likely make broader commercial adoption easier as clinical evidence keeps building and regulatory pathways continue to mature through Asia Pacific.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 0.05 Billion |
|
Market size value in 2026 |
USD 0.06 Billion |
|
Revenue forecast in 2033 |
USD 0.23 Billion |
|
Growth rate |
CAGR of 21.16% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United States; Canada; Mexico; United Kingdom; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; United Arab Emirates |
|
Key company profiled |
Arcturus Therapeutics, CSL Seqirus, GSK, Sanofi, Moderna, Pfizer, Replicate Bioscience, eTheRNA, BioNTech, CureVac, Imperial College London, Gennova Biopharmaceuticals, HDT Bio, Precision NanoSystems, TriLink BioTechnologies. |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (saRNA Vaccines, saRNA Therapeutics, saRNA Research Reagents, saRNA Delivery Systems, saRNA Kits, Custom saRNA Products, GMP saRNA Products, Others); By Application (Infectious Diseases, Cancer Immunotherapy, Rare Diseases, Genetic Disorders, Veterinary Vaccines, Drug Discovery, Academic Research, Others); By Delivery Technology (Lipid Nanoparticles, Polymer-Based Delivery, Viral Vectors, Nanoemulsions, Liposomes, Electroporation, Hybrid Delivery Systems, Others); By End User (Biotechnology Companies, Pharmaceutical Companies, CROs, Academic Institutes, Government Research Organizations, Hospitals, Research Laboratories, Others); By Development Stage (Preclinical Research, Phase I Trials, Phase II Trials, Phase III Trials, Commercial Manufacturing, Technology Platforms, Translational Research, Others). |
Which Regions are Driving the Asia Pacific Self-amplifying RNA (saRNA) Market Growth?
East Asia pretty much ends up holding the biggest chunk of the regional market, basically because there’s advanced biotechnology infrastructure already there, plus established pharmaceutical manufacturing , and a lot of strong public investment in RNA research. Japan is leading the commercialization side through early regulatory acceptance of self-amplifying RNA vaccines, while South Korea and China keep pushing ahead with clinical research and big-scale biopharmaceutical production. Government funding programs, seasoned contract manufacturing organizations, and a close, almost day-to-day style collaboration between universities and industry all help keep a steady innovation ecosystem. On top of that, strong intellectual property protection, along with mature regulatory frameworks , makes it easier for biotechnology companies to push their clinical pipelines forward and to justify manufacturing investments.
Oceania sits as the second-largest regional contributor, mainly due to consistent research funding and regulatory processes that are transparent, along with internationally recognized clinical trial capabilities, not just manufacturing scale alone. Australia continues pulling in biotechnology partnerships, largely thanks to advanced medical research institutions and fairly efficient pathways for early-stage clinical development. There’s also solid collaboration between academic organizations, biotechnology firms, and healthcare providers, which keeps therapeutic innovation moving. Stable healthcare investment and predictable regulatory oversight make the region a dependable contributor to regional revenue, and also to longer-term product development.
South Asia is projected to show the quickest growth through 2033, as biotechnology manufacturing capacity expands across India and nearby economies. More recently there have been investments in GMP manufacturing facilities, vaccine production infrastructure, and genomic medicine programs, and those have really sped up commercialization opportunities .
Who are the Key Players in the Asia Pacific Self-amplifying RNA (saRNA) Market and How Do They Compete?
Competition still looks moderately concentrated , mainly because making RNA commercialization work really depends on specialized engineering know-how, pretty advanced delivery methods, and also a lot of money for clinical development, so it’s not something everyone can just pick up overnight. In general, technology innovation is the main competitive driver, then later it’s manufacturing capability, regulatory experience , and strategic collaborations that quietly decide who gets the better long term positioning in the market. Established pharma companies keep adding to their portfolios by pairing up with specialized RNA developers, while biotech newcomers tend to bet more on distinctive delivery platforms and the next generation therapeutic candidates, you know, the ones that are slightly more advanced or more targeted.
Arcturus Therapeutics stands out via its proprietary STARR® self-amplifying RNA platform plus low-dose vaccine technology. Its collaboration with CSL Seqirus helps broaden commercial reach by mixing innovative RNA know how with large scale vaccine manufacturing and distribution capabilities worldwide . Meanwhile, Gennova Biopharmaceuticals keeps leaning into regional manufacturing expansion , and localized RNA platform development, which then reinforces its access to Asian biotechnology markets through domestic production , not just exporting.
Moderna and BioNTech, meanwhile, build on deep messenger RNA development experience, which lets them push advanced RNA platform innovation faster and expand therapeutic pipelines beyond infectious diseases. CureVac puts its emphasis on optimized RNA engineering and formulation technologies , aiming to improve stability and make manufacturing more efficient overall.
Company List
- Arcturus Therapeutics
- CSL Seqirus
- GSK
- Sanofi
- Moderna
- Pfizer
- Replicate Bioscience
- eTheRNA
- BioNTech
- CureVac
- Imperial College London
- Gennova Biopharmaceuticals
- HDT Bio
- Precision NanoSystems
- TriLink BioTechnologies
Recent Development News
In March 2026, Arcturus Therapeutics announced 2025 financial results and confirmed continued advancement of its self-amplifying RNA pipeline, including Phase II progression of ARCT-032 and ongoing pandemic influenza vaccine development. The update reinforced confidence in commercialization plans and long-term investment in saRNA technologies.
Source: https://arcturustherapeuticsinc.gcs-web.com
What Strategic Insights Define the Future of the Asia Pacific Self-amplifying RNA (saRNA) Market?
The market is edging toward broader therapeutic commercialization, a bit like self-amplifying RNA platforms keep widening beyond infectious disease vaccines into oncology, genetic disorders, and also that personalized medicine direction. With ongoing improvements in lipid nanoparticle delivery, artificial intelligence assisted RNA design, and more regional manufacturing capacity, this kind of structural shift should keep progressing over the next five to seven years.
One less obvious risk though is the fact that specialized raw materials, and delivery technology suppliers, can end up concentrated, so manufacturing can bottleneck even when the clinical pipelines are expanding. Still, there’s a solid opening here, namely the rise of personalized cancer vaccines, which is being backed by precision medicine initiatives in Japan, South Korea, Singapore, and India. In those areas, biotechnology investment keeps building, and it helps the whole ecosystem move faster.
Market players should therefore focus on strategic partnerships that blend RNA platform expertise with scalable GMP manufacturing, and also regional clinical development know-how, so they can commercialize quicker while cutting down on both technical and regulatory risks that show up when companies expand independently.
Asia Pacific Self-amplifying RNA (saRNA) Market Report Segmentation
By Product Type
- saRNA Vaccines
- saRNA Therapeutics
- saRNA Research Reagents
- saRNA Delivery Systems
- saRNA Kits
- Custom saRNA Products
- GMP saRNA Products
- Others
By Application
- Infectious Diseases
- Cancer Immunotherapy
- Rare Diseases
- Genetic Disorders
- Veterinary Vaccines
- Drug Discovery
- Academic Research
- Others
By Delivery Technology
- Lipid Nanoparticles
- Polymer-Based Delivery
- Viral Vectors
- Nanoemulsions
- Liposomes
- Electroporation
- Hybrid Delivery Systems
- Others
By End User
- Biotechnology Companies
- Pharmaceutical Companies
- CROs
- Academic Institutes
- Government Research Organizations
- Hospitals
- Research Laboratories
- Others
By Development Stage
- Preclinical Research
- Phase I Trials
- Phase II Trials
- Phase III Trials
- Commercial Manufacturing
- Technology Platforms
- Translational Research
- Others
Frequently Asked Questions
Find quick answers to common questions.
The expected Asia Pacific Self-amplifying RNA (saRNA) Market size for the market will be USD 0.23 Billion in 2033.
Key segments for the Asia Pacific Self-amplifying RNA (saRNA) Market are By Product Type (saRNA Vaccines, saRNA Therapeutics, saRNA Research Reagents, saRNA Delivery Systems, saRNA Kits, Custom saRNA Products, GMP saRNA Products, Others); By Application (Infectious Diseases, Cancer Immunotherapy, Rare Diseases, Genetic Disorders, Veterinary Vaccines, Drug Discovery, Academic Research, Others); By Delivery Technology (Lipid Nanoparticles, Polymer-Based Delivery, Viral Vectors, Nanoemulsions, Liposomes, Electroporation, Hybrid Delivery Systems, Others); By End User (Biotechnology Companies, Pharmaceutical Companies, CROs, Academic Institutes, Government Research Organizations, Hospitals, Research Laboratories, Others); By Development Stage (Preclinical Research, Phase I Trials, Phase II Trials, Phase III Trials, Commercial Manufacturing, Technology Platforms, Translational Research, Others).
Major Asia Pacific Self-amplifying RNA (saRNA) Market players are Arcturus Therapeutics, CSL Seqirus, GSK, Sanofi, Moderna, Pfizer, Replicate Bioscience, eTheRNA, BioNTech, CureVac, Imperial College London, Gennova Biopharmaceuticals, HDT Bio, Precision NanoSystems, TriLink BioTechnologies.
The Asia Pacific Self-amplifying RNA (saRNA) Market size is USD 0.05 Billion in 2025.
The Asia Pacific Self-amplifying RNA (saRNA) Market CAGR is 21.16% from 2026 to 2033.
- Arcturus Therapeutics
- CSL Seqirus
- GSK
- Sanofi
- Moderna
- Pfizer
- Replicate Bioscience
- eTheRNA
- BioNTech
- CureVac
- Imperial College London
- Gennova Biopharmaceuticals
- HDT Bio
- Precision NanoSystems
- TriLink BioTechnologies
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Cord Blood Banking Services Market
Cord Blood Banking Services Market Size, Share & Analysis Report By Type of Service (Collection, Processing, Storage), By Bank Type (Private Banks, Public Banks, and Hybrid Banks), By Component (Cord Blood, and Cord Tissue), By End User (Hospitals, Research Institutions, Biotechnology Companies, and Others) and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
ELISA Processors Market
ELISA Processors Market Size, Share & Analysis Report By Type (Optical Filter ELISA Analyzer, and Optical Grating ELISA Analyzers), By Mode (Automated ELISA Analyzers, and Semi-Automated ELISA Analyzers), By Applications (Immunology, Vaccine development, Drug Monitoring, and Others), By End Users (Biotechnology Companies, Pharmaceutical Companies, Contract Research Organization, and Diagnostic Laboratories) and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
May 2026
Microscope Slide Scanner Market
Microscope Slide Scanner Market Size, Share & Analysis Report By Type (Portable Microscope Slide Scanner, and Desktop Microscope Slide Scanner), By Application (Biological Research, Medicine, Veterinary, and Other) and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Microwave Cookware Market
Microwave Cookware Market Size, Share & Analysis Report By Material Type (Plastic, Glass, Ceramic, Silicone, and Metal), By Application (Cooking, Reheating, and Defrosting), By End User (Household, Commercial (Restaurants, Hotels, and Cafes), and Food Service Industry), By Sales Channel (Online Retail, Offline Retail (Supermarkets, Hypermarkets, Specialty Stores), and Direct Sales (Company Outlets)) and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031