
Asia Pacific Eye Care Market Summary
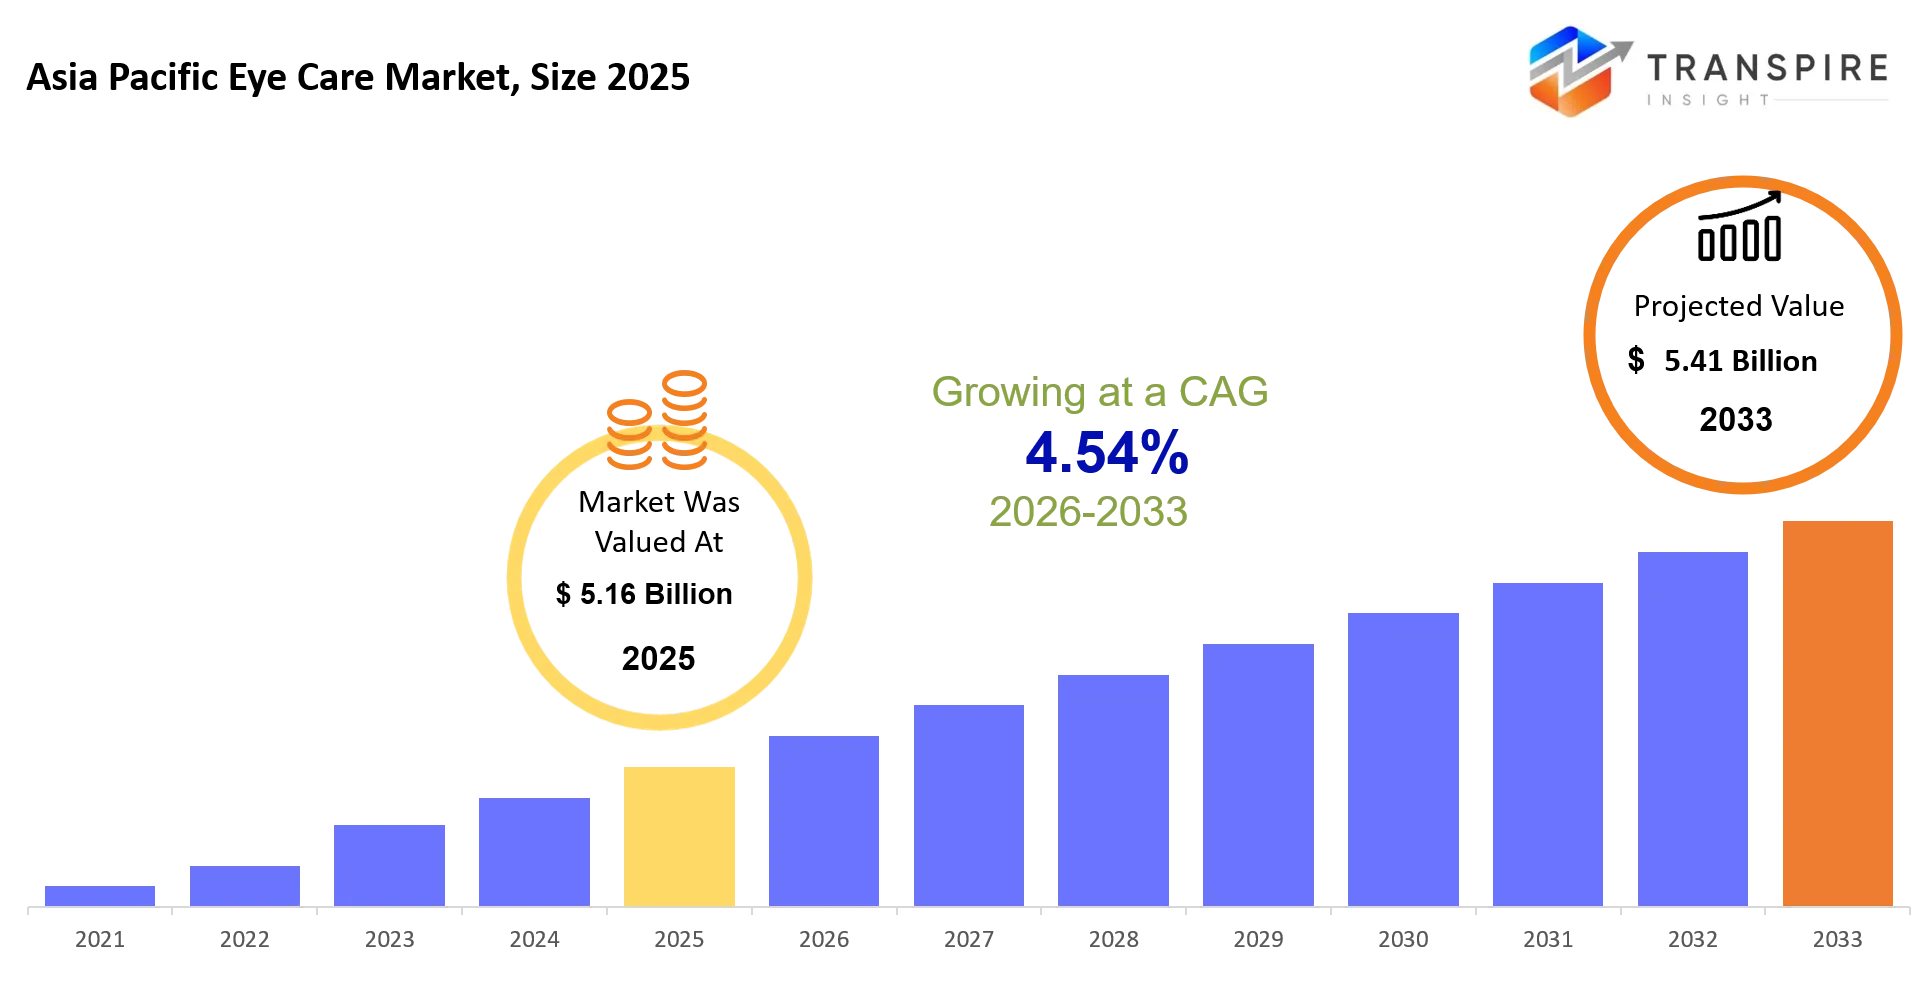
As per Transpire Insight Analysis the Asia Pacific Eye Care Market size is estimated at USD 5.16 Billion in 2025 and is anticipated to reach USD 5.41 Billion by 2033, growing at a CAGR of 4.54% from 2026 to 2033.
The Asia Pacific Eye Care Market kind of basically keeps vision health going by helping people with noticing, managing, and treating eye problems that mess up day to day routines, office productivity, and overall quality of life later on. It pulls together a mix of diagnostic tools, surgical equipment, contact lenses, ophthalmic medicines and also vision correction choices which are all used for different needs.These are used not only in hospitals, but also in special clinics, and even through optical retail channels, so yeah pretty wide reach.
Over the past five years, there’s been this kinda structural move toward integrated digital ophthalmology, and it has rearranged how care teams work in practice.With AI-assisted screening and some more detailed imaging, clinicians can often notice issues earlier and then sort out care in a more streamlined manner. And then, the COVID-19 pandemic, yeah, that was a big turning point, because it got in the way of the usual eye checkups, so there was a backlog of untreated cases , but at the same time it also helped teleconsultation grow faster and other digital care models. At the same time healthcare systems kept expanding their screening capacity, they poured money into upgraded ophthalmic infrastructure, and providers began using newer technologies. That resulted in better treatment efficiency, more patients being seen, and it also opened up stronger revenue paths across both public services and privately run eye care.
Asia Pacific Eye Care Market Size & Forecast:
- Asia Pacific Eye Care Market Size 2025: USD 5.16 Billion
- Expected Market Value 2033: USD 5.41 Billion
- Forecast CAGR: 4.54%
- Leading region in 2025: East Asia
- Fastest Growing region: South Asia
- Key Profile: Alcon, Johnson & Johnson Vision, Bausch + Lomb, Carl Zeiss Meditec, EssilorLuxottica, CooperVision, Hoya Corporation, Topcon, NIDEK, Roche, Novartis, AbbVie, Santen Pharmaceutical, Canon Medical Systems, Haag-Streit
Key Market Insights
- East Asia basically led the Asia Pacific Eye Care Market in 2025 with something like 46% share , you know, the usual drivers—better healthcare backbone, older populations, and a pretty steady push in ophthalmology equipment adoption.
- South Asia is also being forecast as the fastest moving regional market for 2025–2033, mainly because private hospitals are growing, insurance take-up is rising, and access to vision care services is getting broader.
- When you look at product types, ophthalmic pharmaceuticals were on top with close to 38% market share , helped by continuous treatment demand for glaucoma, dry eye disease and retinal disorders.
- Contact lenses stayed second in line, with premium silicone hydrogel products doing well, plus disposable lens adoption keeps expanding in many urban consumer circles.
- Diagnostic imaging systems are expected to show the quickest product growth through 2033 , largely due to AI-enabled retinal screening and optical coherence tomography upgrades that are being rolled out more often.
- For applications, vision correction still rules with around 42% share , which matches the ongoing need for refractive error management across hospitals, clinics, and optical retail networks.
- Retinal disease management should see the fastest application growth, because diabetic retinopathy screening programs are spreading across more Asia Pacific economies that are still developing.
- On the end user side, hospitals generated nearly 48% of revenue, helped along by integrated ophthalmic surgery capabilities and ongoing investments in advanced diagnostic infrastructure.
- Specialty eye clinics will likely keep growing quicker than the rest through 2033, probably because waiting times are shorter and procedural efficiency is starting to improve, a bit more each year, basically.
What are the Key Drivers, Restraints, and Opportunities in the Asia Pacific Eye Care Market?
The main force pushing market expansion is the fast rollout of digital ophthalmology, backed by national blindness prevention programs and also wider reimbursement for advanced eye care. Artificial intelligence assisted retinal imaging, optical coherence tomography, and minimally invasive surgical methods, made diagnosis faster and made the treatment plan more precise. When intervention happens earlier, procedure counts went up across hospitals and specialty clinics. At the same time healthcare providers updated their ophthalmic devices so patient flow became smoother. In practice these changes boosted equipment sales, lifted pharmaceutical demand, and kept recurring service income moving across the regional eye care business.
The largest structural roadblock is still uneven access to specialized ophthalmologists, plus advanced diagnostic infrastructure that tends to sit outside the major metropolitan areas. Growing specialist capacity takes years of clinical schooling and steady healthcare funding. On top of that, the high cost of buying equipment keeps smaller providers from adopting new technology. From a Transpire Insight look at regional procurement updates and launch timing, the supply chain staying concentrated is still the key execution problem. Component shortages and late import arrivals keep stretching equipment replacement cycles, which in turn slows down new installations and delays revenue generation across several developing markets.
A pretty big chance is likely to show up as AI enabled community eye screening gets expanded, especially when it's paired with cloud-linked diagnostic platforms. It feels like governments as well as private healthcare organizations are putting money into regional checkup initiatives for diabetic retinopathy and glaucoma. With portable imaging devices, specialist support can get pushed into underserved areas, without needing any sort of permanent hospital setup or an ongoing ward. Also, keep investing in teleophthalmology, premium intraocular lenses, and digital patient management platforms, because that should help push stronger procedural volumes and then create fresh, repeatable revenue streams across Asia Pacific during the next ten years.
What Has the Impact of Artificial Intelligence Been on the Asia Pacific Eye Care Market?
Artificial intelligence plus digital technologies are kind of pushing ophthalmic care into a new shape by making screening more accurate , speeding up day to day workflow , and helping with clinical decisions in a more consistent way. AI- assisted retinal image analysis will automatically spot diabetic retinopathy glaucoma, and age related macular degeneration from very high-resolution scans, so clinicians can focus on patients who really need urgent care first. At the same time digital scheduling systems, cloud based imaging archives, and automated reporting tools cut down on the admin burden , and they also help coordination between primary care teams and ophthalmologists feel smoother.
Then there is machine learning, which doesn’t just “analyze” in a simple sense—it can support patient demand forecasting, improve equipment utilization , and even project maintenance requirements for imaging systems. That means less surprise downtime and better asset performance over time. In general, these abilities help hospitals and specialty clinics push up the number of exams they can handle while lowering operating costs and keeping treatment more uniform across cases. Remote monitoring and teleophthalmology platforms also extend specialist services into underserved areas, which tends to improve earlier diagnosis, and it makes follow up care easier to actually complete.
Still, AI adoption is not totally straightforward, there are constraints. For example, integrating advanced software with older hospital information systems takes major capital , and it usually demands solid technical know how. Performance depends heavily on large, diverse clinical datasets, and if imaging quality varies a lot across rural facilities, algorithm accuracy can drop. So, tackling interoperability , cybersecurity, and standardized clinical validation is going to be crucial if this is going to roll out widely across the whole regional vision care network.
Key Market Trends
- After 2021, artificial intelligence-assisted retinal screening kinda took off more, and that meant faster diagnostic turnaround times. It also helped teams catch problems earlier, especially within diabetic retinopathy programs where earlier intervention matters a lot.
- Premium silicone hydrogel contact lenses got stronger momentum from 2022 through 2025. Part of it was just higher comfort expectations , and part of it was the growth of disposable lens portfolios , you know, more options showing up.
- Hospitals started swapping out older imaging gear for more advanced optical coherence tomography platforms. This shift improved diagnostic precision , and it also made surgical planning feel a bit more guided, overall.
- Teleophthalmology networks grew fast after the pandemic. So remote consultations became more normal, plus specialist referrals could reach underserved regional healthcare systems without so much friction.
- Carl Zeiss Meditec and Topcon Healthcare also pushed cloud connected imaging solutions harder. That moved the whole data integration story forward, and by 2023 it supported smoother remote clinical collaboration.
- National diabetic screening programs broadened across India, China, and Southeast Asia. As a result, retinal examination volumes increased, and clinics kept buying diagnostic equipment more steadily , not just in short bursts.
- Premium intraocular lens adoption rose too, mainly because cataract surgery providers emphasized better visual outcomes. They also talked about less reliance on corrective eyewear after surgery, which patients often prefer.
- Regional manufacturers leaned into stronger local production strategies following supply chain disruptions that hit during 2020–2022. This improved equipment availability , and it strengthened procurement resilience when shortages happened.
- Private specialty eye clinic networks expanded across South Asia between 2023 and 2025. That boosted procedural capacity , and it sped up the adoption of advanced ophthalmic technologies, piece by piece.
Asia Pacific Eye Care Market Segmentation
By Product Type :
Eyeglasses kind of held a strong position since correcting sight stayed like a basic healthcare must across all age groups, and it never really stopped being relevant. Contact lenses got more accepted through daily disposable and silicone hydrogel products, they felt easier on the eyes and also more convenient to use, sort of, in real day life. Intraocular lenses were also a steady helper for cataract surgery volumes because healthcare facilities kept opening more access to advanced surgical procedures. Ophthalmic drugs meanwhile kept steady sales thanks to long-term use for glaucoma , dry eye syndrome, infections, and retinal disorders, so the demand stayed consistent.
Eye care supplements carried on pulling in consumers who wanted nutritional backing for vision health. Diagnostic equipment showed strong progress as providers invested in optical coherence tomography systems, retinal imaging tools, and AI-assisted screening items that help with early detection. Beyond that, other products supported more specialized treatment needs across hospitals, specialty clinics, and even optical retail networks too. In the end, product diversity will keep backing broader clinical adoption, and it will also create long-term business opportunities, maybe more than people expect.
By Application :
Refractive errors were still the biggest application area, because corrective lenses along with routine eye examinations stayed necessary for both city and rural populations, more or less. Cataracts then drove a large amount of treatment work as surgical procedures kept rising, and this was enabled by newer healthcare infrastructure. Glaucoma therapy also grew, mainly because earlier detection became more practical thanks to advanced imaging tools, plus more organized screening programs. Dry eye syndrome kept causing steady demand, both for prescription medicines and for over the counter options too.
Retinal disorders got more clinical attention as well, since diabetes linked complications in the eyes mean people needed regular monitoring and quicker intervention when things show up. Eye infections also helped keep pharmaceutical sales steady, because there were antibacterial and antiviral treatment choices available. Other applications handled the less typical vision disorders, those that need specialized clinical management rather than basic follow up. Overall, wider disease detection combined with earlier treatment should keep improving how much patients use services in many healthcare settings, even when access varies a bit.
By Distribution Channel :
Hospitals stayed as the top distribution channel, mostly because advanced diagnostic gear , surgical facilities and specialist ophthalmologists all worked inside integrated healthcare settings. Optical stores kept their momentum too , with solid retail activity driven by prescription eyewear, contact lenses, and routine vision check services. Retail pharmacies made it easy for people to get ophthalmic medicines, lubricating eye drops, plus nutritional supplements. Online retail also kept climbing as digital platforms got better at showing product options and offering home delivery.
Specialty clinics, in the meantime, boosted their market footprint by providing more focused eye care services, faster appointment slots, and upgraded treatment technologies. A few other distribution routes helped with local access in smaller communities , especially through independent providers. Digital commerce and specialized healthcare delivery will keep getting better , so patient access improves across the broader regional vision care ecosystem.
By End User :
Adults showed up as the biggest end user group, mostly due to a kind of long screen time, workplace vision expectations, and the fact that routine eye examinations help keep treatment going. Kids, on the other hand, still need regular vision assessments , because schools tend to push early identification of refractive issues. Then there’s the geriatric population, which created notable clinical demand from cataracts, glaucoma, and those age related retinal conditions. In general, healthcare providers kept investing in advanced diagnostic and surgical technologies so care quality could be improved, while operational efficiency also gets a boost.
Other end users covered organizations running occupational vision programs and community health initiatives too. More preventive screening, and better access to care will likely strengthen the use of services across basically every demographic group. And with better diagnostic capability, long term disease management as well as clinical outcomes should improve.
By Treatment Type :
Vision correction stayed at the top as the main treatment option, because eyeglasses, contact lenses, and those refractive procedures were really tackling common visual disorders across lots of different people. Meanwhile the surgical side kept moving ahead with more cataract procedure volumes, plus an ongoing pull toward premium intraocular lenses. On the pharmaceutical side , growth stayed fairly steady, driven by prescription therapies for glaucoma, retinal diseases, infections, and even dry eye syndrome. Preventive eye care also started getting more attention, thanks to organized screening programs along with regular vision examinations.
Besides that, other treatment approaches helped cover more specialized clinical needs, which depends on the patient’s exact situation. With earlier diagnosis and more thoughtful treatment planning, long-term disease management looked better across different healthcare facilities. And, as the next period goes on, continued investment in technology , specialist services, and preventive care will help keep adoption strong for the overall forecast timeline.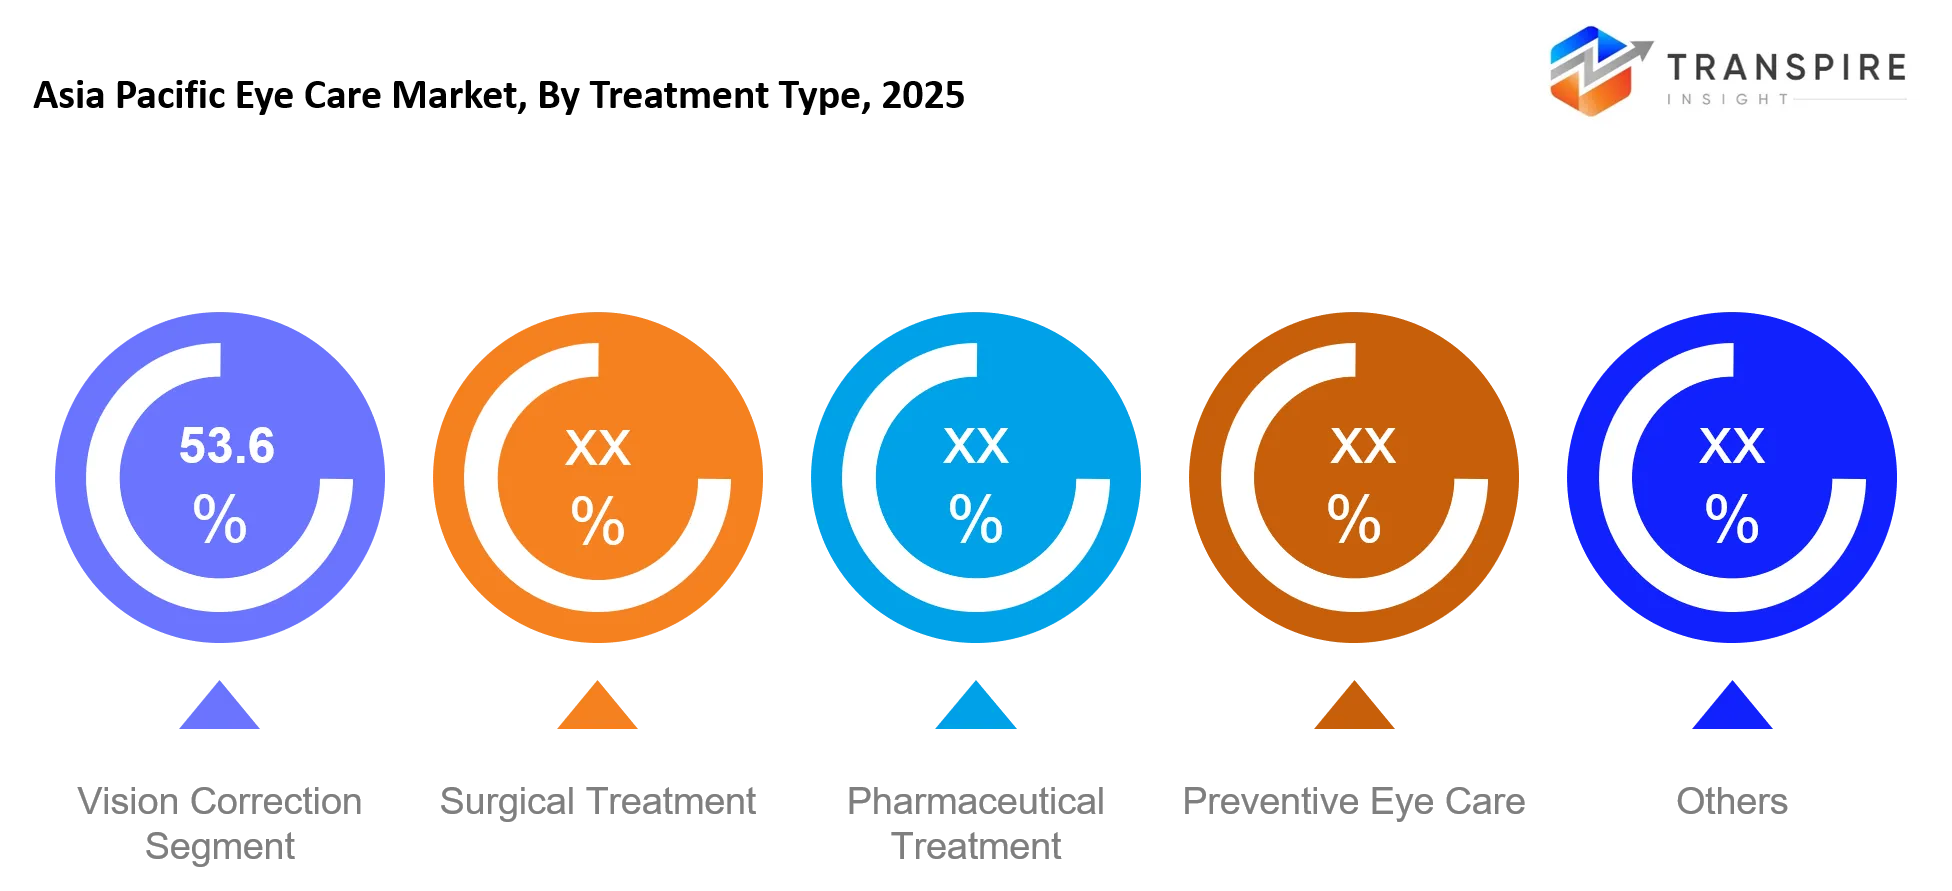
What are the Key Use Cases Driving the Asia Pacific Eye Care Market?
Vision correction is still the main reason people buy into this, because optical retailers, hospitals, and specialty clinics bring in eyewear, contact lenses, and diagnostic services to deal with refractive errors. Employers, schools, and healthcare providers also keep funding routine vision checks, so the whole thing helps productivity, improves learning outcomes, and supports long-term eye health, which basically keeps the commercial activity moving along the supply chain.
Cataract care , and retinal disease management are also getting bigger, as hospitals and dedicated eye clinics invest in more advanced surgical systems and imaging tools. On top of that, pharmaceutical suppliers and diagnostic equipment manufacturers get a boost from diabetic retinopathy screening efforts, these show up through public health programs and private healthcare networks.
More recently, AI-assisted screening and portable retinal imaging are starting to stand out as emerging uses with serious upside. Community healthcare programs , rural medical centers, and teleophthalmology networks are likely to adopt these tools to widen access to specialists, catch problems earlier, and back national vision care plans during the forecast period.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 5.16 Billion |
|
Market size value in 2026 |
USD 5.41 Billion |
|
Revenue forecast in 2033 |
USD 5.41 Billion |
|
Growth rate |
CAGR of 4.54% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Asia Pacific (India, China, Japan, Australia, South Korea, Rest of Asia Pacific) |
|
Key company profiled |
Alcon, Johnson & Johnson Vision, Bausch + Lomb, Carl Zeiss Meditec, EssilorLuxottica, CooperVision, Hoya Corporation, Topcon, NIDEK, Roche, Novartis, AbbVie, Santen Pharmaceutical, Canon Medical Systems, Haag-Streit . |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (Eyeglasses, Contact Lenses, Intraocular Lenses, Ophthalmic Drugs, Eye Care Supplements, Diagnostic Equipment, Others); By Application (Refractive Errors, Cataracts, Glaucoma, Dry Eye Syndrome, Retinal Disorders, Eye Infections, Others); By Distribution Channel (Hospitals, Optical Stores, Retail Pharmacies, Online Retail, Specialty Clinics, Others); By End User (Adults, Children, Geriatric Population, Healthcare Providers, Others); By Treatment Type (Vision Correction, Surgical Treatment, Pharmaceutical Treatment, Preventive Eye Care, Others) |
Which Regions are Driving the Asia Pacific Eye Care Market Growth?
East Asia accounted for about 46% of regional revenue, so it basically became the big dominant regional market. The strong healthcare infrastructure and those favorable reimbursement systems , plus the national vision screening programs helped keep adoption of advanced ophthalmic technologies pretty consistent. You had major manufacturers, research institutions, hospital networks, and optical retailers sort of working together, creating an integrated ecosystem that made products show up faster and also pushed clinical innovation along. Looking ahead, continued investment in digital diagnostics , specialist training, and care for an aging population should keep the region in the lead across the whole forecast period.
Southeast Asia, meanwhile, brought in steady revenue. This wasn’t mainly from one single growth factor, but more from private healthcare systems expanding while public health investment stayed balanced. Regulatory improvements, stable economic development, and broader insurance coverage nudged continuous buying of ophthalmic equipment, pharmaceuticals, and vision correction products. Local distribution partnerships helped too, and the growing specialty clinic networks improved access in both big cities and secondary cities. With predictable healthcare spending and gradual upgrades to infrastructure, the business opportunities should remain reliable through the forecast.
South Asia seems to be the fastest-growing regional market, since healthcare infrastructure investment and national blindness prevention programs picked up pace quite a lot in recent years. More private hospital capacity, wider insurance coverage, and easier access to specialty eye clinics have made it possible for patients to reach advanced treatment and diagnostic services sooner. At the same time, digital ophthalmology efforts, along with artificial intelligence -assisted screening, helped improve early disease detection even in underserved areas. As this region keeps growing from 2026 up through 2033, it should open some really appealing opportunities for manufacturers, healthcare providers, and investors looking to expand into rapidly evolving healthcare markets, especially where demand is rising.
Who are the Key Players in the Asia Pacific Eye Care Market and How Do They Compete?
Competition is still fairly consolidated, but not fully global ophthalmic manufacturers are in the mix with regional suppliers and smaller specialized healthcare firms, so it feels a bit split. In practice, technology innovation, clinical performance, and distribution strength are what mostly decide outcomes. At the same time, established companies keep tightening their product collections, while regional players expand using more specialized offerings , and localized service knows how that sounds simple but actually matters. Over time, product differentiation is leaning more toward digital diagnostics, premium surgical solutions, and integrated vision care platforms rather than price, like it used to be the main story.
Alcon, for instance, keeps its market standing by driving continual improvements in cataract surgery systems and premium intraocular lenses. That helps healthcare providers raise surgical outcomes and also speed up procedures a little. Johnson & Johnson Vision tends to emphasize advanced contact lens technologies and digital surgical solutions, and their edge comes through patient comfort plus precision based ophthalmic procedures. Carl Zeiss Meditec, meanwhile, invests strongly in high resolution imaging platforms and AI enabled diagnostic software. This supports earlier detection of disease and, importantly, better clinical decision making when it counts.
Bausch + Lomb is kind of expanding their product scope across pharmaceuticals, contact lenses, and surgical devices so clinicians can pull multiple treatment options from the same supplier, which is practical. EssilorLuxottica then blends optical retail growth with a more premium eyewear innovation angle, boosting consumer reach via integrated distribution routes and branded vision care services that feel more seamless. And Topcon Healthcare really differentiates by using cloud-connected diagnostic imaging plus digital healthcare platforms, which helps with better data exchange, remote consults, and overall workflow efficiency across hospitals, specialty clinics , and that kind of environment.
Company List
- Alcon
- Johnson & Johnson Vision
- Bausch + Lomb
- Carl Zeiss Meditec
- EssilorLuxottica
- CooperVision
- Hoya Corporation
- Topcon
- NIDEK
- Roche
- Novartis
- AbbVie
- Santen Pharmaceutical
- Canon Medical Systems
- Haag-Streit
Recent Development News
In April 2026, Alcon launched Clareon TruPlus Monofocal and Toric intraocular lenses at ASCRS 2026. The product launch expanded Alcon’s cataract surgery portfolio with enhanced IOL technology, strengthening its competitive position across Asia Pacific and other global ophthalmology markets. Source https://www.alcon.com/
In February 2026, Alcon launched TOTAL30 Multifocal for Astigmatism, the world's first monthly multifocal toric contact lens featuring Water Gradient Technology. The launch broadened advanced vision correction options for patients with astigmatism and presbyopia and supported continued innovation in the eye care market, including Asia Pacific. \
Source https://investor.alcon.com/
What Strategic Insights Define the Future of the Asia Pacific Eye Care Market?
Over the next five to seven years, the Asia Pacific Eye Care Market will, you know, lean more and more toward a more integrated, tech enabled vision care model that brings together early diagnosis, personalized care and remote patient oversight. It’s being pushed by a bunch of factors like population aging happening faster than before, more time on digital screens, wider access to healthcare, and also the rising use of artificial intelligence across ophthalmology. There’s also a quieter issue that doesn’t get as much attention, uneven regulatory standards and reimbursement rules across different regional markets, and that can actually slow down the launch of advanced diagnostic systems. So even when demand looks strong, adoption ends up a bit fragmented.
At the same time, an opportunity is starting to show up, especially community based screening initiatives. These can be helped by portable retinal imaging, plus AI assisted interpretation. This is likely to matter most in parts of Southeast Asia and in underserved rural areas, where specialist access is still a real limitation. For market players, the practical move is to focus on working with local healthcare providers and digital health platforms, while also crafting region specific regulatory pathways and distribution plans. That approach should help speed up adoption, reach more patients, and keep the long term competitive edge stronger.
Asia Pacific Eye Care Market Report Segmentation
By Product Type
- Eyeglasses
- Contact Lenses
- Intraocular Lenses
- Ophthalmic Drugs
- Eye Care Supplements
- Diagnostic Equipment
By Application
- Refractive Errors
- Cataracts
- Glaucoma
- Dry Eye Syndrome
- Retinal Disorders
- Eye Infections
By Distribution Channel
- Hospitals
- Optical Stores
- Retail Pharmacies
- Online Retail
- Specialty Clinics
By End User
- Adults
- Children
- Geriatric Population
- Healthcare Providers
By Treatment Type
- Vision Correction
- Surgical Treatment
- Pharmaceutical Treatment
- Preventive Eye Care
Frequently Asked Questions
Find quick answers to common questions.
The Expected Asia Pacific Eye Care Market size for the Market will be USD 5.41 Billion in 2033.
Key Segments for the Asia Pacific Eye Care Market are By Product Type (Eyeglasses, Contact Lenses, Intraocular Lenses, Ophthalmic Drugs, Eye Care Supplements, Diagnostic Equipment, Others); By Application (Refractive Errors, Cataracts, Glaucoma, Dry Eye Syndrome, Retinal Disorders, Eye Infections, Others); By Distribution Channel (Hospitals, Optical Stores, Retail Pharmacies, Online Retail, Specialty Clinics, Others); By End User (Adults, Children, Geriatric Population, Healthcare Providers, Others); By Treatment Type (Vision Correction, Surgical Treatment, Pharmaceutical Treatment, Preventive Eye Care, Others).
Major Asia Pacific Eye Care Market Players are Alcon, Johnson & Johnson Vision, Bausch + Lomb, Carl Zeiss Meditec, EssilorLuxottica, CooperVision, Hoya Corporation, Topcon, NIDEK, Roche, Novartis, AbbVie, Santen Pharmaceutical, Canon Medical Systems, Haag-Streit.
The Current Asia Pacific Eye Care Market size is USD 5.16 Billion in 2025.
The Asia Pacific Eye Care Market CAGR is 4.54% from 2026 to 2033.
- Alcon
- Johnson & Johnson Vision
- Bausch + Lomb
- Carl Zeiss Meditec
- EssilorLuxottica
- CooperVision
- Hoya Corporation
- Topcon
- NIDEK
- Roche
- Novartis
- AbbVie
- Santen Pharmaceutical
- Canon Medical Systems
- Haag-Streit
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Jul 2026
Alopecia Treatment Market
Alopecia Treatment Market Size, Share & Analysis Report By Disease Type (Alopecia Areata, Cicatricial Alopecia, Traction Alopecia, Alopecia Totalis, Androgenetic Alopecia, Alopecia Universalis, and Other Disease Types), By Treatment Type (Topical Treatments, Oral Medications, Injectable Therapies, and Hair Transplantation), By Gender (Male, and Female), By Distribution Channel (Hospitals and Clinics, Retail Pharmacies, and Online Retailers), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Jul 2026
Medical Ultrasound Probe Market
Medical Ultrasound Probe Market Size, Share & Analysis Report By Type (Linear Type, Convex Type, Endocavitary Probe, Phased Array/Cardiac Probe, Transesophageal (TEE) Probe, and Others), By Application (Ophthalmology, Cardiology, Musculoskeletal, Oncology, Obstetrics & Gynecology, General Imaging, and Others), By End User (Hospitals & Clinics, Diagnostic Centers, Ambulatory Surgical Centers, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
May 2026
Biosimilars Market
Biosimilars Market By Product Type (Monoclonal Antibodies, Recombinant Hormones, Erythropoietin, G-CSF, Others), By Indication (Oncology, Autoimmune Diseases, Blood Disorders, Diabetes, Others), By Manufacturing Type (In-House Manufacturing, Contract Manufacturing), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies, Online Pharmacies), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033
-
Apr 2026
Gastrointestinal Endoscopy Market
Gastrointestinal Endoscopy Market By Type (Rigid Gastrointestinal Endoscope, Flexible Gastrointestinal Endoscopes, Disposable Gastrointestinal Endoscope), By Procedure Type (Colonoscopy, Gastroscopy, Duodenoscopy, Enteroscopy, Flexible Sigmoidoscopy, Others), By Application (Diagnosis, Treatment), By End-Users (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Laboratories, Others), By Industry Analysis, Size, Share, Growth, Trends, and Forecasts 2021-2033