
Nov 02, 2026
Market Forecast
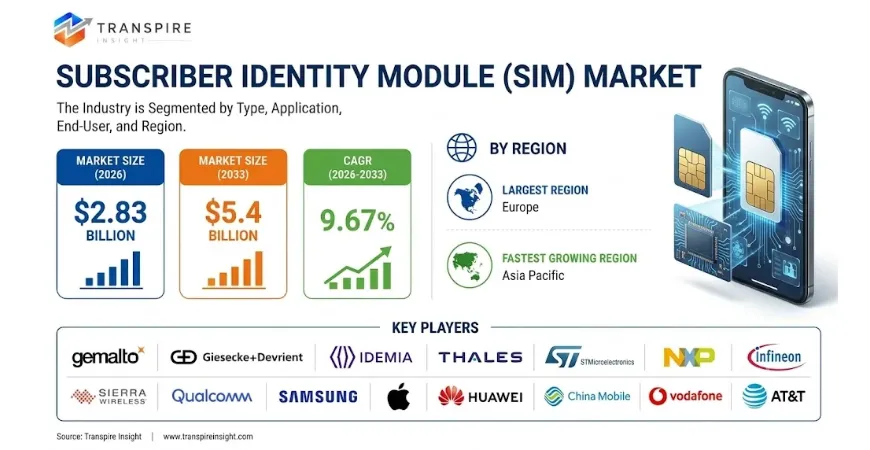
The global Subscriber Identity Module (SIM) market was valued at USD 2.58 billion in 2025 and is projected to grow from USD 2.83 billion in 2026 to USD 5.4 billion by 2033, at a CAGR of 9.67% through the forecast period, according to a new report by Transpire Insights.
The SIM market is undergoing its most significant structural transformation since the transition from full-size to micro and nano SIM form factors. The accelerating shift from physical removable SIM cards toward embedded eSIM and integrated iSIM solutions is reshaping the entire value chain — from SIM manufacturers and mobile network operators to device OEMs and enterprise IoT platform operators. This transition is simultaneously creating disruption for traditional physical SIM card volumes and opening substantial new markets in connected vehicles, IoT devices, and wearables.
SIM Market Growth & Trends
IoT device proliferation is the most significant volume growth driver in the SIM market, with billions of connected devices across smart metering, industrial monitoring, logistics tracking, connected vehicles, and consumer electronics each requiring a SIM or eSIM identifier for cellular connectivity. The addressable device population for SIM connectivity is growing far faster than the mobile handset market, and the embedded eSIM form factor — which can be integrated directly into device hardware without a removable card slot — is particularly well suited to the diverse enclosure and space constraints of IoT device design.
The automotive sector is one of the highest-value growth markets for eSIM, with connected vehicles requiring cellular connectivity for navigation services, OTA software updates, emergency call (eCall) functions, and telematics applications. EU legislation mandating eCall systems in all new passenger cars has established a regulatory baseline for cellular connectivity in European vehicles, and the broader connected vehicle service roadmap at automotive OEMs is driving eSIM specification across an expanding proportion of new vehicle production globally.
Emerging Economies & Technology
Asia Pacific is the fastest-growing region for SIM technology, driven by the world's largest mobile subscriber base in China and India, rapid IoT device deployment across Asian manufacturing and logistics sectors, and the concentration of consumer electronics manufacturing — where eSIM integration is being adopted — in China, South Korea, and Taiwan. Chinese mobile network operators are among the most active eSIM deployers globally, and domestic SIM manufacturers are scaling eSIM production capability alongside their traditional physical SIM output.
iSIM — integrated SIM where the SIM functionality is embedded directly within the device's main application processor rather than as a separate chip — is the next-generation SIM architecture that follows eSIM in the evolution toward smaller, more integrated connectivity solutions. Qualcomm's Snapdragon platforms with integrated iSIM capability are enabling smartphone and IoT device designs that eliminate the separate SIM chip entirely, and Apple's full transition to eSIM-only iPhone models in the United States has demonstrated that major OEMs are willing to remove physical SIM trays from premium consumer devices.
Standard SIM Segment
Standard SIM cards hold 39% of the global SIM market — the largest segment by current revenue share. Despite the trend toward miniaturisation and embedding, standard, micro, and nano SIM cards continue to generate substantial revenue across the large installed base of handsets and devices in developing markets where eSIM adoption is less advanced, prepaid mobile segments where physical SIM card swapping is a common user behaviour, and consumer preference for removable SIM flexibility in markets with multiple carrier options. The installed base of physical SIM-dependent devices globally runs into the billions, sustaining physical card production volumes through the forecast period.
Physical SIM security features — including advanced encryption, anti-cloning technology, and biometric SIM platforms — are generating premium pricing in segments where SIM security is a commercial priority, including financial services M-banking applications, government identity programmes, and enterprise mobile security deployments. These premium physical SIM applications sustain revenue above commodity prepaid SIM card economics.
eSIM: Dominant and Fastest-Growing Format
eSIM holds 72% of market value by the most advanced measure and is growing at a CAGR reflecting the transition away from physical SIM. Remote SIM provisioning — the ability to switch mobile network operator without physically replacing a SIM card — is the defining commercial capability of eSIM for both consumer and IoT applications. For consumers, the ability to switch carriers or add travel data plans remotely through a phone menu is a meaningful convenience improvement. For IoT device operators, the ability to manage connectivity across millions of devices from a centralised platform and switch to better-priced or better-coverage operators without physical field intervention is a transformative operational capability.
GSMA's SGP.02 (M2M eSIM) and SGP.22 (Consumer eSIM) specifications have established the interoperability standards that enable eSIM to function across different device manufacturers, SIM vendors, and mobile network operators — creating the ecosystem infrastructure that supports broad eSIM adoption. Thales, IDEMIA, and Giesecke+Devrient are the established leaders in eSIM personalisation and remote provisioning platform management.
Europe – Largest Regional Market
Europe holds 36% of the global SIM market — the largest regional share. European telecommunications infrastructure is among the most advanced globally, with high 4G and growing 5G penetration, and the EU's eCall mandate has created a regulatory baseline for automotive eSIM that does not exist in most other markets. European SIM security standards — including those governing SIM-based authentication for banking and government digital identity — sustain a premium physical and embedded SIM market above the commodity prepaid segment.
The European IoT deployment landscape — smart energy metering across EU member states, connected industrial equipment, and agricultural IoT — is generating consistent eSIM procurement across the region's manufacturing and utility sectors. European SIM vendors including Thales (formerly Gemalto) and Giesecke+Devrient maintain strong positions in the European enterprise and IoT eSIM market through their longstanding MNO and OEM relationships.
Asia Pacific – Fastest-Growing Region
Asia Pacific is advancing at a CAGR of 13.3% — the highest regional rate in this market. China's mobile market scale — with over 1.7 billion active SIM connections — and its rapid IoT deployment across smart cities, industrial monitoring, and consumer electronics generate the world's largest single national SIM consumption base. India's mobile market is one of the world's largest by subscriber count, and the government's Digital India initiative — including Aadhaar identity-linked SIM registration requirements — creates a structured framework for SIM market development.
South Korean and Taiwanese consumer electronics manufacturers — Samsung, LG, and their Taiwanese OEM counterparts — are integrating eSIM into an expanding proportion of their device portfolios, creating OEM-driven eSIM adoption that flows through to SIM vendor and MNO eSIM infrastructure investment across the Asia Pacific market.
What Are the Recent Developments in the SIM Market?
Q4 2024 – Thales: Launched a new eSIM platform for automotive OEMs incorporating multi-operator subscription management, enabling vehicle manufacturers to offer seamless carrier switching across global markets from a single embedded SIM hardware specification.
Q4 2024 – IDEMIA: Received GSMA certification for its next-generation SGP.32 IoT eSIM platform, enabling simplified remote provisioning for constrained IoT devices with limited processing power and memory — extending eSIM capability to the smallest and most resource-constrained connected device categories.
Q1 2025 – Giesecke+Devrient: Launched a biometric SIM card for mobile financial services in Sub-Saharan Africa, incorporating a fingerprint sensor directly on the SIM card to enable secure mobile banking transactions on basic feature phones without biometric hardware in the handset.
Q2 2025 – STMicroelectronics: Introduced a new iSIM solution integrated with its cellular modem chipset for IoT applications, enabling single-chip cellular connectivity with embedded SIM identity management for ultra-compact IoT device designs in wearable and industrial sensor applications.
Q2 2025 – Apple: Extended its eSIM-only iPhone model policy to additional markets beyond the United States, removing physical SIM card trays from new iPhone models in the UK and Australia and further accelerating consumer eSIM adoption in markets with strong carrier eSIM infrastructure.
Q3 2025 – Qualcomm: Announced the Snapdragon X85 modem platform with integrated iSIM functionality and 5G Advanced capability, targeting premium smartphone and connected device OEMs with a fully integrated cellular connectivity solution eliminating the need for a separate SIM component.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: inquiry@transpireinsight.com
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


