
Aug 08, 2026
Market Forecast
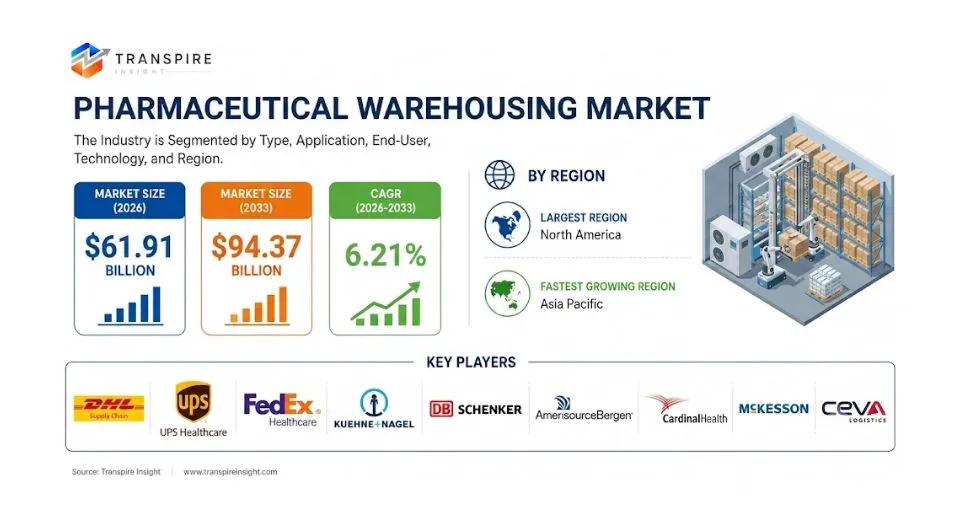
The pharmaceutical warehousing market was valued at USD 58.29 billion in 2025 and is projected to grow from USD 61.91 billion in 2026 to USD 94.37 billion by 2033, at a CAGR of 6.21% through the forecast period, according to a new report by Transpire Insights.
Rising biologics output, expanding vaccine distribution networks, and increasingly strict GDP (Good Distribution Practice) regulations are the central forces behind this growth. Pharmaceutical companies are under more pressure than ever to maintain product integrity across their supply chains, and that pressure translates directly into higher standards and more investment in purpose-built warehousing infrastructure worldwide.
Pharmaceutical Warehousing Market Growth & Trends
The pharmaceutical supply chain is handling greater complexity than at any previous point. Specialty drugs, cell and gene therapies, and large-molecule biologics all require tighter temperature management and more rigorous chain-of-custody documentation than conventional oral solid dosage forms. As these products account for a growing share of industry revenue, the warehousing infrastructure supporting them has had to upgrade accordingly in both physical capability and digital monitoring.
Contract manufacturing growth is adding another layer of demand. As more pharmaceutical companies outsource production, finished goods and active ingredients move through more distribution nodes before reaching the end patient, each of which requires compliant storage. Regulatory bodies in the US, EU, and increasingly in China and India are conducting more supply chain audits, raising the baseline compliance standard and pushing operators to invest in facility upgrades rather than risk approval delays or import bans.
Emerging Economies & Technology
Pharmaceutical manufacturing capacity is expanding rapidly across India, China, Southeast Asia, and Latin America, pulling warehousing investment into these regions alongside production growth. India's domestic pharma sector, already the world's largest supplier of generic medicines by volume, is building out cold chain and GDP-compliant distribution infrastructure to support both export and domestic distribution ambitions. China's "pharma valley" development zones include warehousing as a core infrastructure component, attracting significant private and state capital.
Technology investment is reshaping what pharmaceutical warehousing means in practice. IoT-enabled temperature and humidity monitoring, AI-driven inventory optimisation, and robotics-integrated pick-and-pack systems are migrating from pilot programmes to operational standards at major logistics hubs. The business case is straightforward: automated systems reduce picking errors, lower labour dependency, and generate the granular audit trails that regulators increasingly require. Operators who cannot demonstrate digital chain-of-custody are finding themselves excluded from contracts with major pharmaceutical manufacturers.
Cold Storage Warehousing Segment
Cold storage warehousing holds 48% of the pharmaceutical warehousing market, the largest segment by revenue. The shift of the drug pipeline toward temperature-sensitive biologics, monoclonal antibodies, and mRNA-based products has made reliable refrigerated and frozen storage a non-negotiable infrastructure requirement rather than a specialist niche. COVID-19 vaccine distribution demonstrated just how much cold chain capacity the industry could mobilise at speed and it also exposed the gaps that still exist in many markets.
Demand for ultra-low temperature (-80°C) storage is growing particularly fast as cell therapy and gene therapy products reach commercial-scale distribution. These products require specialised facility design, staff training, and monitoring systems that go well beyond conventional pharmaceutical refrigeration, creating a premium sub-segment with limited competition and strong pricing power for established operators.
Automated Pharmaceutical Warehousing: Fastest-Growing Segment
Automated pharmaceutical warehousing is growing at a CAGR of 11.5% the fastest rate across all warehouse types. Robotic storage and retrieval systems, autonomous mobile robots for intra-facility transport, and automated dispensing units are being retrofitted into existing facilities and specified as standard in new-build projects. The driver is not purely cost reduction: automation also delivers the consistency and documentation that pharmaceutical quality systems demand.
Labour shortages in key logistics markets, particularly in North America and Europe, have accelerated adoption timelines that might otherwise have stretched over a decade. Operators who previously viewed automation as a long-term capital project are moving faster, particularly for high-value or high-velocity pharmaceutical SKUs where picking errors carry significant financial and patient safety consequences.
North America – Largest Regional Market
North America holds 39% of the pharmaceutical warehousing market. The United States is home to the world's largest pharmaceutical consumption base, with a distribution infrastructure shaped by the Drug Supply Chain Security Act (DSCSA) requirements that have driven significant investment in serialisation-capable and digitally traceable warehousing systems. Major 3PL operators including McKesson, Cardinal Health, and AmerisourceBergen maintain nationwide cold chain distribution networks that serve as the backbone of US pharmaceutical distribution.
Canada contributes through its national pharmaceutical distribution programmes and its role as a secondary distribution hub for certain specialty products. Federal investment in domestic vaccine manufacturing and stockpiling capability post-pandemic has also generated incremental cold storage capacity across both countries.
Asia Pacific – Fastest-Growing Region
Asia Pacific is expanding at a CAGR of 12.8% the highest rate of any region in this market. China and India are simultaneously scaling pharmaceutical production and building the distribution infrastructure to move those products domestically and internationally. Both governments have tightened GDP compliance requirements in recent years, driving cold chain and controlled-environment warehousing investment that previously lagged production capability.
Japan and South Korea add demand through their advanced pharmaceutical and biotech sectors, both of which are expanding biologics manufacturing capacity. Southeast Asian markets particularly Singapore, which functions as a regional pharmaceutical distribution hub are investing in high-specification warehousing to serve both the ASEAN market and broader international export flows.
What Are the Recent Developments in the Pharmaceutical Warehousing Market?
Q4 2024 – DHL Supply Chain: Opened a new GDP-certified pharmaceutical distribution centre in Singapore with dedicated cold chain, controlled substance, and ambient warehousing zones, designed to serve as a regional hub for Southeast Asian pharmaceutical distribution.
Q4 2024 – Kuehne + Nagel: Expanded its KN PharmaChain service to include real-time IoT temperature monitoring across all pharmaceutical shipments, extending digital chain-of-custody documentation to every storage and transit leg in its network.
Q1 2025 – Cardinal Health: Commissioned a new automated pharmaceutical distribution facility in Ohio incorporating robotic storage and retrieval systems and AI-driven inventory management, targeting specialty drug and biologics distribution for hospital networks.
Q2 2025 – UPS Healthcare: Announced a USD 600 million expansion of its cold chain network across North America, including new ultra-low temperature storage capacity at five existing logistics campuses to support growing cell therapy distribution volumes.
Q2 2025 – CEVA Logistics: Secured a multi-year pharmaceutical warehousing and distribution contract with a top-ten pharma company to manage GDP-compliant storage and last-mile delivery across eight European markets.
Q3 2025 – McKesson: Launched an enhanced pharmaceutical inventory intelligence platform integrating AI-driven demand forecasting with warehouse management systems, targeting reduction of pharmaceutical waste and stockout events across its US distribution network.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: [email protected]
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates
 [email protected]
 APAC:+91 7666513636
 Address


