
Sep 05, 2026
Market Forecast
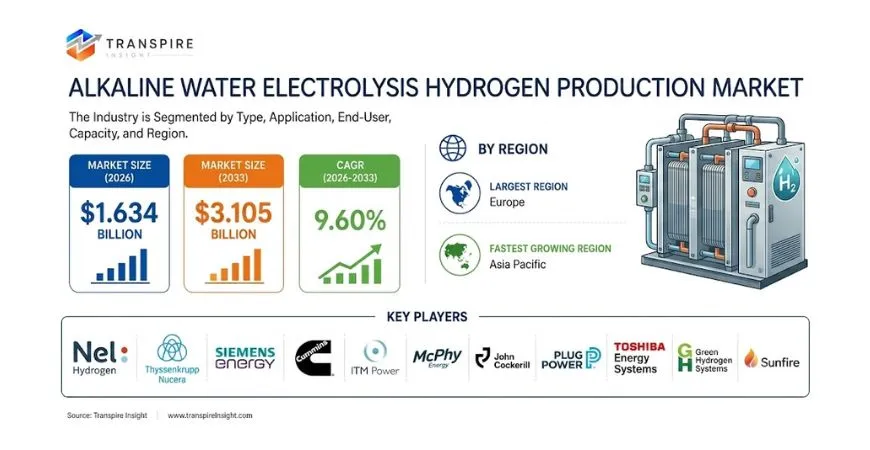
The global alkaline water electrolysis hydrogen production equipment market was valued at USD 1.492 billion in 2025 and is projected to grow from USD 1.634 billion in 2026 to USD 3.105 billion by 2033, at a CAGR of 9.60% through the forecast period, according to a new report by Transpire Insights.
Government green hydrogen targets in Europe, Japan, South Korea, and Australia backed by subsidies, electrolyser manufacturing incentives, and carbon pricing mechanisms are creating the policy pull that is accelerating commercial deployment of alkaline electrolysis systems at scale. Alkaline water electrolysis, as the most commercially mature electrolyser technology with the largest installed base globally, is well positioned to capture a significant share of the first wave of gigawatt-scale green hydrogen projects coming online through the late 2020s.
Alkaline Water Electrolysis Hydrogen Production Equipment Market Growth & Trends
The cost reduction trajectory of renewable electricity, particularly solar and wind, is progressively improving the economics of electrolytic hydrogen production and driving investment in large-scale alkaline electrolyser deployment. As the levelised cost of renewable electricity falls below thresholds where electrolytic hydrogen can compete with fossil-derived hydrogen in industrial applications, the economic case for green hydrogen projects strengthens independently of policy support, creating a commercial adoption dynamic that will sustain market growth beyond the current policy-driven investment cycle.
Industrial decarbonisation in ammonia production, steel manufacturing, and oil refining is the largest near-term demand driver for green hydrogen at scale. These industries collectively consume enormous volumes of hydrogen derived from fossil fuels, and the decarbonisation pathways available to them depend heavily on access to cost-competitive green hydrogen supply. Alkaline electrolysis systems at gigawatt scale are the primary technology route for producing the hydrogen volumes that industrial decarbonisation requires, and project development is advancing in the Netherlands, Germany, Saudi Arabia, Australia, and Chile.
Emerging Economies & Technology
Asia Pacific is the fastest-growing region for alkaline water electrolysis equipment, driven by ambitious green hydrogen targets in China, Japan, South Korea, and Australia. China has deployed more alkaline electrolyser capacity than any other single market, with domestic manufacturers including Peric Hydrogen, Tianjin Mainland, and CSIC producing systems at costs that are competitive with European and North American suppliers. Japan and South Korea are developing green hydrogen import supply chains sourcing hydrogen produced from renewable electricity in Australia and elsewhere that will require large-scale alkaline electrolysis at the point of production.
Technology development in alkaline electrolysis is addressing the operating flexibility limitations that have historically made conventional alkaline systems less well suited to intermittent renewable electricity input than PEM electrolysers. Advanced alkaline electrolysers with improved gas purification, wider partial load operating range, and faster response to power input changes are closing this flexibility gap while maintaining the cost and durability advantages that make alkaline technology the preferred choice for large baseload and semi-baseload green hydrogen production projects.
Industrial Hydrogen Production Segment
Industrial hydrogen production holds 58% of the global alkaline water electrolysis equipment market, the dominant application. Ammonia synthesis for fertiliser production, methanol production, and petroleum refining hydrogen requirements are the largest volume industrial hydrogen consumers, and the scale of their current fossil-derived hydrogen use represents the largest addressable decarbonisation opportunity for green hydrogen technology. The economics of replacing grey hydrogen with green hydrogen in these applications are closest to parity of any hydrogen end-use, particularly in markets with high carbon prices or carbon border adjustment mechanisms.
Steel industry decarbonisation is driving a new category of hydrogen demand that will be among the largest growth drivers for alkaline electrolysis through the forecast period. Direct reduction iron processes using green hydrogen instead of natural gas represent a fundamental steelmaking process change that major European steel producers including SSAB, ArcelorMittal, and ThyssenKrupp are investing in through pilot and demonstration plants that will scale toward commercial production through the late 2020s and 2030s.
Renewable-integrated Electrolyzers: Fastest-Growing Segment
Renewable-integrated alkaline electrolysers are growing at a CAGR of 13.2% the fastest rate in the market. Systems specifically designed and optimised for operation on variable renewable electricity inputs with improved dynamic response, enhanced partial load performance, and integrated power electronics for renewable coupling are the most commercially valuable equipment category for the growing pipeline of dedicated renewable hydrogen projects. Sunfire, Nel Hydrogen, and John Cockerill are all developing renewable-optimised alkaline electrolyser platforms that address the operational requirements of wind and solar-coupled production.
Energy storage applications using alkaline electrolysers to convert surplus renewable electricity into hydrogen for later reconversion in fuel cells or direct use are an expanding market for renewable-integrated systems. Grid-scale hydrogen storage projects in Germany, the UK, and Australia are providing commercial deployments that demonstrate the energy storage value proposition alongside green hydrogen production, generating operational data that supports further market development.
Europe – Largest Regional Market
Europe holds 38% of the global alkaline water electrolysis hydrogen production equipment market, the largest regional share. The EU Hydrogen Strategy's target of 40 GW of electrolyser capacity by 2030 supported by the European Green Deal, REPowerEU, and the Hydrogen Bank subsidy auction mechanism is creating the most comprehensive policy and financial support framework for green hydrogen deployment globally. Major alkaline electrolyser manufacturers including Nel Hydrogen, Thyssenkrupp Nucera, McPhy Energy, and John Cockerill all have significant European manufacturing and project development capability.
Germany is the largest individual national market within Europe, driven by its industrial base's hydrogen demand and the German government's National Hydrogen Strategy. The Netherlands, Spain, and France are also significant project markets, with major industrial port facilities Rotterdam, Antwerp, Dunkirk serving as hubs for green hydrogen import and distribution infrastructure that will anchor large-scale electrolyser deployment.
Asia Pacific – Fastest-Growing Region
Asia Pacific is advancing at a CAGR of 14.6% the highest regional rate in this market. China's domestic alkaline electrolyser industry has scaled rapidly, with manufacturing capacity growing from megawatt to gigawatt scale within a few years. Chinese domestic project deployment driven by provincial government renewable energy and green hydrogen targets is providing the commercial volume that is driving down Chinese alkaline electrolyser costs to among the lowest globally.
Australia is emerging as a major green hydrogen export economy, with large-scale renewable electricity resources and proximity to Japanese and South Korean hydrogen import markets creating a commercial basis for hydrogen production facilities that will require hundreds of megawatts to gigawatts of electrolyser capacity. Projects from bp, Fortescue, and Origin Energy are advancing through feasibility and development stages, with alkaline electrolysis as the primary or shortlisted technology for production at the scales these projects require.
What Are the Recent Developments in the Alkaline Water Electrolysis Hydrogen Production Equipment Market?
Q4 2024 – Nel Hydrogen: Received a contract for a 200 MW alkaline electrolyser system for a green ammonia project in Norway, one of the largest single alkaline electrolyser procurement contracts awarded in Europe and a demonstration of the technology's commercial readiness at utility scale.
Q4 2024 – Thyssenkrupp Nucera: Commissioned the first modules of its 24 MW green hydrogen production facility in Saudi Arabia under the NEOM project partnership, validating its alkaline electrolysis platform under the high ambient temperature operating conditions of Middle Eastern deployment environments.
Q1 2025 – Siemens Energy: Launched a next-generation alkaline electrolyser stack design achieving a 15% improvement in stack efficiency compared to its predecessor, targeting cost reduction below USD 1,000 per kilowatt of installed capacity for large-scale project procurement.
Q2 2025 – McPhy Energy: Secured European Innovation Fund financing for a gigawatt-scale alkaline electrolyser manufacturing facility in France, targeting annual production capacity of 1 GW by 2028 to serve the European green hydrogen project pipeline.
Q2 2025 – John Cockerill: Awarded a contract for alkaline electrolyser supply to a green steel demonstration project in Belgium, providing hydrogen production equipment for integration with a direct reduction ironmaking process in a commercially significant demonstration of steel sector decarbonisation.
Q3 2025 – Green Hydrogen Systems: Completed commissioning of a 20 MW renewable-integrated alkaline electrolyser system for a Danish offshore wind hydrogen production project, demonstrating dynamic load following operation tracking wind power output variation in a real grid-connected environment.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: [email protected]
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates
 [email protected]
 APAC:+91 7666513636
 Address


