
Sep 10, 2026
Market Forecast
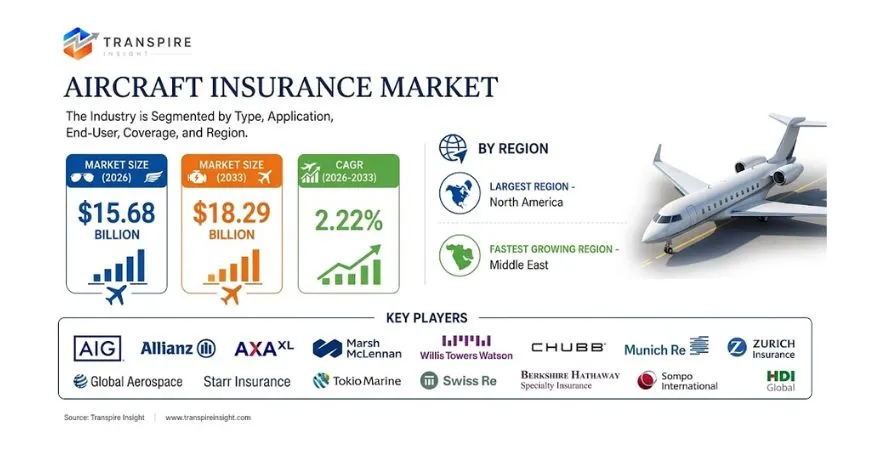
The global aircraft insurance market was valued at USD 15.34 billion in 2025 and is projected to grow from USD 15.68 billion in 2026 to USD 18.29 billion by 2033, at a CAGR of 2.22% through the forecast period, according to a new report by Transpire Insights.
Commercial aviation recovery - a growing global fleet - and evolving risk landscapes all over the world concerning war risk, cyber threats, and even new types of aircraft, including urban air mobility vehicles, really shape the aircraft insurance market right now. Even though the market is quite mature - and premium growth is relatively modest within its well-established commercial aviation core - emerging risk categories and an expanding fleet geographically do create entirely new demand segments adding incremental growth over the baseline renewal premium path.
Aircraft Insurance Market Growth & Trends
Global air travel demand has bounced back very strongly from the pandemic disruption and is getting close to and actually surpassing pre-pandemic levels in many markets already. Since the global commercial airline fleet keeps expanding to meet the recovering travel demand - with lots of new aircraft deliveries planned from Boeing and Airbus up until the late 2020s - the value of the insured hull value and passenger liability exposure of the entire global fleet is increasing, which mathematically raises the overall market premium regardless of rate changes.
War risk and geopolitical risk have become a much bigger deal in aircraft insurance market dynamics following Russia's invasion of Ukraine back in 2022, resulting in the most complicated aircraft insurance dispute in the market's history when Russian-leased planes got stuck and insurance coverage started getting disputed. The lessons learned from this event really are changing how war risk coverage is set up, priced, and monitored by the specialized aviation insurance market - and sustained geopolitical instability keeps war risk premiums high, contributing a lot to market revenue growth.
Emerging Economies & Technology
The Middle East is growing the fastest in terms of aircraft insurance, driven by the rapid expansion of Gulf carrier fleets - Emirates, Etihad, Qatar Airways - and the development of several new regional carriers across the broader Middle East and North Africa aviation market altogether. Gulf carriers are among the biggest buyers of new wide-body aircraft worldwide, holding large order books at Boeing and Airbus that translates into increasing insured fleet values over our forecast period.
Urban air mobility and advanced air mobility vehicles - eVTOL aircraft, self-driving delivery drones, and commercial drone services - are creating entirely new risk categories that the traditional aviation insurance market will have to develop its pricing, coverage, and loss modeling capabilities to address. These vehicles will operate in different airspace, at different scales, and with different risk profiles than traditional aviation - requiring new underwriting approaches from specialist aviation insurers and offering growth opportunities for insurers that establish themselves as leaders in these emerging categories.
Commercial Aircraft Insurance Segment
Commercial aircraft insurance holds 56 percent of the global market - it's the dominant segment. The combination of very high insured hull values - modern wide-body aircraft are insured at values exceeding $200 million per plane - and extremely high passenger liability limits really makes commercial airline fleet insurance the biggest premium pool in the aviation market. Major airline groups such as American Airlines, Delta, United, Lufthansa, and Air France-KLM are among the largest single insurance buyers in the aviation market itself.
The commercial aircraft insurance market actually operates within a relatively concentrated specialist market of Lloyd's of London syndicates, international insurance companies like AIG, Allianz, and AXA XL, and aviation specialist companies including Global Aerospace. This specialist market structure gives us technical underwriting expertise for a risk class that really requires quite deep aviation engineering and operational knowledge - but it also creates market concentration risks that really emerged quite visibly during the Russia-Ukraine aircraft insurance dispute itself.
War risk insurance: fastest-growing sector
War risk insurance is expanding at a CAGR of 7. 2 percent - the quickest pace within the aircraft insurance market. The Russia-Ukraine conflict, Middle Eastern instability, and even wider geopolitical risks intensifying have greatly increased the commercial and operational value of aviation war risk coverage for airlines, lessors, and lenders. War risk premiums have really risen significantly from pre-2022 times, and the very structure of war risk coverage - including the notice and cancellation terms that insurers rely on to handle unexpected exposure spikes - has actually been reworked for most of the world's aircraft fleet.
Political risk coverage for planes running in markets with higher governmental control or expropriation risk is another emerging sub-segment of aviation specialist insurance, dealing with the chance that leased aircraft in politically unstable markets might be held, taken, or get operationally unavailable to their owners. This type of coverage has truly become more active after the Russia stranding event, with lessors looking for greater protection than regular war risk policies give.
North America - biggest regional market
North America retains 41% of the global aircraft insurance market - the biggest regional portion. The United States holds the world's biggest commercial air travel market - and consequently the biggest national aviation insurance market too, with major carriers and a huge amount of general aviation and corporate jet fleets all needing insurance coverage. Lloyd's of London syndicates and US-licensed companies compete intensely for US aviation insurance placements, with top insurance brokers like Marsh McLennan and Willis Towers Watson managing the placement of the largest airline fleet programs.
The US business aviation industry - private jets, turboprops, and piston planes used by big corporations and high-net-worth people - represents a significant and high-premium-priced insurance section that Chubb, AIG, and specialized aviation insurers really compete to cater to. The recovery and ongoing expansion of business jet usage after the pandemic - which greatly accelerated both new aircraft purchases and flight time among current users - keeps this section's premium contribution stable.
Middle East – Fastest-Growing Region
The Middle East is advancing at a CAGR of 8.1% — the highest regional rate in this market. Emirates, Etihad, and Qatar Airways operate some of the world's most modern and largest widebody aircraft fleets, with ongoing orders for Boeing 777X, Boeing 787, and Airbus A350 aircraft that will continue to expand insured fleet values through the forecast period. The region's geographic position as a global connecting hub — with these carriers serving routes between virtually every major city pair globally — generates very high passenger liability exposure that sustains premium levels commensurate with the operational scale.
Saudi Arabia's aviation sector development — including Riyadh Air's new carrier launch with a major aircraft order, flynas and flyadeal expansion, and NEOM's planned air connectivity — is adding new commercial aviation insurance demand in a market that was previously dominated by the established Gulf carriers. This new carrier formation and fleet expansion is generating incremental insurance procurement that broadens the Middle East aviation insurance market beyond its existing base.
What Are the Recent Developments in the Aircraft Insurance Market?
Q4 2024 – AIG: Launched a dedicated eVTOL and urban air mobility insurance product covering hull, liability, and third-party personal injury risk for commercial eVTOL operations, targeting air taxi operators and logistics drone operators preparing for initial commercial service launches in the US and Europe.
Q4 2024 – Global Aerospace: Published revised war risk underwriting guidelines for aviation fleet insurance incorporating lessons from the Russia-Ukraine aircraft stranding event, including updated notice-of-cancellation provisions and clearer definitions of geopolitical risk trigger events for large airline programme placements.
Q1 2025 – Marsh McLennan: Structured a parametric aviation business interruption insurance product for a major airline group providing automatic premium payment triggered by defined weather or airspace closure events, without requiring loss adjustment for delays and cancellations caused by covered trigger events.
Q2 2025 – Munich Re: Signed a capacity agreement with a Lloyd's syndicate to provide reinsurance backing for a new class of autonomous commercial drone liability coverage, supporting the development of insurance products for commercial drone delivery and inspection operations as regulatory frameworks for BVLOS operations mature.
Q2 2025 – Allianz: Expanded its aviation cyber risk coverage to include operational technology and avionics systems across its commercial airline and MRO facility insurance programmes, responding to growing airline and regulator concern about cybersecurity threat exposure in connected aircraft systems.
Q3 2025 – Swiss Re: Released a global aviation war risk exposure model quantifying geographic concentration of insured hull values across current geopolitical risk zones, providing aviation insurers and capital market investors with a framework for assessing portfolio war risk accumulation under different conflict scenario assumptions.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: [email protected]
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates
 [email protected]
 APAC:+91 7666513636
 Address


