
Sep 01, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the In-vitro Diagnostics (IVD) market size is projected to grow from USD 92.23 billion in 2026 to USD 149.5 billion by 2035, at a CAGR of 7.85% during the forecast period 2026-2035. The in-vitro diagnostics market is fueled by rising prevalence of chronic diseases globally, growing demand for point-of-care testing, rapid adoption of artificial intelligence in laboratories, growing companion diagnostics, and the increasing elderly population that needs to be frequently monitored for clinical disease.
Introduction
In-vitro diagnostics (IVD) refers to medical tests carried out on bodily fluids, such as blood, tissue, and urine, for the detection, monitoring, and management of different medical conditions outside of the human body. IVD solutions are critical in today's clinical medicine, allowing healthcare workers to access reliable information to diagnose and prevent diseases and treat them early. The IVD market continues to evolve, transforming patient care globally through quick, accurate, and decentralized testing ecosystems, supported by breakthroughs in biotechnology, molecular diagnostic platforms, digital health platforms, and automated laboratory systems.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive In-vitro Diagnostics (IVD) Market sample report today to explore expert insights, key trends, and emerging opportunities shaping the future of the industry.
In-vitro Diagnostics (IVD) Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America remains the market leader for IVD, owing to its sophisticated healthcare system and the presence of a few major manufacturers, including Abbott, Thermo Fisher Scientific, BD, and Danaher, which are all based in the region and tend to frequently launch new products. Hundreds of thousands of clinical laboratories operate in the U.S., performing billions of tests annually, and government figures reveal a significant percentage of the population with one or more chronic conditions, ensuring steady demand for routine and specialized diagnostic panels. Favorable reimbursement policies, continued support from the FDA for accelerated approval protocols, and significant investments in precision medicine and AI-powered diagnostic platforms continue to strengthen the region's leading role, and the use of high-throughput analyzers in hospital labs and reference labs maintains a consistent demand for reagents and consumables.
Asia Pacific's rapid ascent is anchored in a very different set of dynamics: a still-underpenetrated but fast-modernizing diagnostic infrastructure combined with an enormous disease burden. The South-East Asia region of the WHO accounts for almost 50% of the world's TB burden, and the national rollout of HPV DNA-based tests for cervical cancer screening rather than the traditional methods is institutionalizing the adoption of modern IVD testing in a significant way. In cost-sensitive segments, local manufacturers from across China and India, including domestic players with manufacturing divisions producing affordable PCR and rapid-test kits, are increasingly entering the fray to gain access, while the government's increasing healthcare spending, an ageing population and increased awareness around early detection are driving molecular diagnostics and point-of-care testing further into the healthcare network.
Top 15 Trends in the In-vitro Diagnostics (IVD) Market
Proceed to checkout to purchase the exclusive In-vitro Diagnostics (IVD) Market report and get instant access to detailed market insights, strategic analysis, and future growth opportunities.
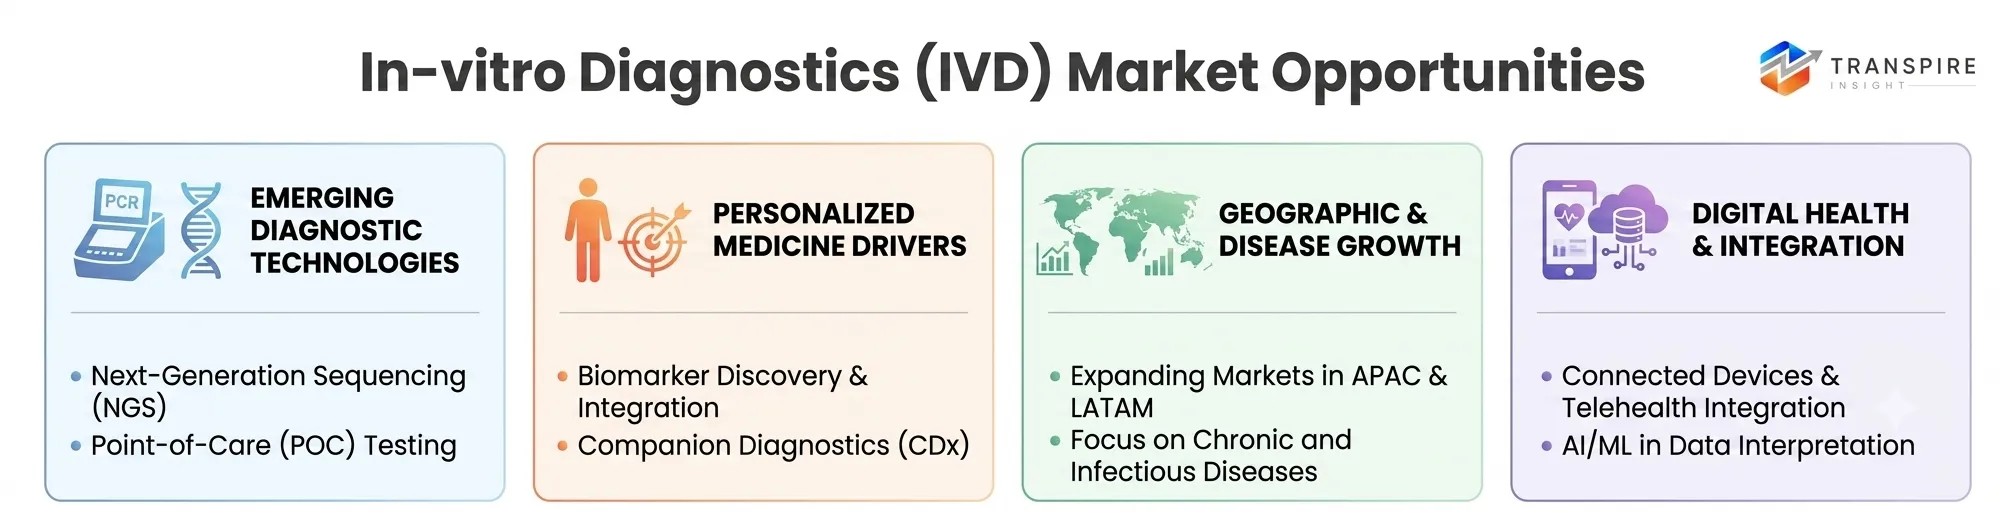
Point-of-Care and Rapid Testing
Demand for point-of-care testing is rising sharply as hospitals, clinics, and home users seek faster, accurate results without dependence on centralized laboratory infrastructure and staffing.
Molecular Diagnostics Growth
Molecular diagnostics, including PCR and next-generation sequencing, continue gaining share as clinicians increasingly demand higher sensitivity for infectious disease, oncology, and genetic disorder testing panels.
AI-Driven Diagnostics
Artificial intelligence is transforming diagnostic workflows through automated image analysis, predictive algorithms, and faster interpretation of complex laboratory data across pathology, radiology, and genomics laboratories.
Personalized Medicine
Personalized medicine is driving demand for biomarker-based diagnostics that guide targeted therapy selection, improve treatment outcomes, and significantly reduce unnecessary drug exposure for patients globally.
Companion Diagnostics
Companion diagnostics are expanding alongside targeted oncology drugs, helping physicians match each patient to therapies most likely to succeed based on tumor biomarker profiles.
Liquid Biopsy
Liquid biopsy technology is gaining traction for non-invasive cancer detection, enabling earlier diagnosis, real-time monitoring, and reduced reliance on traditional invasive surgical tissue biopsy methods.
List of Top 25 Companies Leading the In-vitro Diagnostics (IVD) Market
Customize the exclusive In-vitro Diagnostics (IVD) Market report to receive insights tailored to your needs, including country-specific analysis and business-focused market intelligence.
Roche remains the revenue leader in molecular diagnostics and automated lab systems.
Founded: 1896 | HQ: Basel, Switzerland.
Why It Ranks: Exceptional market share across clinical chemistry, tissue diagnostics, and high-throughput systems.
Regional Dominance: Europe and North America maintain solid core market leadership for clinical diagnostics.
Product Line: Cobas analyzers, Elecsys immunoassay reagents, and Ventana tissue diagnostic platforms.
Abbott dominates point-of-care, rapid lateral flow testing, and cardiovascular diagnostics worldwide.
Founded: 1888 | HQ: Abbott Park, Illinois, USA.
Why It Ranks: Massive distribution network and continuous innovation in decentralised diagnostic testing.
Regional Dominance: Strong presence across North America, Latin America, and expanding Asian healthcare markets.
Product Line: Alinity diagnostic systems, BinaxNOW tests, and FreeStyle Libre continuous glucose monitors.
Operates leading diagnostic brands including Beckman Coulter, Cepheid, and Leica Biosystems.
Founded: 1984 | HQ: Washington, D.C., USA.
Why It Ranks: Unmatched portfolio in automated hematology, immunoassay, and rapid PCR testing systems.
Regional Dominance: Commands substantial market share across North American and Western European hospital laboratories.
Product Line: GeneXpert molecular platforms, Access immunoassay analyzers, and DxH hematology series systems.
A prominent pioneer in integrating laboratory automation with digital health diagnostic workflows.
Founded: 1847 | HQ: Erlangen, Germany.
Why It Ranks: Industry leadership in total lab automation and comprehensive high-volume clinical chemistry platforms.
Regional Dominance: Strong operational footprint throughout Europe, North America, and key Asia-Pacific regions.
Product Line: Atellica Solution analyzers, ADVIA clinical chemistry, and RapidLab blood gas systems.
scientific leader supplying essential molecular diagnostic reagents and sequencing infrastructure.
Founded: 1956 | HQ: Waltham, Massachusetts, USA.
Why It Ranks: Unrivaled capabilities in mass spectrometry, real-time PCR, and next-generation gene sequencing.
Regional Dominance: Dominates North American markets while rapidly expanding across Asia-Pacific clinical networks.
Product Line: Applied Biosystems PCR systems, Ion Torrent sequencers, and TaqMan assay kits.
Worldwide leader in clinical microbiology, sample collection, and automated specimen management.
Founded: 1897 | HQ: Franklin Lakes, New Jersey, USA.
Why It Ranks: Dominates pre-analytical diagnostic workflows, blood collection, and infectious disease detection tools.
Regional Dominance: Holds leading shares in North America, Latin America, Europe, and Asia-Pacific.
Product Line: BD COR molecular systems, BD MAX platforms, and Vacutainer specimen collection.
World leader in specialized infectious disease diagnostics and clinical microbiology testing systems.
Founded: 1963 | HQ: Marcy-l'Étoile, France.
Why It Ranks: Unrivaled syndromic testing platforms for rapid multiplex detection of infectious pathogens.
Regional Dominance: Strong European market roots with expansive growth in the Americas and Asia-Pacific.
Product Line: BioFire FilmArray platforms, VITEK automated ID/AST systems, and VIDAS immunoassay reagents.
market leader in automated hematology instrumentation and urinalysis diagnostic platforms.
Founded: 1968 | HQ: Kobe, Japan.
Why It Ranks: Controls the vast majority of hematology testing market share worldwide.
Regional Dominance: Leading market presence in Asia-Pacific with strong adoption in European hospitals.
Product Line: XN-Series hematology analyzers, UN-Series urinalysis platforms, and CyFlow flow cytometry instruments.
Leading innovator dedicated to women's health diagnostics, cervical screening, and virology.
Founded: 1985 | HQ: Marlborough, Massachusetts, USA.
Why It Ranks: Dominates molecular screening for human papillomavirus and sexually transmitted infectious diseases.
Regional Dominance: Solid market control in North America alongside growing adoption in European markets.
Product Line: Panther molecular systems, ThinPrep Pap tests, and Aptima infectious disease assays.
Pioneer in sample preparation, molecular diagnostics, and specialized bioinformatics workflow software.
Founded: 1984 | HQ: Venlo, Netherlands.
Why It Ranks: Standard-setting sample preparation technologies essential for molecular and genomic diagnostic applications.
Regional Dominance: Widespread footprint across Europe, North America, and major Asian academic research centers.
Product Line: QIAsymphony systems, QIAstat-Dx platforms, and QuantiFERON tuberculosis diagnostic assay kits.
Schedule a meeting with our market experts to discuss the exclusive In-vitro Diagnostics (IVD) Market report and find the right research solution for your business.
Conclusion
In-vitro diagnostics (IVD) is at the forefront of the transformation of modern healthcare, with technology advancements in artificial intelligence, next-generation sequencing, and decentralized point-of-care testing platforms all driving this transformation. With a changing paradigm in healthcare that favors early detection, personalized medicine, and swift remote patient monitoring, key market players are still making strides across the molecular assays, immunoassays, and total laboratory automation (TLA) areas. In the future, strategic partnerships across industries and digitalization will continue to be essential for enhancing diagnostic availability, patient outcomes, and the future of precision medicine.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


