
Sep 07, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the private security services market size is projected to grow from USD 307.2 billion in 2026 to USD 472.23 billion by 2035, at a CAGR of 6.72% during the forecast period 2027-2035. The private security services market expansion is driven by accelerating urbanization, rising geopolitical volatility, growing commercial infrastructure investments, expanding crime concerns, and rapid adoption of AI-powered remote surveillance and hybrid guarding solutions.
Introduction
Private security services form a critical foundation for protecting corporate, public, and residential assets. As traditional public law enforcement resources face capacity constraints, private entities increasingly rely on contracted security providers to mitigate evolving physical and operational risks. The sector is rapidly transforming from labor-intensive security guarding to technology-driven hybrid solutions, seamlessly integrating physical patrols, automated remote surveillance, advanced threat intelligence, and AI-enabled access control systems to provide comprehensive multi-layered protection.
Recent Developments
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Private Security Services Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance rests on a deeply entrenched outsourcing culture, where corporations, retail chains, and residential complexes routinely hand off protection functions to specialized providers rather than maintaining in-house teams. Players such as Allied Universal, GardaWorld, and Securitas have consolidated much of this demand through repeated acquisitions of regional guarding and monitoring firms, bundling manned guarding with electronic surveillance and remote video monitoring into single-vendor contracts. Retail loss prevention, corporate campus access control, and large-scale event security remain steady demand pillars, while rising interest in cybersecurity-integrated risk consulting is pushing legacy manned-guarding companies to reposition themselves as broader protective-services firms rather than pure labor providers.
Asia Pacific's growth trajectory is driven by a very different dynamic: greenfield infrastructure and first-time formalization of security spending rather than replacement demand. China's continued investment in logistics parks, industrial zones, and Belt and Road-linked infrastructure has expanded the addressable base for site security and asset protection, while India's booming IT parks, warehousing, and e-commerce fulfillment centers have made manned guarding and access control near-default requirements for commercial landlords. Regional players such as SIS Group and Securiguard, alongside entrants expanding their footprint in the region, are scaling operations to meet demand from apartment complexes and gated residential developments, where urban crime concerns are pushing households toward professional guarding for the first time.
Top 15 Trends in the Private Security Services Market
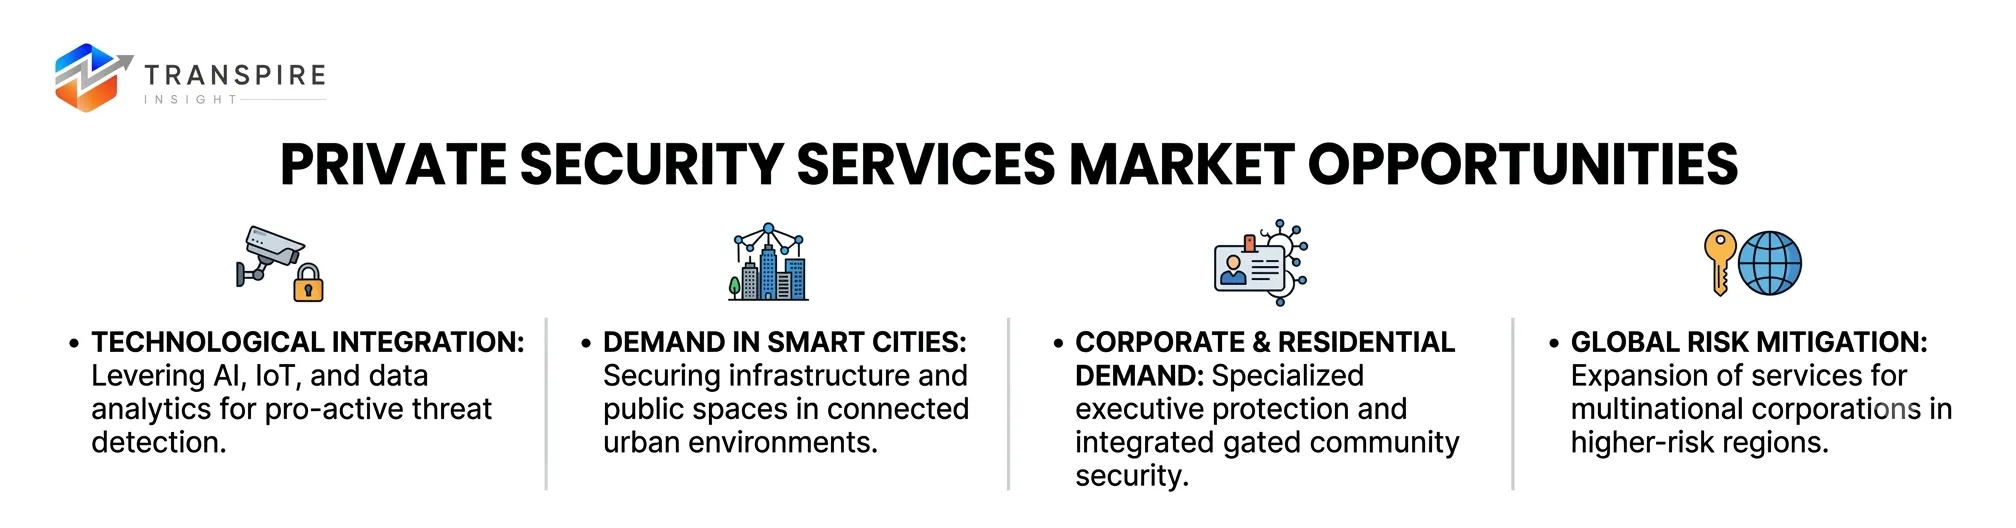
Security firms increasingly deploy AI-driven video analytics for real-time threat detection, cutting manual monitoring reliance and improving response speed across retail and corporate client sites.
Clients now demand converged offerings combining manned guarding, surveillance, and cybersecurity services, pushing providers like Allied Universal and G4S toward integrated digital-physical protection service models.
Large industrial and logistics sites increasingly deploy drones for perimeter patrols, cutting labor costs while covering larger areas much faster than traditional foot-based guarding teams.
Major players such as Securitas, GardaWorld, and Allied Universal continue acquiring regional security firms, expanding geographic reach while smaller independent operators face growing competitive pressure.
Corporations increasingly outsource in-house security to specialized providers, seeking cost efficiency, trained personnel, and access to advanced surveillance technology without maintaining dedicated internal security departments.
Rising urban crime concerns push gated communities and apartment complexes toward professional guarding services, with providers like SIS Group and Securitas expanding dedicated residential security offerings.
List of Top 25 Companies Leading the Private Security Services Market
1. Allied Universal
Largest private security workforce delivering integrated physical guarding and technology solutions.
Founded: 1957 | HQ: Conshohocken, Pennsylvania, USA.
Why It Ranks: Unmatched workforce scale and market dominance across North America.
Regional Dominance: Strongest presence in North America, Europe, Latin America, and Asia-Pacific.
Product Line: Manned guarding, electronic security systems, janitorial, and risk advisory services.
2. Securitas AB
security leader specializing in intelligence-led guarding and electronic risk solutions.
Founded: 1934 | HQ: Stockholm, Sweden.
Why It Ranks: Major market share driven by advanced technology integration and international footprint.
Regional Dominance: Massive operations across North America, Europe, and Latin America.
Product Line: On-site guarding, remote guarding, electronic security, and threat intelligence.
3. G4S (An Allied Universal Company)
security brand operating extensively in government, corporate, and high-risk sectors.
Founded: 1901 | HQ: London, United Kingdom.
Why It Ranks: Deep international presence with operations spanning more than 100 countries.
Regional Dominance: Primary market strength in Europe, Middle East, Africa, and Asia-Pacific.
Product Line: Secure solutions, cash logistics, risk management, and electronic systems.
4. Prosegur Compania de Seguridad
Spanish multinational providing comprehensive physical guarding, cash management, and alarm systems.
Founded: 1976 | HQ: Madrid, Spain.
Why It Ranks: Market leadership across Spanish-speaking nations and strong technology innovation focus.
Regional Dominance: Dominant footprint in Europe, Latin America, and Australia.
Product Line: Prosegur Security (guarding), Cash, Alarms, and AVOS technology platforms.
5. SIS Limited (Security and Intelligence Services)
Premier Asian security services giant delivering guarding, facility management, and cash logistics.
Founded: 1974 | HQ: New Delhi, India.
Why It Ranks: Unrivaled market presence and rapid expansion across high-growth Asian markets.
Regional Dominance: Heavy dominance across India, Australia, and New Zealand.
Product Line: Security guarding, electronic security, cash logistics, and facility management.
6. GardaWorld
World's largest privately held security services company delivering physical and cash solutions.
Founded: 1995 | HQ: Montreal, Quebec, Canada.
Why It Ranks: Specialized capabilities in high-risk protection, cash logistics, and international crisis response.
Regional Dominance: Dominant position in Canada, North America, Middle East, and Africa.
Product Line: Physical security guards, cash services, travel risk, and crisis response.
7. Secom Co., Ltd.
Japanese pioneer delivering centralized electronic security, automated monitoring, and physical patrols.
Founded: 1962 | HQ: Tokyo, Japan.
Why It Ranks: Premier provider of automated security systems and emergency response services globally.
Regional Dominance: Complete market dominance in Japan and strong presence across East/Southeast Asia.
Product Line: Centralized security monitoring, home alarms, physical guarding, and cyber services.
8. Sohgo Security Services Co., Ltd. (ALSOK)
Leading Japanese security firm offering comprehensive physical guarding, automated protection, and logistics.
Founded: 1965 | HQ: Tokyo, Japan
Why It Ranks: Trusted provider for high-profile commercial, government, and financial facility protection.
Regional Dominance: Heavy market consolidation across Japan and key Asian trade hubs.
Product Line: Stationed security guarding, cash transportation, and automated alarm systems.
9. Brink's Company
Legendary security logistics firm specializing in secure transit, cash management, and guarding.
Founded: 1859 | HQ: Richmond, Virginia, USA.
Why It Ranks: Uncontested leader in high-value asset protection and secure cash transport.
Regional Dominance: Expansive operational footprint across North America, Europe, and Latin America.
Product Line: Armored transport, ATM services, vault management, and physical guard security.
10. Loomis AB
European cash-in-transit specialist delivering secure logistics and integrated physical security solutions.
Founded: 1934 | HQ: Stockholm, Sweden.
Why It Ranks: Leading international reputation in financial infrastructure protection and physical cash logistics.
Regional Dominance: Widespread coverage across North America and Western Europe.
Product Line: Cash-in-transit, safepoint smart safes, foreign exchange, and physical security.
Conclusion
The private security services market is rapidly evolving as organizations face increasingly complex physical and digital threat landscapes. Key industry leaders are actively transitioning from conventional labor-heavy models to technology-driven hybrid paradigms, combining physical security personnel with AI surveillance and open-source threat intelligence. As urbanization continues and public security resources remain stretched, integrated security providers will play an irreplaceable role in safeguarding commercial, governmental, and critical infrastructure assets.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


