
Sep 11, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the fluorosurfactants market size is projected to grow from USD 1.92 billion in 2026 to USD 2.10 billion by 2035, at a CAGR of 2.28% during the forecast period 2027-2035. The market is driven by the growing demand for high performing wetting and leveling agents for paints, coatings, adhesives and semiconductors. Moreover, regulatory shifts to more environmentally friendly short-chain fluorochemicals speed up the formulation of new products globally.
Introduction
Fluorosurfactants are highly effective synthetic surfactants which have been developed to significantly reduce the surface tension of liquid systems. They are essential in many specialty industrial applications such as paints, adhesives, semiconductor processing and firefighting foam. They have excellent thermal stability, chemical resistance and wetting properties. Though environmental concerns have cast light on legacy PFAS chemistries, the market keeps growing with clean-technology innovations and product improvements with short-chain non-bioaccumulative chemistries.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Fluorosurfactants Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
Asia Pacific's leadership is anchored in China's expanding semiconductor and electronics base, where the national drive for chip self-reliance and ongoing fab investment keeps demand tied to high-purity fluorosurfactant grades used in lithography and cleaning processes. It's backed up by innovation activity around the region: AGC Inc., for example, has launched innovative fluorosurfactants, designed for flexible electronics, and won early acquisition contracts valued at tens of millions of dollars within months of commercial launch. In addition to the Chinese market, other Asian markets such as Japan, South Korea, and India are still growing, providing a significant scale and end-use diversification. However, the combination of specialty demand in the region, driven by chips, and wide industrial demand places Asia Pacific in a structural lead over all other regions in absolute volume.
The percentage growth in Europe is not only due to volume growth, but also to the regulatory transformation. Shrinking legacy product lines and growth in replacement chemistries that are compliant with the European Union's new PFAS regulations are creating revenue waves for manufacturers as they move away from old chemistries. Germany leads the region with its highest national market share, bolstered by its sophisticated infrastructure for producing specialty chemicals, as well as its green regulation programs, while France and the UK closely follow, with automotive coating integration and eco-compliant formulation programs driving the two nations. Compliance dates are creating a need for near-term reinvestment throughout the regional supply chain, leading to a faster growth rate in Europe than its more mature and broad-based revenue base.
Top 15 Trends in the Fluorosurfactants Market
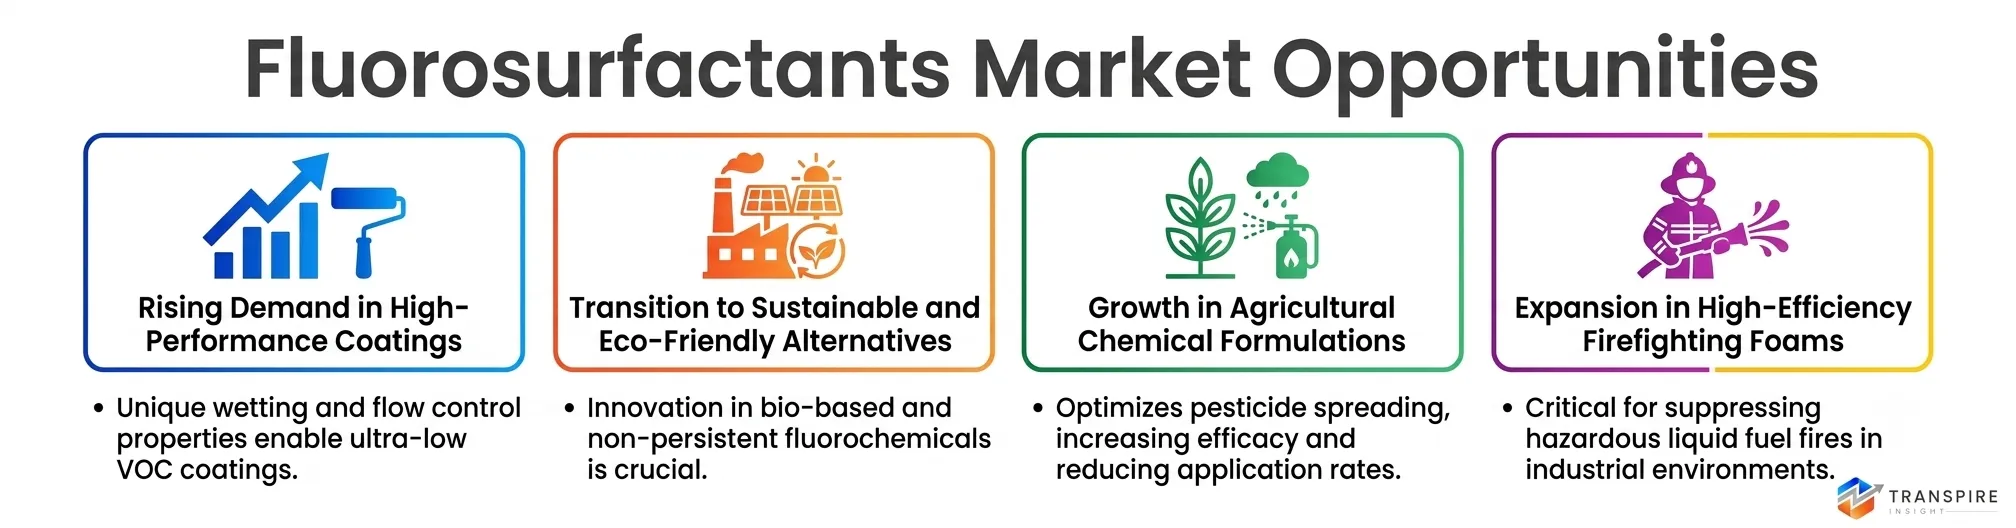
Shift toward short-chain, PFAS-compliant fluorosurfactant formulations
Manufacturers are reformulating away from long-chain perfluorinated compounds toward shorter-chain alternatives that meet tightening regulatory limits worldwide while still preserving wetting, leveling, and tension-reduction performance.
Tightening PFAS regulations reshaping product development priorities
Expanding PFAS restrictions across the European Union and several U.S. states are forcing producers to redirect research budgets toward compliant chemistries, raising compliance costs sharply.
Rising demand from semiconductor fabrication and lithography
Advanced node chip manufacturing requires high-purity fluorosurfactants for photoresist and cleaning processes, and China's drive for semiconductor self-reliance is steadily anchoring sustained fab-related demand growth.
Telomer-based fluorosurfactants gaining share over legacy chemistries
Telomer-based fluorosurfactants are winning share from older perfluorooctane chemistries because they offer comparable surface performance with a more favorable environmental and regulatory compliance profile overall.
Electronics and flexible display manufacturing driving specialty demand
Flexible electronics and next-generation display manufacturing require specialty fluorosurfactants for uniform coating and surface tension control, prompting suppliers like AGC to launch tailored product lines.
Rising firefighting foam reformulation amid PFAS restrictions
Firefighting foam manufacturers are reformulating away from legacy PFAS-based surfactants under mounting regulatory pressure and liability concerns, accelerating adoption of fluorine-free and short-chain alternatives rapidly.
List of Top 25 Companies Leading the Fluorosurfactants Market
1. The Chemours Company
Chemours leads fluorochemistry through its flagship Capstone non-ionic and anionic fluorosurfactant lines.
Founded: 2015 | HQ: Wilmington, Delaware, USA.
Why It Ranks: Holds major market share driven by advanced short-chain fluorinated additive solutions.
Regional Dominance: Dominates North American markets with strong export operations across Western Europe.
Product Line: Capstone FS-30, Capstone FS-31, Capstone FS-60, Capstone FS-63, Capstone FS-65.
2. 3M Company
3M produces high-performance Novec liquid fluorosurfactants used in precision cleaning and electronics.
Founded: 1902 | HQ: St. Paul, Minnesota, USA.
Why It Ranks: Unrivaled legacy portfolio and massive brand penetration across electronic supply chains.
Regional Dominance: Strong market presence spanning North America, East Asia, and Western Europe.
Product Line: 3M Novec 4200, Novec 4300, Novec FC-4430, Novec FC-4432, Fluorad.
3. Solvay S.A.
Solvay manufactures specialty fluorochemicals and short-chain fluorinated surfactant formulations for high-tech coatings.
Founded: 1863 | HQ: Brussels, Belgium.
Why It Ranks: leadership in high-purity chemical manufacturing and sustainable process engineering innovation.
Regional Dominance: Dominates the European Union market while maintaining extensive production across Asia.
Product Line: Fluorolink C10, Fluorolink S10, Fluorolink 7004, Fomblin, Polymer Additives.
4. AGC Inc.
AGC supplies Surflon non-ionic and cationic fluorosurfactants engineered for electronic chemical formulations.
Founded: 1907 | HQ: Tokyo, Japan.
Why It Ranks: Key supplier to Asia-Pacific semiconductor original equipment manufacturers and chemical compounders.
Regional Dominance: Commands top market share across Japan, South Korea, Taiwan, and China.
Product Line: Surflon S-241, Surflon S-242, Surflon S-243, Surflon S-651, Surflon S-386.
5. Daikin Industries, Ltd.
Daikin develops Unidyne fluorosurfactants tailored for oil and water repellency in technical textiles.
Founded: 1924 | HQ: Osaka, Japan.
Why It Ranks: Dominant international position in advanced fluorochemical engineering and surface treatment technologies.
Regional Dominance: Massive production footprint across Japan, Southeast Asia, and North America.
Product Line: Unidyne TG-5521, Unidyne TG-5541, Unidyne TG-8111, Ftone, Unidyne TG-5601.
6. DuPont de Nemours, Inc.
DuPont provides specialized short-chain fluorochemical wetting agents for industrial cleaning and microelectronics.
Founded: 1802 | HQ: Wilmington, Delaware, USA.
Why It Ranks: Historical leader in material sciences with deep integration into chemical supply chains.
Regional Dominance: Strong enterprise footprint across North America, Europe, and Asia-Pacific regions.
Product Line: DuPont Zonyl FSO, Zonyl FSN, Zonyl FSA, Zonyl FSP, DuPont Zonyl.
7. DIC Corporation
DIC formulates Megafac fluorinated surface modifiers specifically engineered for display panels and paints.
Founded: 1908 | HQ: Tokyo, Japan.
Why It Ranks: Premier supplier of specialized leveling agents to the electronic display sector.
Regional Dominance: Leading market presence across East Asian flat-panel display manufacturing hubs.
Product Line: Megafac F-477, Megafac F-554, Megafac F-556, Megafac F-563, Megafac F-570.
8. Archroma
Archroma designs high-efficiency fluorochemical wetting agents and repellent coatings for technical industrial fabrics.
Founded: 2013 | HQ: Reinach, Switzerland.
Why It Ranks: Leading specialist in sustainable specialty chemicals for textile and paper sectors.
Regional Dominance: Dominates European textile markets with growing operations in Southern Asia.
Product Line: Nuva N, Nuva TTC, Cartafix, Pekoflam, Arkophob.
9. Merck KGaA
Merck provides high-purity Tividida fluorosurfactants designed to optimize surface tension in display coatings.
Founded: 1668 | HQ: Darmstadt, Germany.
Why It Ranks: pioneer in high-value electronic chemicals and laboratory specialty materials.
Regional Dominance: Robust commercial footprint across Western Europe, North America, and East Asia.
Product Line: Tividida FL 2300, Tividida FL 2500, Tividida FL 3000, Tividida FL 2200.
10. Dynax Corporation
Dynax specializes in C6 fluorosurfactants specifically formulated for firefighting foam concentrate manufacturing.
Founded: 1991 | HQ: Pound Ridge, New York, USA.
Why It Ranks: Niche market leader in specialty firefighting foam additives and stabilizers.
Regional Dominance: Supplies major firefighting concentrate manufacturers across North America and Europe.
Product Line: DX4005N, DX4010N, DX5011, DX5022, DX1030.
Conclusion
The specialty chemical industry is still a critical part of the chemicals industry, with fluorosurfactants being one of the most important areas of the industry. Demand remains strong due to increased demand from electronics, paints and coatings, and specialty applications in firefighting. Under the strict regulations and compliance requirements, major players are making progress towards compliant short-chain C6 chemistries and other fluorinated technologies. Ongoing R&D will guarantee sustainable growth for industrial applications throughout the world.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


