
Oct 23, 2026
By Transpire Insight
Description
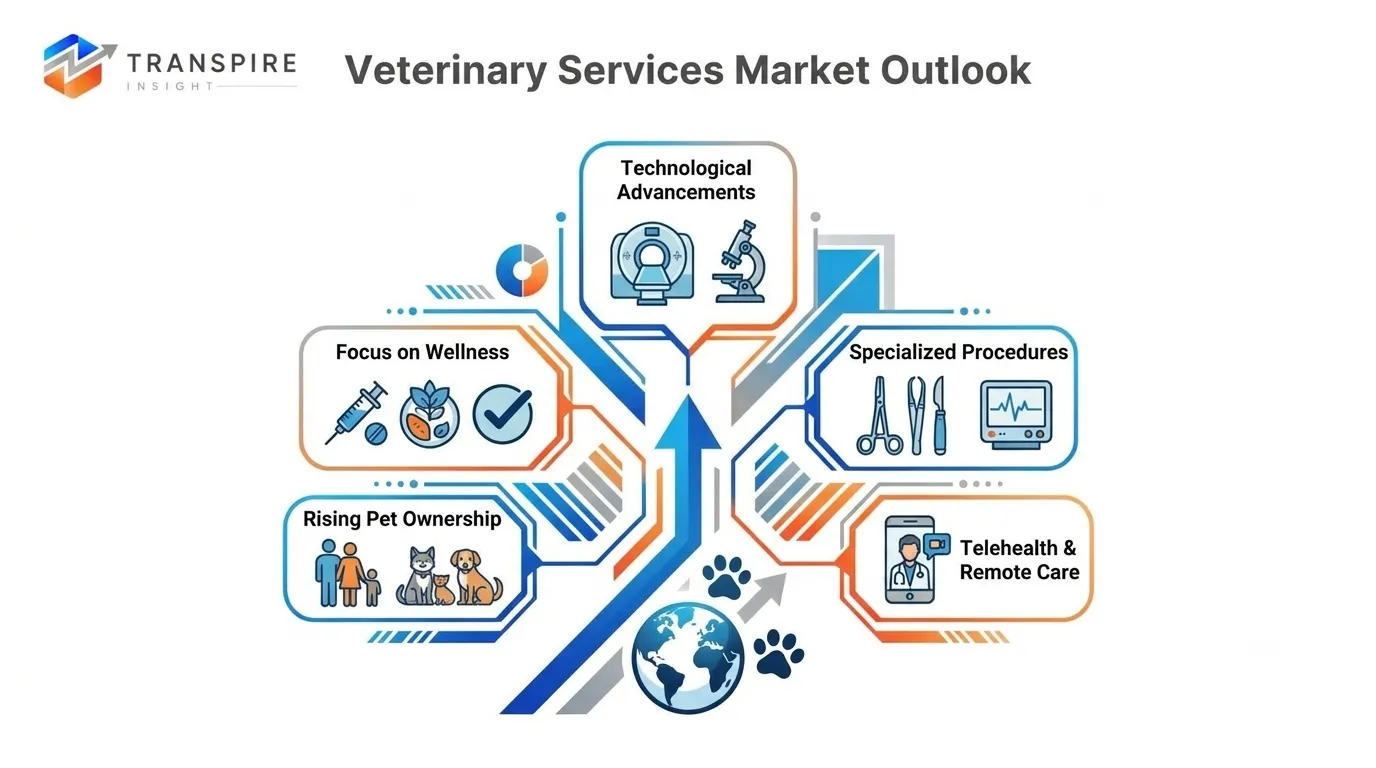
According to a research report published by Transpire Insight, the veterinary services market size is projected to grow from USD 174.97 billion in 2026 to USD 259.10 billion by 2035, at a 6.76% CAGR during the 2027-2035 forecast period. As pets become part of the family, animal health insurance coverage continues to expand, livestock consumption of protein continues to grow, and clinical innovations in diagnostics continue to advance, animal healthcare continues to grow in a sustained manner.
Introduction
Veterinary services are going through a major change globally as pets are getting humanized and industrial livestock demands are rising. The sector includes general wellness, emergency intervention, specialty surgery, and advanced diagnostic testing. The current trend towards the integration of technology and the various ways in which preventive healthcare is becoming more common are driving a trend of expansion of infrastructure to deliver comprehensive, life-cycle clinical care to companion animals and agricultural herds around the world.
Recent Development News
March 2026: Zoetis acquired the Animal Genomics business from Neogen to enhance precision livestock management and analytics, and its ability to predict animal health.
In March 2026, leading vet networks rushed to adopt AI-powered diagnostic imaging and automated administrative systems across the globe, enabling a faster transformation of their clinics.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Veterinary Services Market Size & Statistics
The Market Size for Veterinary Services Battery Was Estimated to be Worth USD 174.97 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 6.76% between 2026 and 2035.
The Veterinary Services Market Size is anticipated to reach USD 259.10 billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 38.2% of the veterinary services market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 7.4% in the veterinary services market.
Regional Growth and Demand Analysis by Transpire Insight
North America continues to be the demand anchor for veterinary services because pets are a part of the household's identity and expenditure. Chronic disease management and dental care are common expenses that owners make regularly. Owners regularly pay for dental care, chronic disease management, and diagnostics and surgery. Clinics like Mars Veterinary Health, which encompasses Banfield, VCA, and BluePearl clinics, provide heavy primary and specialty coverage for the area. Chewy has also been opening Chewy Vet Care Clinics throughout the United States, demonstrating the retail/ecommerce trend that is going into clinical care. As more pet owners have pet insurance, more are willing to pay for expensive care. More pet owners are adopting pet insurance, which expands their base of people willing to pay for higher-cost care.
Asia Pacific is the most dynamic region. Significant expansion can be expected with urbanization, increased disposable income, and increased awareness of animal healthcare services. China's chains like New Ruipeng Pet Healthcare are expanding hospital services to a rapidly increasing urban pet population. As India's first-time pet parents shift toward professional care, platforms like Supertails are establishing clinic networks and services. This is in addition to livestock demand, which is high because of the significant number of farms in the region that require disease control and food safety support. As Latin America continues to grow, the number of pets in the region is increasing in Brazil and Mexico, and chains of clinics and insurers are starting to expand.
Top 15 Trends in the Veterinary Services Market
Top 25 Companies Leading the Veterinary Services Market
1. Mars Veterinary Health
leader providing comprehensive hospital care through extensive clinical provider networks.
Founded: 1935 | HQ: McLean, Virginia, USA.
Why It Ranks: Commands top industry revenue share via network of corporate hospitals.
Regional Dominance: Holds leading corporate veterinary practice presence throughout North America and Europe.
Product Line: General practice, specialty veterinary care, emergency hospitals, and pet diagnostics.
2. IVC Evidensia
Premier international veterinary care group delivering primary and emergency animal care.
Founded: 2011 | HQ: Bristol, United Kingdom.
Why It Ranks: Controls significant market share through expansive European primary care clinic consolidations.
Regional Dominance: Maintains dominant market share and practice density across Western European nations.
Product Line: Small animal clinics, referral specialty centers, equine, and farm services.
3. National Veterinary Associates (NVA)
Leading network of compassionate general, specialty, and emergency veterinary hospital locations.
Founded: 1996 | HQ: Agoura Hills, California, USA.
Why It Ranks: Operates hundreds of premier specialty centers and emergency practices across continents.
Regional Dominance: Exerts primary market presence across suburban and urban United States locations.
Product Line: Specialty surgery, emergency care, general wellness clinics, and resort boarding.
4. VetCor
Fast-growing veterinary clinic aggregator focusing on community-centered local practice management.
Founded: 1997 | HQ: Hingham, Massachusetts, USA.
Why It Ranks: Consistently expands footprint by acquiring independent practices while retaining local branding.
Regional Dominance: Strong commercial penetration across North American community veterinary networks.
Product Line: Routine pet examinations, vaccinations, minor surgery, and dental preventive procedures.
5. PetVet Care Centers
High-growth network of specialty, emergency, and general companion animal hospitals.
Founded: 2012 | HQ: Westport, Connecticut, USA.
Why It Ranks: Focuses heavily on acquiring high-volume specialty and 24/7 emergency care facilities.
Regional Dominance: Deep market footprint distributed throughout major metropolitan areas in the United States.
Product Line: Advanced specialty care, emergency trauma intervention, and routine companion medicine.
6. Pets at Home Group PLC (Vets4Pets)
Integrated retail and clinical veterinary service provider offering accessible companion care.
Founded: 1991 | HQ: Handforth, United Kingdom.
Why It Ranks: Seamlessly pairs extensive retail presence with joint-venture veterinary practices.
Regional Dominance: Controls unmatched physical retail and practice footprint across the United Kingdom.
Product Line: Practice management, preventive health plans, routine surgeries, and pet retail.
7. Greencross Vets
Premier integrated pet care company operating clinical practices and emergency centers.
Founded: 1994 | HQ: Melbourne, Australia.
Why It Ranks: Leads domestic market through integrated veterinary clinics and specialty referral centers.
Regional Dominance: Holds position as the largest clinical veterinary operator across Australasia.
Product Line: Companion clinical services, animal rehabilitation, emergency medicine, and preventive care.
8. Zoetis Inc.
World's largest standalone animal health company developing innovative pharmaceuticals and vaccines.
Founded: 1952 | HQ: Parsippany, New Jersey, USA.
Why It Ranks: Generates massive revenues through breakthrough dermatology treatments and reference lab services.
Regional Dominance: Commands top commercial market share across North America and Latin America.
Product Line: Monoclonal antibodies, vaccines, parasiticides, livestock diagnostics, and software platforms.
9. Boehringer Ingelheim Animal Health
Family-owned pharmaceutical giant specializing in veterinary biologicals and preventative therapeutics.
Founded: 1885 | HQ: Ingelheim, Germany.
Why It Ranks: Globally renowned for producing market-leading flea, tick, and heartworm preventatives.
Regional Dominance: Anchors immense commercial authority across primary companion and livestock European markets.
Product Line: Antiparasitics, swine biologicals, equine therapeutics, and companion chronic disease drugs.
10. Merck Animal Health (MSD)
research-driven veterinary healthcare provider delivering advanced pharmaceutical and tech solutions.
Founded: 1891 | HQ: Rahway, New Jersey, USA.
Why It Ranks: Integrates high-volume vaccines with cutting-edge digital intelligence and identification technology.
Regional Dominance: Holds extensive distribution networks across North America, Europe, and Asia-Pacific.
Product Line: Livestock intelligence software, diabetes management, aquaculture solutions, and biosecurity vaccines.
Conclusion
There is still plenty of room for growth in the veterinary services market, as technology is being embraced and consumer preferences are evolving. Leaders in the marketplace are growing by making strategic acquisitions, digital integration, and sophisticated diagnostic rollouts, all while owners demand medical treatments fit for humans, and livestock managers focus on disease prevention. The sector is well poised to continue expanding in the future, elevating animal healthcare to an essential cornerstone of modern medicine globally.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


