
Oct 03, 2026
By Transpire Insight
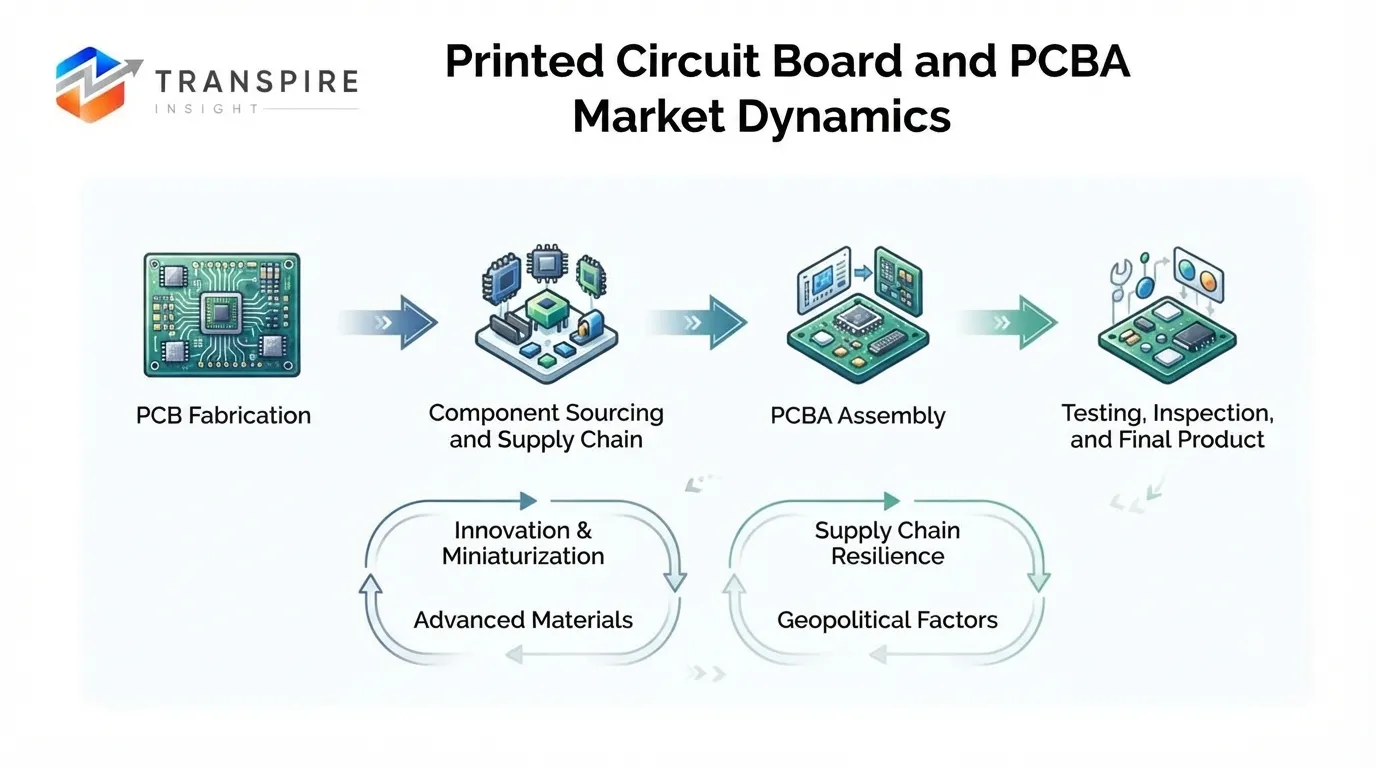
Description
According to a research report published by Transpire Insight, the printed circuit board and PCBA market size is projected to grow from USD 43.48 billion in 2026 to USD 67.10 billion by 2035, at a CAGR of 6.43% during the forecast period 2027-2035. Rapid EV adoption, the mushrooming of 5G infrastructure, the continued ramp-up of AI computing devices, and the miniaturization of smart consumer devices that demand high-density interconnect technology are driving market expansion.
Introduction
Printed Circuit Board (PCB) and Printed Circuit Board Assembly (PCBA) industry is the backbone of electronics manufacturing worldwide. PCBA's ability to combine complex circuitry and active components makes it suitable for consumer electronics, automotive systems, aerospace, and medical equipment. With the evolution of High-Density Interconnect (HDI), flexible substrates, and flexible Surface Mount Technology (SMT), the market is still growing to satisfy high-performance computing and microelectronics needs globally.
Recent Development News
February 2026: As high-layer-count HDI boards hit a significant shortage of supplies in AI server hardware architectures, leading PCB manufacturers revealed mega-facility expansions to meet the demand.
May 2026: The big players in the automotive industry completed their long-term supply contracts for next-generation rigid-flex PCB assemblies that will be used in high-voltage electric vehicle (EV) battery management systems.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Printed Circuit Board and PCBA Market Size & Statistics
The Market Size for Printed Circuit Board and PCBA Was Estimated to be Worth USD 43.48 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 6.43% between 2026 and 2035.
The Printed Circuit Board and PCBA Market Size is anticipated to reach USD 67.10 Billion by 2035.
Asia-Pacific is projected to drive the highest demand during the forecast period, accounting for 48.02% of the Printed Circuit Board and PCBA market.
North America is projected to grow the fastest during the forecast period at a CAGR of 6.8% in the Printed Circuit Board and PCBA market.
Regional Growth and Demand Analysis by Transpire Insight
Asia Pacific is leading due to its electronics manufacturing ecosystem, competitive electronics manufacturing costs, and government initiatives to promote domestic electronics manufacturing of semiconductors and PCBs. China is the one that drives the Asia-Pacific PCB market, accounting for 56.62% of the market in terms of output. AI servers, high-speed optical modules, and edge devices have boosted the market for higher-end boards, with its PCB industry investing over CNY70 billion (approx. US$10.3 billion) in this area. Taiwanese fabricators are also growing at a faster pace. The second phase expansion of Eiso Enterprise's Guishan factory has started, with the focus set on the AI and aerospace and defense industries. In the meantime, Zhen Ding and Taihong have shifted production to Thailand to minimise geopolitical risk. Among the emerging markets, India is the highlight. Its market share in the PCB industry is projected to grow at a 5.92% CAGR, and in iPhones, 1 out of 4 units is being manufactured domestically.
North America is the fastest-growing area. Demand for high-reliability products manufactured in the US is growing across a number of industries, including aerospace, defense, medical electronics, and data centers. Factory expansions are being driven by demand from the top five North American cloud providers, including Foxconn, Quanta, and Wistron. Regional policy is also working to shift the supply: US CHIPS and Science Act incentives and European sovereign-AI mandates are driving new fabs to North America and Central Europe. Sunshine PCB GmbH (Germany) bought Malaysia's Vision Industries to expand its microwave and high-frequency PCB business and presence in Southeast Asia.
Top 15 Trends in the Printed Circuit Board and PCBA Market
Hyperscale operators are deploying AI servers that need backplanes with many layers and advanced materials, pushing fabricators toward premium boards and heavy capacity investment globally.
High-density interconnect boards with microvias let designers pack more functions into smaller footprints, making them essential for smartphones, wearables, automotive modules, and computing devices.
Flexible and rigid-flex circuits bend, fold, and save weight, making them valuable for wearables, foldable phones, medical devices, and vehicle electronics in tight spaces.
Electric vehicles and driver assistance systems use far more electronic control units, sensors, and power modules, multiplying demand for reliable, heat-tolerant boards and assemblies.
Rollout of 5G base stations and high-speed networking gear requires low-loss laminates and precise impedance control, lifting demand for telecom boards and materials.
Tariff risks and policy incentives push electronics makers to build assembly capacity closer to customers, benefiting North America, Europe, and Southeast Asia while easing risk.
List of Top 25 Companies Leading the PCB and PCBA Market
1. Zhen Ding Tech Group
Holds the world's largest market share in flexible PCB manufacturing for smartphones.
Founded: 2006 | HQ: Taoyuan, Taiwan.
Why It Ranks: Unmatched operational scale and elite long-term supply integration with tech giants.
Regional Dominance: Dominates production across Taiwan and mainland China, exporting to markets.
Product Line: Flexible PCBs, rigid-flex boards, high-density interconnect (HDI) substrates, IC carrier boards, multi-layer PCBs, and surface-mount assembled circuit boards.
2. Unimicron Technology Corp.
World leader in advanced semiconductor substrate fabrication and high-density PCB solutions.
Founded: 1990 | HQ: Taoyuan, Taiwan.
Why It Ranks: Superior technical capabilities in manufacturing high-performance ABF substrates for artificial intelligence chips.
Regional Dominance: Strong presence in Taiwan, China, Germany, and key Asia-Pacific technology hubs.
Product Line: ABF substrates, BT substrates, high-density interconnect (HDI) boards, multi-layer PCBs, flexible printed circuits, and sub-assembly modules.
3. DSBJ (Suzhou Dongshan Precision Manufacturing)
Major Chinese supplier specializing in flexible printed circuits and precision electronic hardware.
Founded: 1980 | HQ: Suzhou, China.
Why It Ranks: Rapid expansion through strategic acquisitions, securing top-tier consumer electronics supply chains.
Regional Dominance: Dominates mainland China with expansive distribution networks across North America and Europe.
Product Line: Flexible printed circuits (FPC), rigid PCBs, LED display modules, precision metal components, and specialized PCBA solutions.
4. Nippon Mektron, Ltd.
Historical pioneer and market leader in flexible printed circuit design.
Founded: 1969 | HQ: Tokyo, Japan.
Why It Ranks: Exceptional material innovation and reliable FPC supply for automotive and mobile sectors.
Regional Dominance: Maintains a dominant operational presence across Japan, Southeast Asia, Europe, and the Americas.
Product Line: Ultra-thin flexible printed circuits, rigid-flex PCBs, automotive wiring modules, waterproof FPCs, and high-precision assemblies.
5. Compeq Manufacturing Co., Ltd.
Pioneered high-density interconnect technology for mobile devices and high-end consumer electronics.
Founded: 1973 | HQ: Taoyuan, Taiwan.
Why It Ranks: Dominant market position as a core supplier of HDI boards for top smartphone brands.
Regional Dominance: Operations centralized in Taiwan and mainland China, servicing international OEMs globally.
Product Line: HDI PCBs, multi-layer printed circuit boards, rigid-flex boards, system-in-package substrates, and high-frequency communication modules.
6. Tripod Technology Corp.
Leading manufacturer of memory module PCBs and high-layer server printed circuit boards.
Founded: 1991 | HQ: Taoyuan, Taiwan.
Why It Ranks: High production yield, cost efficiency, and massive capacity in memory and server boards.
Regional Dominance: Strong manufacturing footprint in China and Taiwan, supplying major cloud data centers.
Product Line: Heavy copper PCBs, memory module boards, server backplanes, automotive control PCBs, and multi-layer rigid boards.
7. Kingboard Holdings Limited
Vertical integration giant producing both raw laminates and finished printed circuit boards.
Founded: 1988 | HQ: Shatin, Hong Kong.
Why It Ranks: Unrivaled cost structure achieved by controlling raw material laminate production through finished PCBs.
Regional Dominance: Dominates Greater China, exporting laminates and circuit boards to over fifty countries.
Product Line: Copper clad laminates, glass epoxy laminates, single- and double-sided PCBs, multi-layer circuit boards, and chemical laminates.
8. TTM Technologies, Inc.
Leading Western manufacturer of mission-critical, high-reliability PCBs and complex RF components.
Founded: 1998 | HQ: Santa Ana, California, USA.
Why It Ranks: Premier partner for North American aerospace, defense, and high-speed networking industries.
Regional Dominance: Strong footprint across the United States, Canada, China, and various defense markets.
Product Line: Advanced HDI PCBs, high-frequency radar boards, rigid-flex circuits, custom defense assemblies, and backplane systems.
9. Shennan Circuits Co., Ltd.
Key Chinese manufacturer supporting 5G telecommunication infrastructure and high-performance server hardware.
Founded: 1984 | HQ: Shenzhen, China.
Why It Ranks: Deep technological integration with telecom giants for 5G antenna and base station boards.
Regional Dominance: Holds massive market share in mainland China, expanding rapidly into telecommunication networks.
Product Line: Telecom backplanes, semiconductor packaging substrates, high-density HDI boards, electronic sub-assemblies, and thermal management boards.
10. AT&S (Austria Technologie & Systemtechnik AG)
Europe’s top manufacturer of high-end printed circuit boards and IC substrates.
Founded: 1987 | HQ: Leoben, Austria.
Why It Ranks: Technological leadership in substrate packaging for high-performance computing, medical, and mobile devices.
Regional Dominance: Commands the European market with state-of-the-art production plants in Austria, China, and Malaysia.
Product Line: Integrated circuit substrates, HDI circuit boards, embedded component packaging, flexible PCBs, and medical diagnostic assemblies.
Conclusion
Printed Circuit Board (PCB) and Printed Circuit Board Assembly (PCBA) are an important part of the technological ecosystem. Demand for more complex designs of HDI and flexible substrates keeps rising across electric vehicles, artificial intelligence, 5G networking, and smart automation. With industry leaders continuing to increase production capacity and invest in innovative manufacturing automation, the industry is poised for continued innovation, greater functional density, and solid potential growth in the long term, globally.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


