
Oct 15, 2026
By Transpire Insight
Description
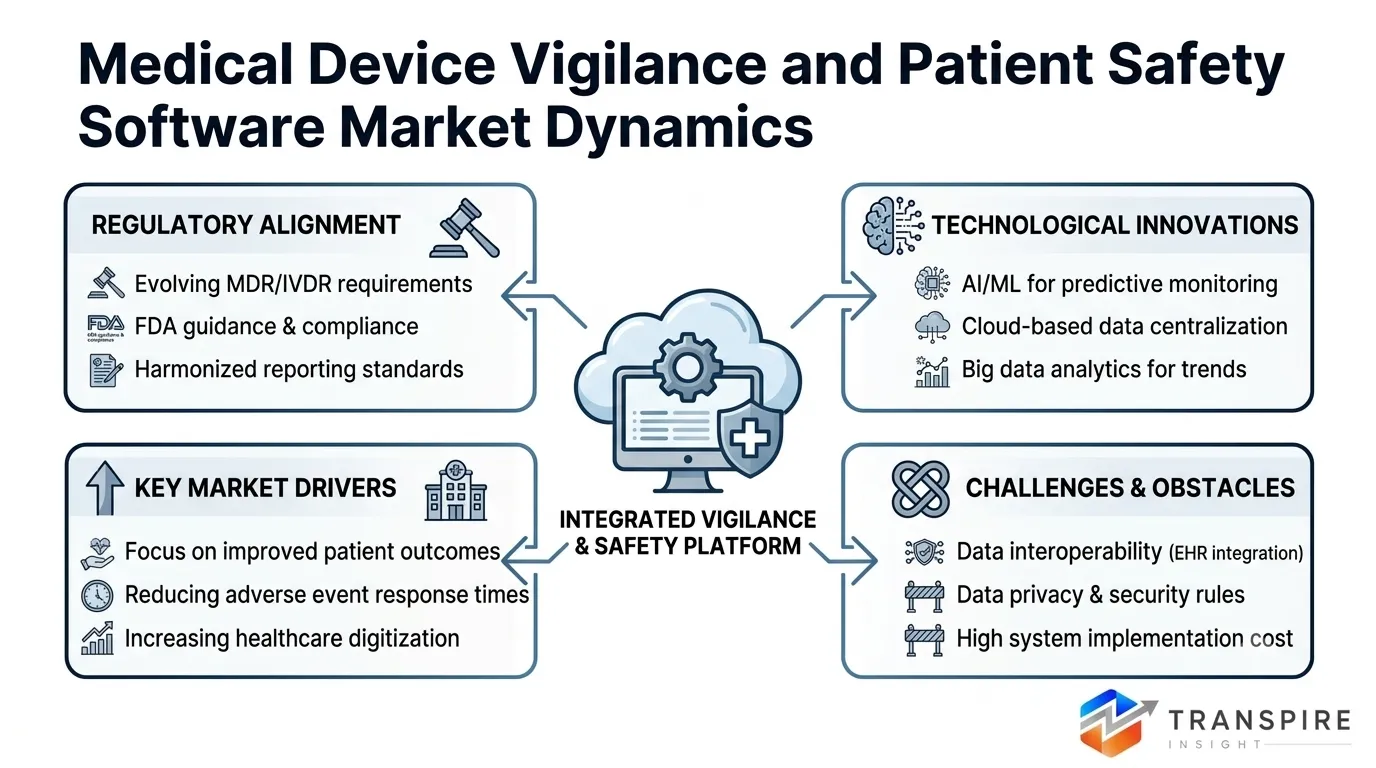
According to a research report published by Transpire Insight, the medical device vigilance and patient safety software market size is projected to grow from USD 1.85 billion in 2026 to USD 4.25 billion by 2035, at a CAGR of 11.60% during the forecast period 2027-2035. The rapid adoption of device vigilance and safety software around the world is being propelled by strict post-market surveillance regulations, the growth of AI-approved devices, mandatory adverse event reporting, and cloud-based risk automation.
Introduction
For healthcare technology companies and healthcare providers, Medical Device Vigilance and Patient Safety Software is a crucial compliance solution. These enterprise platforms enable the rapid tracking of adverse events, automated regulatory submission, detection of adverse event signals, and clinical risk mitigation. Vigilance software that incorporates Artificial Intelligence and Cloud tools enables 24/7 post-market surveillance, patient safety, and minimises serious device recalls in various worldwide regulatory regions.
Recent Development News
February 2026: The U.S. FDA approved more than 1,350 medical devices powered by AI, driving a surge in the demand for automated materiovigilance and cloud-based adverse event monitoring systems.
March 2026: The European Commission adopted a Delegated Regulation updating MDR (EU 2017/745) post-market requirements and updated ISO 14155:2026 clinical standards for Software as a Medical Device (SaMD).
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Medical Device Vigilance and Patient Safety Software Market Size & Statistics
The Market Size for Medical Device Vigilance and Patient Safety Software Was Estimated to be Worth USD 30.3 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 7.12% between 2026 and 2035.
The Medical Device Vigilance and Patient Safety Software Market Size is anticipated to reach USD 42.82 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 38.2% of the medical device vigilance and patient safety software market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 8.9% in the medical device vigilance and patient safety software market.
Regional Growth and Demand Analysis by Transpire Insight
North America leads because it pairs the strictest post-market reporting obligations with the densest concentration of device manufacturers. North America is the leader, having the most rigorous post-market reporting requirements and the largest number of device manufacturers. Europe follows closely. The European Commission has introduced the first four EUDAMED modules as mandatory from 28th May, with the vigilance module still to be implemented. Manufacturers are already developing workflows for the incidents.
Asia Pacific is the fastest-growing region. The regulators are aggressively monitoring the devices, and India's Materiovigilance Programme is encouraging hospitals and manufacturers to report adverse events in a structured manner. Adverse event reporting is also improving in the region, with device manufacturers establishing manufacturing plants in the region, leading to an increased demand for vigilance software. Cloud-based solutions work well for these markets since they enable multinationals to handle safety cases across multiple regulatory regions from a single platform, without investments in heavy on-premises solutions.
Top 15 Trends in the Medical Device Vigilance and Patient Safety Software Market
Machine learning models scan complaints, literature, and device logs to flag serious incidents faster, cutting manual review effort and helping manufacturers meet regulatory reporting timelines.
Manufacturers are shifting from on-premises tools to cloud platforms that offer faster deployment, scalable case handling, remote access, and easier regulatory updates across multiple markets.
The European Commission made four EUDAMED modules mandatory, pushing manufacturers to adopt software that structures device, actor, and incident data for the pending vigilance module.
Vigilance platforms increasingly pull registry, claims, and electronic health record data into post-market surveillance, giving safety teams broader signals beyond spontaneous complaints and incident reports.
Predictive analytics models trend complaint and adverse event data to spot emerging failure patterns, allowing manufacturers to launch corrective actions before issues escalate into recalls.
Asia Pacific regulators are strengthening device oversight, and programs like India's Materiovigilance Programme are pushing manufacturers and hospitals toward structured reporting software for adverse events.
List of Top 25 Companies Leading Medical Device Vigilance and Patient Safety Software
1. IQVIA
Comprehensive software ecosystem powering pharmacovigilance and device compliance.
Founded: 1982 | HQ: Durham, North Carolina, USA.
Why It Ranks: Market leadership in human data science and end-to-end device surveillance.
Regional Dominance: Strongest presence across North America and key European healthcare markets.
Product Line: IQVIA SmartSolve and Connected Intelligence vigilance suites for post-market safety.
2. Oracle Health
Enterprise cloud architecture providing high-scale automated adverse event reporting platforms.
Founded: 1977 | HQ: Austin, Texas, USA.
Why It Ranks: Unmatched database infrastructure powering safety signal detection and compliance.
Regional Dominance: reach with massive enterprise footprints in North America and Europe.
Product Line: Oracle Argus Safety and Health Sciences Data Management Workbench platforms.
3. Veeva Systems
Cloud software pioneer transforming life sciences regulatory and post-market safety operations.
Founded: 2007 | HQ: Pleasanton, California, USA.
Why It Ranks: High adoption rate of unified cloud quality and safety platforms globally.
Regional Dominance: Rapid expansion across North America, Europe, and Asia-Pacific life sciences.
Product Line: Veeva Vault Safety and Vault Quality suite for device manufacturers.
4. RLDatix
Specialized healthcare provider software focused on clinical risk management and patient safety.
Founded: 2001 | HQ: Chicago, Illinois, USA.
Why It Ranks: Deep market penetration across hospital systems for incident reporting workflows.
Regional Dominance: Dominates healthcare facility governance in North America and the United Kingdom.
Product Line: RLDatix Safety, Governance, Risk, and Compliance (GRC) enterprise software platforms.
5. ArisGlobal
Automated life sciences technology provider transforming drug and device safety management.
Founded: 1987 | HQ: Miami, Florida, USA.
Why It Ranks: Cutting-edge AI-driven adverse event processing, reducing manual compliance efforts significantly.
Regional Dominance: Widespread enterprise adoption across North America, Europe, and India.
Product Line: LifeSphere Safety and LifeSphere Quality end-to-end safety technology solutions.
6. Riskonnect
Integrated risk management platform vendor protecting enterprise operations and patient safety.
Founded: 2007 | HQ: Atlanta, Georgia, USA.
Why It Ranks: Exceptional capabilities in unifying clinical risk tracking with overall operational safety.
Regional Dominance: Strong foothold in North American hospital networks and risk organizations.
Product Line: Riskonnect Healthcare Patient Safety and Enterprise Risk Management platform solutions.
7. Health Catalyst
Data and analytics software platform enabling performance improvement across healthcare entities.
Founded: 2008 | HQ: South Jordan, Utah, USA.
Why It Ranks: Advanced clinical data analytics accelerating adverse event detection and prevention.
Regional Dominance: Widespread implementation across major United States healthcare and hospital systems.
Product Line: Patient Safety Incident Reporting Module and Health Catalyst Data Operating System.
8. Origami Risk
Multi-tenant SaaS provider delivering risk management, safety, and compliance technology solutions.
Founded: 2009 | HQ: Chicago, Illinois, USA.
Why It Ranks: Modular cloud platform allowing highly customizable patient incident tracking configuration.
Regional Dominance: Dominant enterprise market position within North American health system networks.
Product Line: Origami Healthcare Risk Management and Quality Improvement incident management suites.
9. Sparta Systems (Honeywell)
Quality management software vendor ensuring stringent device compliance and risk controls.
Founded: 1994 | HQ: Hamilton, New Jersey, USA.
Why It Ranks: Industrial-grade quality software integrated directly into the medical manufacturing supply chain.
Regional Dominance: Broad multinational presence across North America, Europe, and Asia regions.
Product Line: TrackWise Digital and TrackWise Enterprise Quality Management System software solutions.
10. MasterControl
SaaS quality management provider powering compliance workflows for medical device companies.
Founded: 1993 | HQ: Salt Lake City, Utah, USA.
Why It Ranks: User-friendly regulatory cloud platforms tailored specifically for emerging medical tech.
Regional Dominance: Strong commercial penetration across North America, Europe, and Asia-Pacific hubs.
Product Line: MasterControl Quality Excellence and Manufacturing Excellence post-market surveillance solutions.
Conclusion
With the rise of AI-powered software and connected hardware in healthcare, medical device vigilance platforms are no longer just about regulatory duties, but also about being a predictive patient safety engine. New and increasingly demanding post-market regulations push manufacturers to embrace uniform cloud platforms. Companies that embrace automated risk detection, real-world monitoring, and streamlined safety reporting will experience reduced product recalls, maintain enterprise goodwill, and ensure improved clinical outcomes.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


