
Oct 03, 2026
By Transpire Insight
Description
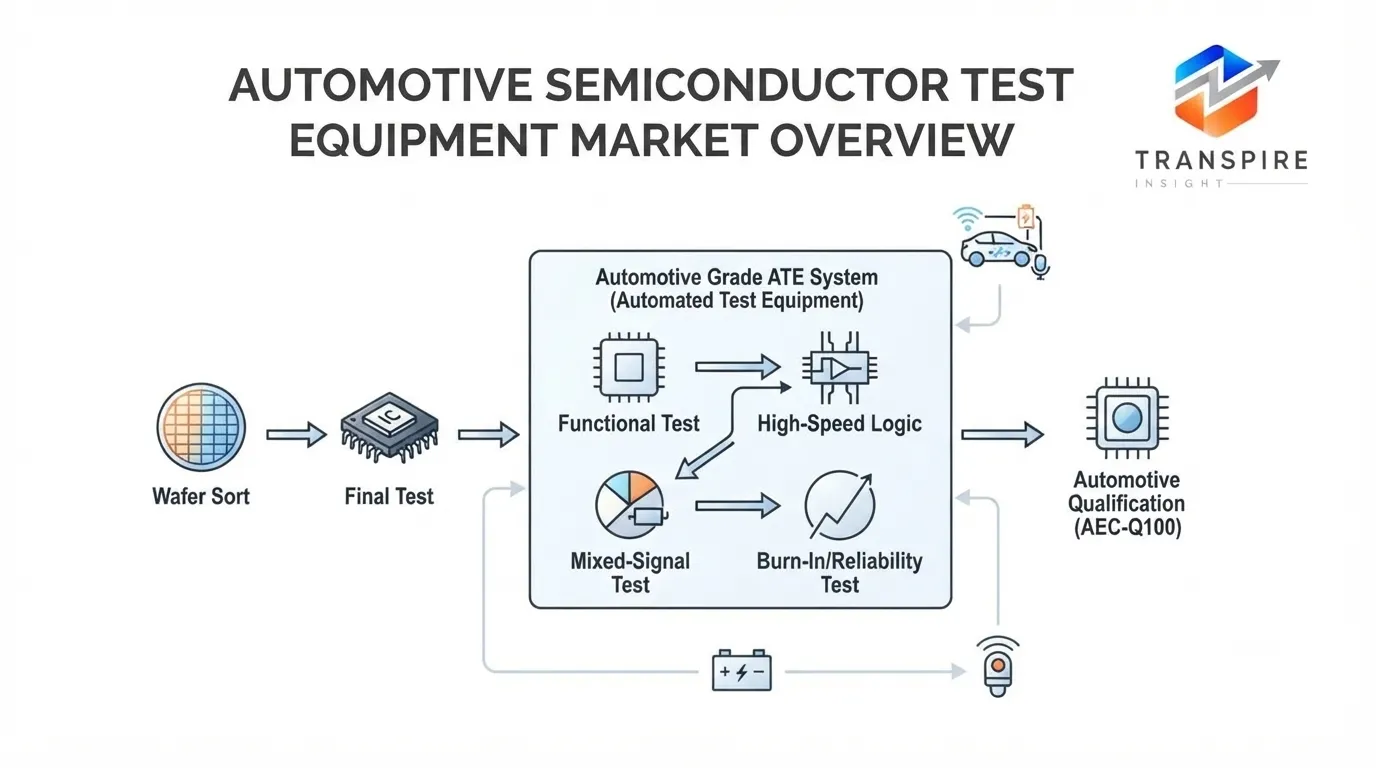
According to a research report published by Transpire Insight, the automotive semiconductor test equipment market size is projected to grow from USD 3.9 billion in 2026 to USD 6.12 billion by 2035, at a CAGR of 2.91% during the forecast period 2027-2035. Automotive chips are facing stringent zero-defect quality and yield testing demands due to rapid vehicle electrification, the growing number of Advanced Driver Assistance Systems (ADAS), and the transition to software-defined vehicles.
Introduction
As the automotive industry makes the move towards becoming a complex electronic node, the automotive semiconductor test equipment market is growing significantly. Power modules made of silicon carbide (SiC) or gallium nitride (GaN), automotive radar systems, microcontrollers, and domain controllers are examples of safety-critical applications that need to meet high reliability requirements and must be tested using automated test equipment (ATE) with zero-defect tolerances. Specialized wafer probers, handlers, and functional testers are offered by test equipment manufacturers to ensure no end-user operational failures.
Recent Development News
July 2026: National Instruments added new Prompt-Based Test Sequence Generation for TestStand to its suite of tools for Nigel AI to speed up the validation of complex automotive semiconductor testing.
June 2026: National Instruments introduced the modular PXIe 1480 FlexRIO platform specifically for deterministic SerDes testing on high-resolution automotive cameras and displays.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Automotive Semiconductor Test Equipment Market Size & Statistics
The Market Size for Automotive Semiconductor Test Equipment Was Estimated to be Worth USD 3.9 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 2.91% between 2026 and 2035.
The Automotive Semiconductor Test Equipment Market Size is anticipated to reach USD 6.12 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 38.23% of the automotive semiconductor test equipment market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 12% in the automotive semiconductor test equipment market.
Regional Growth and Demand Analysis by Transpire Insight
North America is projected to dominate the revenue mix as it has a strong presence at advanced nodes and strong government initiatives. A total of more than USD 130 billion is being made available to the semiconductor industry through funding programs like the U.S. CHIPS Act and the European Chips Act. In automotive, where zero-defect standards are required, test equipment leaders Teradyne and Advantest get rid of the compromises of conventional test equipment. Qualcomm's partnership with BMW and Mercedes focuses on generating USD 4 billion in automotive revenue, in addition to chip validation for automotive use. All these factors combine to make North America the revenue leader, despite the increase in production being made in Asia.
The Asia-Pacific region is projected to witness the fastest growth due to the growth of semiconductor manufacturing, increase in demand for EVs, government initiatives, and automotive electronics manufacturing. There are 180 of the 300 high-volume fabs in Taiwan, South Korea, and mainland China, thus consolidating test equipment installations in the region. The semiconductor usage in vehicles is increasing from USD 600 to USD 2,000 as the number of vehicles goes up and automobile tier-1 suppliers are the fastest growing buyers for test equipment. Under supportive government policies and localization incentives, China, Japan, and India are ramping up semiconductor manufacturing. The automotive end-use market is expected to see the highest growth in semiconductor test equipment, with the volume of EVs being produced increasing rapidly, and the number of ADAS and autonomous driving systems on the rise.
Top 15 Trends in the Automotive Semiconductor Test Equipment Market
List of Top 25 Companies Leading the Automotive Semiconductor Test Equipment Market
1. Advantest Corporation
leader delivering high-throughput automated test equipment for advanced automotive microcontrollers.
Founded: 1954 | HQ: Tokyo, Japan
Why It Ranks: Holds the largest market share in semiconductor automated test equipment.
Regional Dominance: Strongest market footprint and revenue generation across the Asia-Pacific region.
Product Line: V93000 SoC test platform and high-density EVA100 measurement systems.
2. Teradyne, Inc.
Pioneer in high-speed, multi-site ATE platforms designed for power and ICs.
Founded: 1960 | HQ: North Reading, Massachusetts, USA
Why It Ranks: Dominates linear, automotive analog, and mixed-signal semiconductor automated test solutions.
Regional Dominance: Dominant enterprise footprint throughout North America and major Asian chip hubs.
Product Line: FLEX Test System family and ETS-88 high-power semiconductor testing series.
3. Cohu, Inc.
Specializes in thermal inspection, probe heads, and test handlers for automotive.
Founded: 1947 | HQ: Poway, California, USA
Why It Ranks: Unrivaled integration of automotive IC handling, thermal management, and contactors.
Regional Dominance: Highly influential presence in European automotive supply chains and Asian fabs.
Product Line: Diamondx ATE systems, Matrix handler systems, and xArray thermal contactors.
4. Keysight Technologies, Inc.
Offers high-frequency, precision electronic design and test instrumentation for automotive chips.
Founded: 2014 (Keysight) / 1939 (HP) | HQ: Santa Rosa, California, USA
Why It Ranks: Industry standard for automotive radar, RF, and power semiconductor test.
Regional Dominance: Widespread adoption across North America, Western Europe, and key Asian markets.
Product Line: PathWave software suite, dynamic power device analyzers, and radar target simulators.
5. FormFactor, Inc.
Leading provider of advanced wafer probe cards used in automotive testing.
Founded: 1993 | HQ: Livermore, California, USA
Why It Ranks: Top supplier of high-reliability wafer-level probing cards and systems.
Regional Dominance: Strong penetration in major semiconductor foundries across Taiwan, US, and Korea.
Product Line: Katana silicon photonics probe cards and Apollo MEMS wafer test cards.
6. National Instruments (Emerson Electric)
Modular test leader providing PXI platforms for automotive electronics and silicon.
Founded: 1976 | HQ: Austin, Texas, USA
Why It Ranks: Premier provider of software-defined, modular test hardware across automotive workflows.
Regional Dominance: Broad market penetration across North American and European OEM ecosystems.
Product Line: LabVIEW environment, PXIe test chassis, and Semiconductor Test System (STS).
7. Chroma ATE Inc.
Specialist in high-power test instrumentation tailored for electric vehicle power devices.
Founded: 1984 | HQ: Taoyuan City, Taiwan
Why It Ranks: Key innovator in testing wide-bandgap SiC and GaN automotive power devices.
Regional Dominance: Deep footprint in Greater China, Japan, and expanding Southeast Asian regions.
Product Line: Chroma 3650-S ATE, dynamic burn-in systems, and power IC testers.
8. SPEA S.p.A.
Designs automatic test equipment for automotive microelectromechanical systems (MEMS) and sensors.
Founded: 1976 | HQ: Volpiano, Turin, Italy
Why It Ranks: Exceptional capabilities in multi-physics MEMS sensor testing for automotive safety.
Regional Dominance: Exceptional market share within European automotive tier-1 suppliers and chipmakers.
Product Line: SPEA DOT 800 semiconductor tester and MEMS inertial sensor handling systems.
9. Tokyo Electron Limited (TEL)
leader in automated wafer probers crucial for automotive semiconductor validation.
Founded: 1963 | HQ: Tokyo, Japan
Why It Ranks: Key enabler of high-precision temperature-controlled wafer probing for automotive chips.
Regional Dominance: Massive market position across Japan, South Korea, Taiwan, and Mainland China.
Product Line: TEL PREMIO and Tactras automated high-temperature wafer prober equipment series.
10. LTX-Credence (Xcerra / Cohu)
Historic ATE pioneer integrated into Cohu to deliver robust mixed-signal testing.
Founded: 1976 | HQ: Poway, California, USA
Why It Ranks: Reliable foundation in microcontrollers, SoC, and automotive power management testing.
Regional Dominance: Broad presence leveraging Cohu's international field support network.
Product Line: PAx Series testers and X-Series architecture for cost-effective automotive testing.
Conclusion
The automotive semiconductor test equipment market plays a crucial role in the safety, efficiency, and reliability of vehicles. The high-throughput, multi-site automated testing equipment will also continue to grow in demand as EV architectures, autonomous driving technologies, and advanced packaging continue to expand. The key players continue to have a competitive advantage in terms of their ability to capture the long-term growth in the market, owing to their expansion of AI-powered software suites and modular high-temperature testing.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


