
Sep 10, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the automotive vents market size is projected to grow from USD 1.58 billion in 2026 to USD 2.50 billion by 2035, at a CAGR of 5.44% during the forecast period 2027-2035. The automotive vents market is expected to grow at a faster pace with the rise in electric vehicle production, the rise in automotive electronics integration, increased demand for ingress protection rating of IP67/IP68, and strict thermal management requirements for the EV battery packs worldwide.
Introduction
Automotive vents are an integral part of the market dedicated to engineered venting solutions for sensitive electronics, lighting, drive units, and battery systems facing the threat of moisture, pressure changes, and environmental contaminants. The automotive industry has undergone a swift transformation towards EVs and autonomous driving systems, making reliable pressure equalization and thermal management crucial. The cars use innovative micro-venting systems and ePTFE membrane technologies to ensure durability and compliance with regulations over the long-term.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Automotive Vents Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
Asia Pacific's leadership rests on sheer production scale rather than any single technology shift. China, Japan, South Korea, and India together anchor regional demand, and China's accelerating battery-electric vehicle rollout is compounding vent requirements by introducing battery-specific venting needs across an unmatched volume of unit output. China's accelerating BEV platform rollout further compounds vent demand by introducing battery-specific venting requirements across a high-volume production base that no other region matches in absolute unit output. North America's rapid ascent, meanwhile, is being driven by strong consumer demand for comfort, safety, and performance, backed by a research-rich innovation ecosystem where suppliers, OEMs, and technology firms collaborate closely to introduce lightweight, aerodynamic vent components. Growth in North America is being driven by robust consumer demand for comfort, safety, and performance, as well as by a vibrant innovation ecosystem that supports the integration of advanced ventilation solutions into next-generation vehicles. Strong research infrastructure and collaborative networks between suppliers, OEMs, and technology firms in the region accelerate the introduction of lightweight, aerodynamic vent components.
North America's momentum, by contrast, is being driven less by production volume and more by electronics depth. The region benefits from strong semiconductor design capability and a rapidly expanding base of automotive, aerospace, and industrial R&D centres, pushing OEMs toward higher-complexity, sensor-rich door control units. Continental has led this shift with broad OEM partnerships across the region, while a vehicle fleet exceeding 290 million units continues to support elevated average selling prices for connected and luxury-oriented door features. Bosch has extended the same logic globally, expanding its Vehicle Motion Management portfolio to fold door control, braking, and steering into one centralized, software-defined architecture, enabling personalised entry experiences that North American OEMs are increasingly adopting first.
Top 15 Trends in the Automotive Vents Market
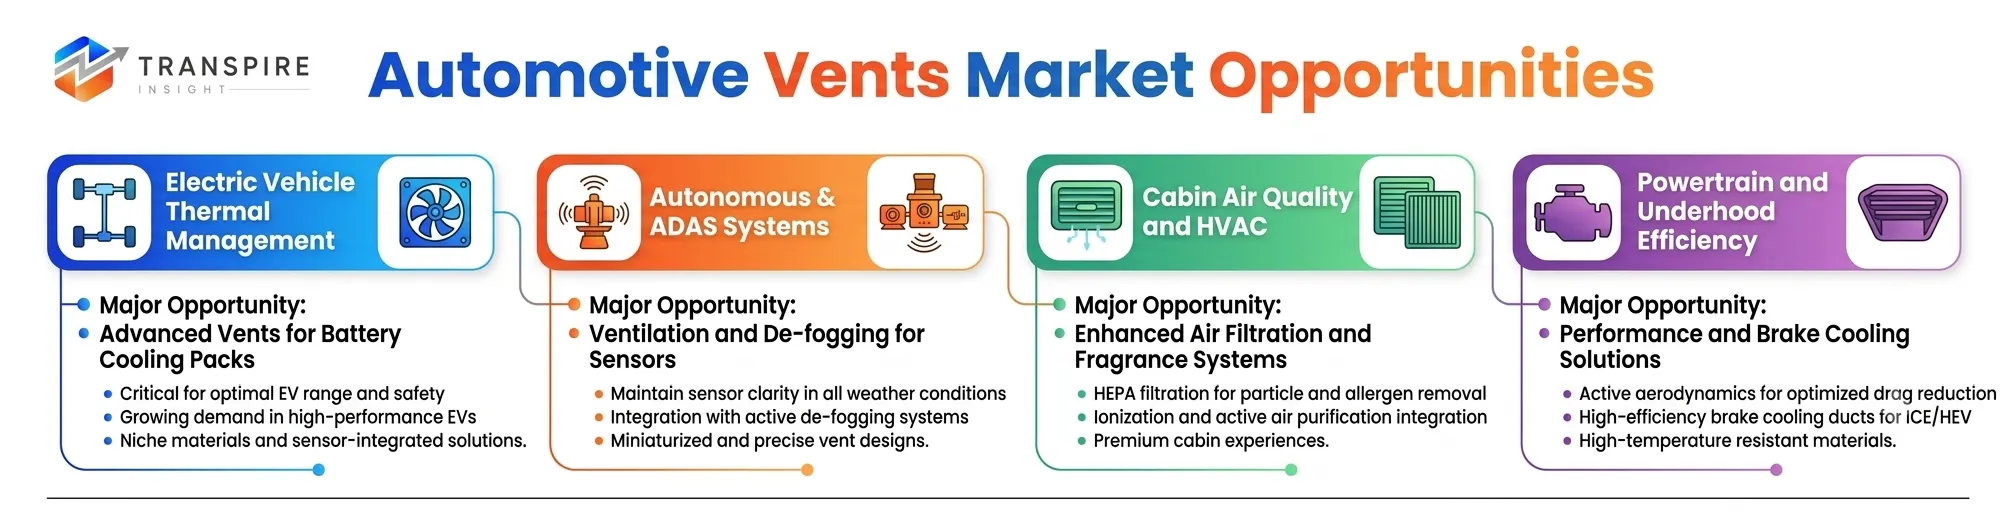
EV Battery Thermal Venting Demand Rising
Electric vehicle batteries generate heat and gas during operation, pushing manufacturers to develop pressure-management venting solutions that prevent thermal buildup and maintain safe battery performance.
Intelligent, Sensor-Linked Air Vents Growing
ADAS components like LiDAR and cameras generate heat, prompting OEMs to deploy active vent networks with temperature sensors that release thermal loads automatically.
PTFE Membrane Vents Gaining Share
Polytetrafluoroethylene remains the leading vent material due to superior chemical resistance and membrane-grade filtration, outperforming polypropylene and polyethylene in demanding automotive environments.
Exhaust Vents Growing Fastest Among Types
Stringent emission regulations and the shift toward electrified powertrains are driving demand for efficient under-hood air evacuation, making exhaust vents the fastest-expanding vent type.
Research-Driven Innovation Clusters in North America
Strong research infrastructure and close collaboration between suppliers, OEMs, and technology firms in North America accelerate development of lightweight, aerodynamic, next-generation vent components.
Fuel-Efficiency Regulations Boosting Airflow Tech
Growing regulatory pressure around fuel efficiency and emissions is rapidly boosting demand for optimized airflow technologies, particularly across North America's advanced automotive manufacturing base.
List of Top 25 Companies Leading the Automotive Vents Market
market leader pioneering ePTFE membrane technology for critical protective venting applications.
Founded: 1958 | HQ: Newark, Delaware, USA.
Why It Ranks: Unrivaled technical expertise and dominant market share in EV battery vents.
Regional Dominance: Strong presence across North America, Europe, and rapidly expanding in Asia-Pacific.
Product Line: GORE Automotive Vents, ePTFE membranes, electronic enclosure vents, battery pressure relief vents.
Major filtration titan offering advanced protective venting solutions for vehicle powertrains.
Founded: 1915 | HQ: Bloomington, Minnesota, USA.
Why It Ranks: Robust distribution and cutting-edge research in micro-ventilation filtration technologies.
Regional Dominance: Extensive operations and market share leadership throughout North America and Europe.
Product Line: Snap-fit vents, weldable vents, powertrain vents, hydrophobic and oleophobic protective membranes.
Japanese materials leader manufacturing high-durability Temish porous polymer venting components.
Founded: 1918 | HQ: Osaka, Japan.
Why It Ranks: Exceptional material innovation and supply partnerships with top Asian vehicle OEMs.
Regional Dominance: Dominant footprint across Japan, China, and the broader Asia-Pacific region.
Product Line: TEMISH venting materials, automotive pressure vents, waterproof breathable caps, ECU vents.
Motion control giant providing specialized sealing and environmental venting components.
Founded: 1917 | HQ: Cleveland, Ohio, USA.
Why It Ranks: Deep integration across automotive OEM engineering supply chains and advanced materials.
Regional Dominance: Strong industrial foothold across North America and Western European markets.
Product Line: Engineered sealing vents, thermal management vents, custom automotive enclosure protection systems.
Premier automotive filtration specialist engineering high-performance venting modules for OEMs.
Founded: 1941 | HQ: Ludwigsburg, Germany.
Why It Ranks: Extensive Tier-1 OEM partnerships and strong R&D in automotive fluid management.
Regional Dominance: Leading market presence across European automakers and growing North American footprint.
Product Line: Crankcase ventilation systems, air vent caps, EV battery degassing valve assemblies.
Specialty component maker crafting innovative plastic fasteners and functional venting hardware.
Founded: 1912 | HQ: Glenview, Illinois, USA.
Why It Ranks: High-volume production capabilities and customized engineering for top OEM platforms.
Regional Dominance: Strong manufacturing network across North America, Europe, and East Asia.
Product Line: Direct-fit automotive vents, pressure relief valves, powertrain breather caps, fastener vents.
Porous polymer innovator engineering customized porous plastic automotive venting products.
Founded: 1961 | HQ: Fairburn, Georgia, USA.
Why It Ranks: Proprietary porous technology offering superior airflow and liquid barrier functional performance.
Regional Dominance: Strategic presence across North American, European, and Asian manufacturing centers.
Product Line: Porous PTFE vents, sensor protection vents, headlamp vents, acoustic venting media.
Japanese automotive supplier specializing in high-precision plastic components and vent valves.
Founded: 1967 | HQ: Yokosuka, Japan.
Why It Ranks: Key Tier-1 provider of lightweight plastic functional parts to major automakers.
Regional Dominance: Massive market presence and supply chains across Asia-Pacific and North America.
Product Line: Fuel tank vent valves, cabin pressure equalization vents, plastic vent fasteners.
Major Toyota Group member delivering advanced rubber and functional plastic automotive vents.
Founded: 1949 | HQ: Kiyosu, Japan.
Why It Ranks: Deep integration with Japanese OEMs and leader in interior functional components.
Regional Dominance: Widespread manufacturing leadership in Japan, Southeast Asia, and North America.
Product Line: Automotive air register vents, interior duct vents, environmental sealing and pressure vents.
Electronics giant supplying protective vents for automotive sensors and electronic control units.
Founded: 1932 | HQ: Wallingford, Connecticut, USA.
Why It Ranks: Essential provider of protective venting solutions for connected and autonomous vehicle sensors.
Regional Dominance: footprint with significant operations in North America, Europe, and China.
Product Line: Hermetic pressure vents, sensor enclosure vents, IP68-rated electrical protective vents.
Conclusion
With the integration of vehicle electrification and advanced electronic systems, the automotive vents industry is experiencing a pivotal shift. With a focus on IP-rated ingress protection and emergency battery degassing, membrane technologies such as ePTFE are essential. Leading international suppliers are further expanding their operations in emerging markets such as Asia-Pacific. Leading suppliers keep on expanding their presence in high-growth markets, such as Asia-Pacific. High-flow venting solutions will continue to play an important role in providing long-term reliability in vehicles, component safety, and structural performance.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


