
Aug 19, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the automotive advanced technologies market size is projected to grow from USD 397.29 billion in 2026 to USD 958.20 billion by 2035, at a CAGR of 18.80% during the forecast period 2026-2035. Accelerating adoption of electric power, rapid growth of software-defined architectures, strict safety regulations, and rising consumer demand for AI-driven in-cabin intelligence drive market expansion.
Introduction
The automotive advanced technologies market is undergoing a fundamental transformation toward smart, connected, and sustainable mobility. Automakers are aggressively shifting from traditional hardware manufacturing to software-defined vehicle platforms. High-performance computing, advanced sensors, artificial intelligence, and next-generation electric powertrains are becoming standard components of modern vehicles. These technological advancements enhance road safety, improve battery efficiency, enable autonomous driving features, and create subscription-based digital revenues, forever changing how consumers interact with their vehicles.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Automotive Advanced Technologies Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Automotive Advanced Technologies Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America is estimated to generate the highest demand during the forecast period, holding a market share of 34% by 2026 in the Automotive Advanced Technologies market. Leading demand for advanced automotive technologies remains concentrated in North America, led by U.S. automakers and Tier-1 suppliers. The region is seeing strong momentum, supported by early investments in ADAS, autonomous driving pilots, and collision-avoidance systems by legacy OEMs and EV players, a mature industrial ecosystem capable of rapidly scaling connected-vehicle and safety-tech rollouts, and a robust regulatory push toward mandatory safety features like automatic emergency braking and lane-keeping assist. As automakers in the region increasingly embed AI, sensors, and software into core vehicle architecture rather than treating it as an add-on, they are seeking suppliers that offer tight integration with existing production lines, faster time-to-market, and dependable support for high-volume passenger and commercial vehicle output. The most visible use cases are ADAS and predictive safety systems in passenger cars and light commercial vehicles, where they directly reduce collision rates and improve regulatory compliance. North America's advanced-technology adoption is more mature compared to faster-growing emerging markets, but steady demand will be sustained by high consumer purchasing power and a strong base of software and semiconductor talent.
Asia-Pacific is projected to be the fastest-growing region during the forecast period in the Automotive Advanced Technologies market. Asia-Pacific's growth is anchored by China, Japan, South Korea, and India, which together are shaping the next phase of advanced automotive technology adoption. China leads the region in scale, with a heavy focus on electrification, connectivity, and autonomous-driving features across its high-volume passenger vehicle and EV production base, aided by strong export-oriented manufacturing. India's rapid industrial digitization and expanding domestic vehicle demand are turning it into one of the fastest-growing markets globally for advanced safety and connectivity systems. Japan and South Korea continue to focus on sensor technology, robotics-driven manufacturing, and AI-based driver-assistance innovation, reflecting their advanced automotive engineering base. Cost-sensitive, high-volume East Asian markets are accelerating adoption of ADAS and electrified drivetrains for efficiency and safety gains, while more affordable, cloud-enabled connectivity and telematics platforms are drawing manufacturers across Southeast Asia into the ecosystem. With 40% ADAS penetration expected in 2026 and continued government-backed smart mobility programs, Asia-Pacific is likely to remain the leading source of long-term market growth through the forecast period.
Top 15 Trends Automotive Advanced Technologies Market
Proceed to Checkout to purchase the exclusive Automotive Advanced Technologies Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
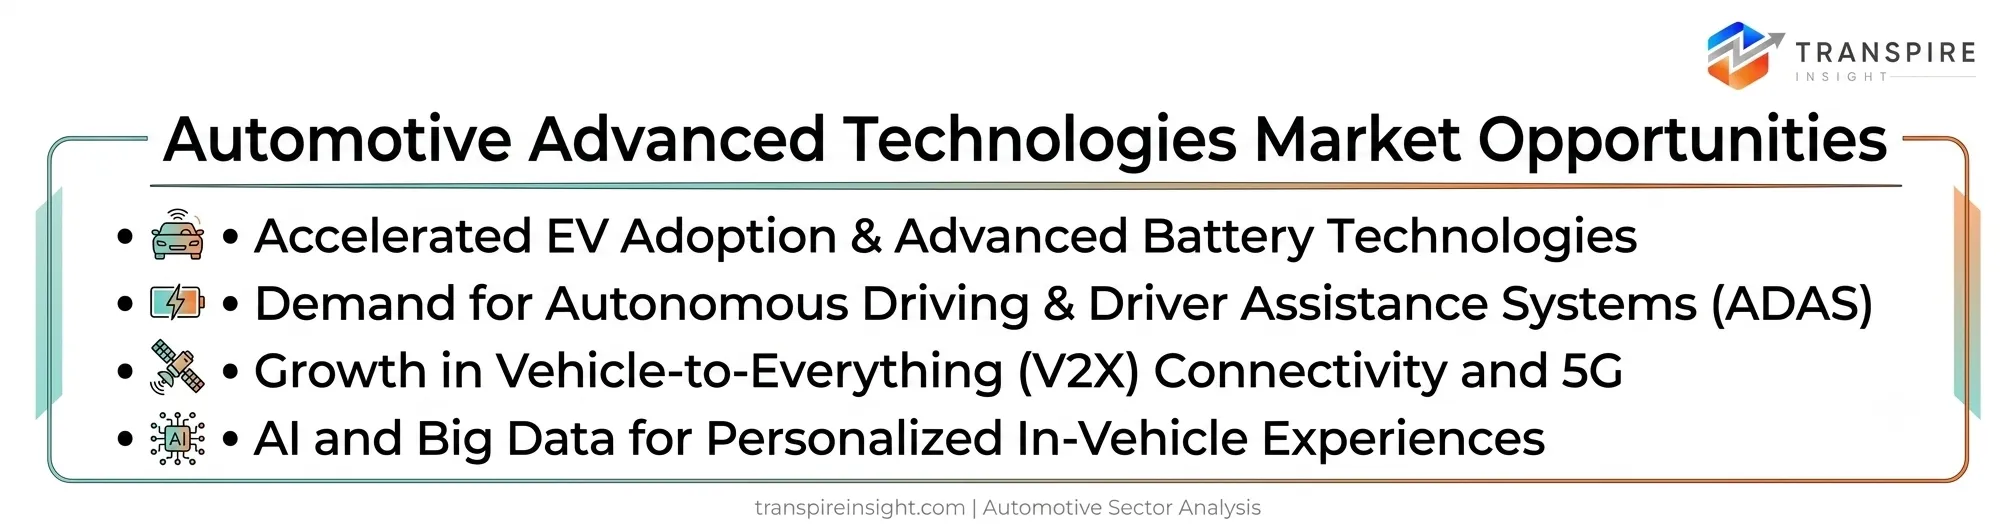
Autonomous Driving Systems
Self-driving capabilities are becoming increasingly sophisticated, moving vehicle design beyond mechanical engineering into complex cyber-physical systems requiring advanced automated driving technology and validation.
ADAS Mass Adoption
ADAS adoption is rapidly scaling in mass-market and mid-range passenger vehicles, driven by tightening safety standards and rising consumer demand for collision protection.
Electrification & Battery Powertrains
EV sales surpassed 17 million in 2024, with around 116 million EVs expected on roads by 2026, driving battery and charging infrastructure investment.
Software-Defined Vehicles
Vehicles are becoming software-defined platforms, alongside electrification and autonomy, fueling rising demand for advanced SoCs, memory, and power discrete semiconductor devices.
Connectivity & Telematics
Connectivity is now standard equipment, with the connected car market expected to exceed USD 214B by 2030 and telematics nearing USD 670B in value.
By-Wire Chassis Systems
Steer-by-wire and brake-by-wire electronic chassis systems are gaining traction in premium vehicles, with electro-mechanical brakes debuting across North America and China in 2026.
Top 25 Companies Leading the Automotive Advanced Technologies Market
Customize the exclusive Automotive Advanced Technologies Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Robert Bosch GmbH
Pioneer in automotive technology, supply chains, software engineering, and sensor solutions globally.
Founded: 1886 | HQ: Gerlingen, Germany.
Why It Ranks: World's top automotive supplier by revenue and sensor innovation market share.
Regional Dominance: Holds leading market share across Europe, North America, and Asia-Pacific regions.
Product Line: ADAS sensors, motion controllers, electric drive modules, and vehicle software.
2. Denso Corporation
Leader in thermal management, powertrain electronics, and advanced vehicle mobility systems.
Founded: 1949 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Key technological supplier for automakers with massive patent power.
Regional Dominance: Strong market presence in Japan, North America, and Asia-Pacific territories.
Product Line: Electric climate systems, powertrain modules, integrated radar, and cockpit electronics.
3. Continental AG
developer of advanced chassis controls, braking systems, and interior electronics.
Founded: 1871 | HQ: Hanover, Germany.
Why It Ranks: High domain expertise in autonomous drive systems and smart connectivity.
Regional Dominance: Dominates the European market while rapidly growing across the Americas and Asia.
Product Line: Smart sensors, autonomous mobility platforms, digital displays, and vehicle brakes.
4. ZF Friedrichshafen AG
Specialist in drive-by-wire controls, transmission systems, and active chassis security solutions.
Founded: 1915 | HQ: Friedrichshafen, Germany.
Why It Ranks: Market leader in commercial vehicle automation and electric drivetrain transmissions.
Regional Dominance: Strong operational footprint throughout Western Europe, North America, and China.
Product Line: Electric drives, steer-by-wire technologies, autonomous shuttles, and safety gear.
5. Magna International Inc.
Tier-one automotive supplier specializing in complete vehicle engineering and electrification.
Founded: 1957 | HQ: Aurora, Ontario, Canada.
Why It Ranks: Flexible contract manufacturing capability paired with cutting-edge powertrain software systems.
Regional Dominance: High manufacturing concentration across North America and key European countries.
Product Line: E-drives, driver assist cameras, active aerodynamics, and full-vehicle assembly.
6. Hyundai Mobis Co., Ltd.
Integrated software and hardware supplier powering modern Hyundai and Kia vehicles.
Founded: 1977 | HQ: Seoul, South Korea.
Why It Ranks: Exceptional expansion in electric vehicle battery systems and autonomous displays.
Regional Dominance: Dominates South Korea while rapidly capturing North American EV platforms.
Product Line: Battery packs, lighting systems, infotainment displays, and active chassis parts.
7. CATL (Contemporary Amperex Technology Co., Ltd.)
power battery manufacturer supplying advanced energy storage for major automakers.
Founded: 2011 | HQ: Ningde, Fujian, China.
Why It Ranks: market leader in lithium-ion and sodium-ion EV battery packs.
Regional Dominance: Commands massive domestic market share in China with rapid European growth.
Product Line: LFP cells, solid-state battery tech, cell-to-chassis modules, and swap systems.
8. Aptiv PLC
Architecture and software architecture integrator driving next-generation software-defined connected vehicles.
Founded: 1994 | HQ: Dublin, Ireland.
Why It Ranks: Pioneer in central domain computing platforms and high-speed electrical architectures.
Regional Dominance: Broad operational capability spanning North America, Europe, and Asia-Pacific markets.
Product Line: Central compute units, wiring harnesses, ADAS software, and connectivity hubs.
9. Aisin Corporation
Comprehensive auto parts company specializing in thermal management and transmission units.
Founded: 1965 | HQ: Kariya, Aichi, Japan.
Why It Ranks: World-class scale in hybrid transmissions and electric axle drivetrain modules.
Regional Dominance: Highly influential across Japanese OEM networks and expanding across Asian markets.
Product Line: E-axles, automatic transmissions, park assistance software, and brake modules.
10. Valeo SA
Innovator in smart electrification, automotive lighting, and active cabin comfort technologies.
Founded: 1923 | HQ: Paris, France.
Why It Ranks: Industry leader in ultrasonic sensors, LiDAR sensors, and thermal management.
Regional Dominance: Main market strength across Europe, alongside growing joint ventures in China.
Product Line: LiDAR units, smart headlights, electric motors, and automated parking gear.
Schedule a meeting with our market experts to discuss the exclusive Automotive Advanced Technologies Market report and identify the best research solution for your organization.
Conclusion
The advanced automotive technologies market is fundamentally redefining transportation through rapid software integration and electrification. As legacy suppliers and technology companies collaborate, software-defined architectures are turning vehicles into upgradeable digital platforms. High-performance chips, artificial intelligence, and efficient energy storage systems will remain key factors separating market leaders from competitors. Companies that prioritize agile software development, robust cybersecurity standards, and sustainable supply chains will control the future of smart mobility, delivering safer, cleaner, and more personalized driving experiences to consumers around the world.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


