
Sep 02, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the aircraft gearbox market size is projected to grow from USD 4.5 billion in 2026 to USD 6.3 billion by 2035, at a CAGR of 7.2% during the forecast period 2026-2035. Commercial aircraft fleet growth, increasing levels of air passenger traffic, and the quick adoption of geared turbofan engines are fueling the growth of the aircraft gearbox market. Further, military modernization and technological progress in lightweight composite gear manufacturing propel demand.
Introduction
An aircraft gearbox is a crucial part of the aerospace propulsion and flight control system that delivers mechanical power from a jet engine to a propeller or auxiliary system, or from a rotor to a rotor. Advanced gearboxes allow for more efficient operation of engine fan and turbine speeds, as well as reduced emissions, as commercial airlines seek increased fuel efficiency and reduced emissions. These precision systems are used in a wide variety of accessory gearboxes, high-performance reduction gearboxes, tiltrotors, and more and are able to take high loads during operation. Industry growth is still being driven by high manufacturing standards, rigorous safety certification, and increasing regional air travel.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Aircraft Gearbox Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance rests on the depth of its aerospace manufacturing base and the concentration of engine and gearbox OEMs within its borders. Pratt & Whitney's FAA certification of the GTF Advantage engine for the A320neo family reinforced the region's lead in geared-turbofan propulsion, while Triumph Group's accessory-drive assembly lines and Boeing's rotorcraft programs sustain both original-equipment and aftermarket gearbox demand. Sizable US defense budgets, channeled through Lockheed Martin platforms and a mature military aviation sector, further anchor regional revenue. A well-established MRO network, supported by Approved Model List supplemental-type certificates, accelerates retrofit uptake and gives local overhaul providers an edge in deploying additively manufactured spares, keeping replacement-part demand steady even as fleets age.
Asia-Pacific's rapid ascent stems from a deliberate push toward supply-chain autonomy among indigenous aircraft programs. COMAC's C919 entering commercial service and its growing reliance on domestic factories for second-source gear casings illustrate how regional governments are steering production away from foreign primes. India's planned USD 12 billion investment in airport infrastructure is expected to lift narrowbody and regional jet orders, while its aerospace offset rules require foreign manufacturers to co-invest in local gear-machining capacity. Together, these forces are building a gearbox manufacturing base that reduces the region's historical dependence on imported components.
Top 15 Trends in the Aircraft Gearbox Market
Aircraft Gearbox Market Size & Statistics
Geared Turbofan Propulsion Architectures
Airlines increasingly favor geared turbofan engines because the design lowers fuel burn, reduces noise significantly, and cuts overall maintenance costs versus traditional direct-drive engine architectures.
Lightweight Composite Gearbox Materials
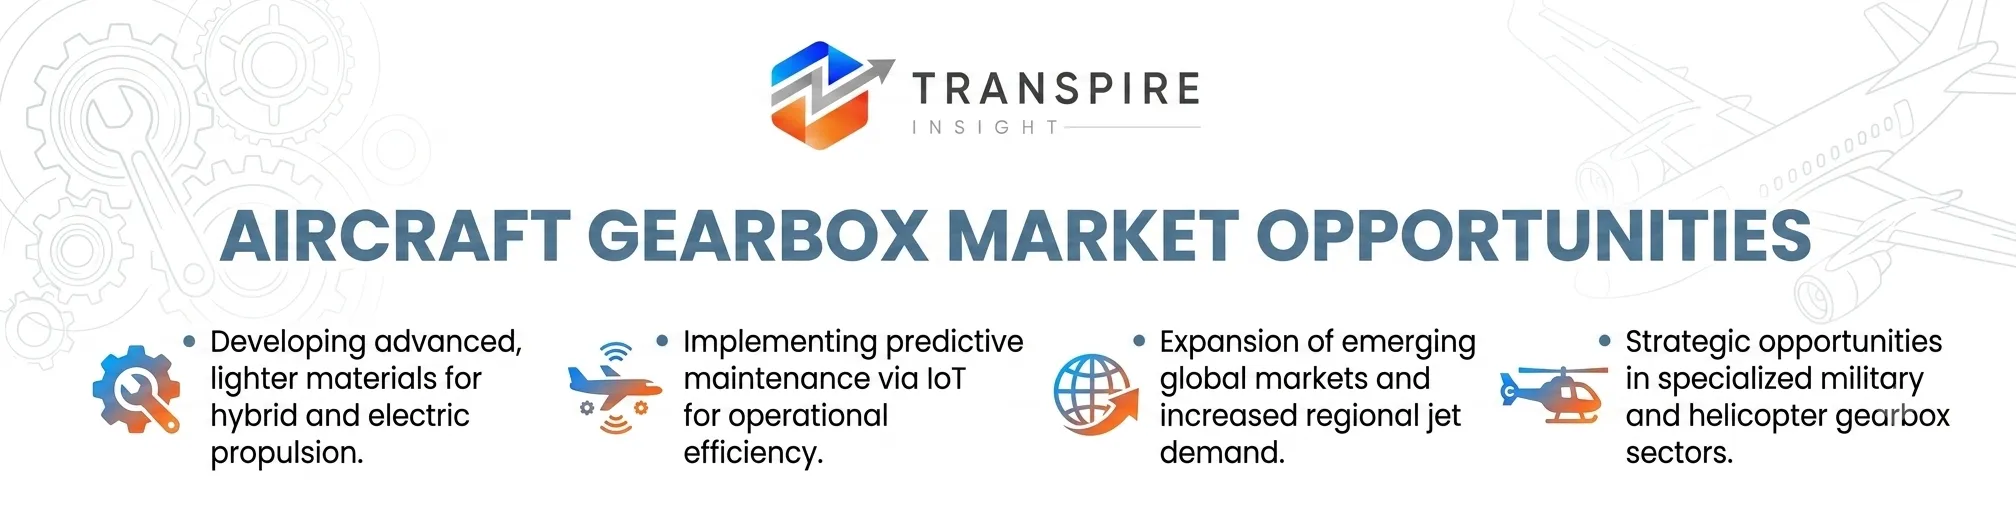
Manufacturers are replacing metal housings with lightweight composite materials to cut aircraft weight, improve fuel efficiency, and extend component service life across commercial fleets worldwide.
Electric Main Gearbox Systems for Helicopters
Helicopter OEMs are adopting electric main gearboxes, which extend safe-flight duration during oil-loss events, reduce weight, and simplify lubrication system design overall for rotorcraft operators.
Localization of Gear Machining Hubs in Asia-Pacific
Asia-Pacific nations are increasingly building domestic gear machining hubs as indigenous aircraft programs seek supply-chain autonomy, reducing dependence on imported components and foreign primes globally.
Smart Diagnostics and Health Monitoring Sensors
Gearbox manufacturers are embedding smart diagnostic sensors that continuously monitor vibration, temperature, and wear patterns, enabling predictive maintenance and reducing unscheduled aircraft downtime across fleets.
UAV and Unmanned Aircraft Gearbox Demand
Rising military and commercial UAV production is creating new demand for compact, lightweight gearbox systems engineered for unmanned platforms' unique power and endurance requirements worldwide.
Top 25 Companies Leading the Aircraft Gearbox Market
Safran manufactures precision gear transmissions powering over twenty-five thousand commercial aircraft worldwide.
Founded: 1905 | HQ: Colombes, France.
Why It Ranks: Holds world-leading market share in accessory gearboxes for narrowbody narrow-aisle airliners.
Regional Dominance: Europe dominates sales with heavy expansion across major North American assembly hubs.
Product Line: Accessory drive gearboxes, reduction gearboxes, thrust reversers, and power transmission systems.
GE Aerospace powers roughly three out of every four commercial flights.
Founded: 1892 | HQ: Evendale, Ohio, USA.
Why It Ranks: Unmatched OEM footprint via CFM International joint ventures powering airliners.
Regional Dominance: Strongest revenue hold in North America alongside immense commercial operations in Asia-Pacific.
Product Line: Geared turbofan modules, accessory power drives, engine gear assemblies, and transfer gearboxes.
Pioneer of Geared Turbofan engine technology transforming commercial fuel efficiency standards worldwide.
Founded: 1925 | HQ: East Hartford, Connecticut, USA.
Why It Ranks: Industry pioneer in high-power fan drive gear systems for modern narrowbodies.
Regional Dominance: Dominates North American commercial and military engine markets while expanding throughout Europe.
Product Line: Fan drive gear systems, auxiliary gearboxes, reduction gearboxes, and turboprop transmissions.
World leader in powering widebody long-haul commercial aircraft and military defense platforms.
Founded: 1906 | HQ: London, United Kingdom.
Why It Ranks: Advanced UltraFan power gearbox design capability handling ultra-high output power requirements.
Regional Dominance: Controls major European market shares alongside expansive commercial airline partnerships in Asia-Pacific.
Product Line: UltraFan power gearboxes, engine accessory drives, turboprop gearboxes, and defense transmissions.
titan in supplying auxiliary power units and aviation mechanical drive systems.
Founded: 1906 | HQ: Phoenix, Arizona, USA.
Why It Ranks: Major OEM supplier of integrated gearboxes for business jets and helicopters.
Regional Dominance: Extensive defense and commercial footprint across North American and Middle Eastern markets.
Product Line: Auxiliary power unit gearboxes, turboprop engine gearboxes, actuation drives, and accessories.
Germany’s leading engine manufacturer specializing in high-tech engine power transmission modules.
Founded: 1934 | HQ: Munich, Germany.
Why It Ranks: Key technological partner providing advanced power drive components for commercial engines.
Regional Dominance: Strong leadership in Europe with significant joint-venture influence across North America.
Product Line: Power turbine gear assemblies, accessory drives, maintenance gearboxes, and rotor shafts.
Italian defense champion producing custom heavy-duty gearboxes for advanced rotorcraft systems.
Founded: 1948 | HQ: Rome, Italy.
Why It Ranks: Dominant force in helicopter main transmissions and tiltrotor gearbox engineering.
Regional Dominance: European market leader with growing military helicopter contracts across South America.
Product Line: Main rotor gearboxes, tail rotor drives, tiltrotor transmission systems, and accessories.
Specialized tier-one supplier manufacturing complex aerospace mechanical power drive gearbox components.
Founded: 1993 | HQ: Berwyn, Pennsylvania, USA.
Why It Ranks: Top-tier independent manufacturer of utility, engine, and flight control gearboxes.
Regional Dominance: Primary market concentration across North America with active supply routes to Europe.
Product Line: Engine accessory gearboxes, actuation gearboxes, rotorcraft transmissions, and mechanical power drives.
Leading provider of integrated flight control actuation and air management gear transmissions.
Founded: 1949 | HQ: Lindenberg, Germany.
Why It Ranks: Essential supplier of high-precision flight control actuation gearboxes to major OEMs.
Regional Dominance: Heavy operational hold across European civil aviation with growing footprint in Asia.
Product Line: Flap and slat actuation gearboxes, landing gear drives, and power transmissions.
Precision aerospace gear specialist known for high-accuracy spiral bevel gear manufacturing.
Founded: 1947 | HQ: Downers Grove, Illinois, USA.
Why It Ranks: Renowned custom manufacturer of high-load gears for military and commercial aviation.
Regional Dominance: Dominates North American custom aerospace gear manufacturing and overhaul defense sectors.
Product Line: Spiral bevel gears, accessory gearboxes, helicopter transmissions, and spur gear assemblies.
Conclusion
The aircraft gearbox market is in a transformative phase as air passenger traffic is on the rise, the fleet is being modernized, and technology is rapidly developing. Engine manufacturers are increasingly moving towards geared turbofan and hybrid electric power solutions, and the need for lightweight, high-torque gearboxes is growing rapidly. Key players are focusing on improving durability and lowering operating expenses by applying additive manufacturing, advanced steel alloys, and predictive health monitoring. The international aircraft gearbox market is set to grow at a high level and maintain strong commercial order backlogs, as well as solid military investments.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


