
Sep 08, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the aerospace parts manufacturing market size is projected to grow from USD 1043.25 billion in 2026 to USD 1628 billion by 2035, at a CAGR of 6.95% during the forecast period 2027-2035. Commercial aircraft backlog deliveries, the surge in defence budget spending, the demand for lightweight composite structural materials, rapid aircraft fleet retrofits for fuel efficiency, and the extensive use of 3D-printed additive components are driving the market for expansion.
Introduction
The aerospace parts manufacturing industry is the backbone of commercial, military, and space-based platforms globally. It's a segment that generates more than 1 trillion dollars a year, manufacturing advanced cabin interiors, precision avionics, complex aerostructures, landing gear systems, and mission-critical systems. Tier-1 and Tier-2 suppliers are increasing their production capacity as a result of order surges from post-pandemic, digital twin engineering, and advanced Additive Manufacturing. This is a high-value, technology-based industrial market characterized by high barrier-to-entry certifications and extremely high quality tolerances.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Aerospace Parts Manufacturing Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America is anticipated to be the highest market for Aerospace Parts Manufacturing during the forecast period with a 39% share. The reason for North America's dominance is that it has an established and well-established aerospace and defense manufacturing ecosystem. The U.S. is home to the key manufacturers of aircraft, engines, precision-engineered parts, and defense equipment, leading to a significant demand for precision-engineered parts in both commercial and defense aircraft programs. Production volumes are sustained by high defence spending, aircraft modernization programmes and large commercial aircraft backlogs, and strong MRO activity provides an ongoing demand for replacement parts. Meanwhile, manufacturers are ramping up investments in additive manufacturing, automation, advanced materials and digital inspection for enhancing production efficiency and complying with the high-quality requirements of the aerospace industry. The factors remain to strengthen the North America region as the biggest regional market.
The Aerospace Parts Manufacturing Market in Asia-Pacific is expected to expand at the highest rate over the forecast period with an estimated CAGR of 7.02% from 2026 to 2035. The economic growth in Asia-Pacific is being fuelled by growing traffic demand on passenger aircraft, an increase in aircraft fleets, defense modernization, and localizing aerospace manufacturing. China continues to be a key regional manufacturer, and India is continuing to build up its in-country aircraft-related system by boosting aircraft demand, defense orders, and investments in manufacturing. Other economies in the region, such as Japan, South Korea, and Singapore, are also developing more capabilities in precision machining, aerostructures, engine parts, and MRO. Increases in fleet size and aircraft utilization of airlines across the region are expected to drive the demand for both original equipment parts and aftermarket replacement parts, making the Asia-Pacific region the fastest-growing region in the forecast.
Top 15 Trends in the Aerospace Parts Manufacturing Market
List of Top 25 Companies Leading the Aerospace Parts Manufacturing Market
1. Boeing
leader in commercial jet airframe construction and major defense platforms.
Founded: 1916 | HQ: Arlington, Virginia, USA.
Why It Ranks: Commands immense market share through massive commercial transport airframe manufacturing.
Regional Dominance: Leads total commercial and military production across North America and Europe.
Product Line: Wide-body aerostructures, wing assemblies, composite flight surfaces, and fuselages.
2. Airbus
Premier European manufacturer producing integrated flight structures and commercial airliner components.
Founded: 1970 | HQ: Blagnac, France.
Why It Ranks: Maintains the world's largest commercial aircraft order backlog, driving steady parts demand.
Regional Dominance: Dominates European aerospace supply chains with extensive regional manufacturing integration.
Product Line: Single-aisle airframes, composite wing sections, control surfaces, and cockpit modules.
3. RTX Corporation
Diversified aerospace powerhouse producing engine assemblies, avionics, and defense strike hardware.
Founded: 1922 | HQ: Arlington, Virginia, USA.
Why It Ranks: Controls vast market footprint via Pratt & Whitney engines and Collins Aerospace.
Regional Dominance: Holds primary market share across North American defense and civil aviation.
Product Line: Jet engines, flight control systems, landing gear, and power distribution.
4. GE Aerospace
Pioneer in high-thrust commercial and military aircraft turbofan engine sub-assemblies.
Founded: 1892 | HQ: Evendale, Ohio, USA.
Why It Ranks: Powers the majority of the commercial fleet through internal and joint-venture engines.
Regional Dominance: Dominates commercial propulsion manufacturing with an extensive North American base.
Product Line: Turbine blades, engine cores, additive printed nozzles, and thrust reversers.
5. Safran S.A.
French multinational leader specializing in aircraft propulsion, interiors, and landing gear.
Founded: 2005 | HQ: Paris, France.
Why It Ranks: Unmatched market share in single-aisle engine systems and landing gear assemblies.
Regional Dominance: Anchors Western European aerospace manufacturing and maintains a massive worldwide export footprint.
Product Line: CFM LEAP engine parts, braking systems, nacelles, and wiring harnesses.
6. Lockheed Martin
Premier defense contractor manufacturing stealth fighter airframes, tactical missiles, and structures.
Founded: 1995 | HQ: Bethesda, Maryland, USA.
Why It Ranks: World leader in advanced defense aerospace manufacturing and complex tactical platforms.
Regional Dominance: Dominates defense hardware manufacturing in North America and allied export markets.
Product Line: Fighter airframes, composite structures, missile bodies, and high-speed flight controls.
7. BAE Systems
Defense titan producing military airframes, electronic warfare systems, and precision components.
Founded: 1999 | HQ: London, United Kingdom.
Why It Ranks: Dominates European defense manufacturing, supplying structural components to major fighter programs.
Regional Dominance: Leading aerospace and defense manufacturer across the United Kingdom and Europe.
Product Line: Rear fuselage sections, electronic warfare housings, wing components, and radomes.
8. Northrop Grumman
Specialized manufacturer of advanced stealth aerostructures, solid rocket motors, and radars.
Founded: 1994 | HQ: Falls Church, Virginia, USA.
Why It Ranks: Key provider of complex composite structures for strategic defense and space programs.
Regional Dominance: Strong hold over US military, space, and classified defense program manufacturing.
Product Line: Composite fuselage panels, rocket motor casings, space structures, and radars.
9. Honeywell International
Engineering giant manufacturing auxiliary power units, avionics, thermal controls, and brakes.
Founded: 1906 | HQ: Charlotte, North Carolina, USA.
Why It Ranks: Unrivaled operational footprint across commercial and military cockpit and mechanical systems.
Regional Dominance: manufacturing scale centered in North America with key Asian facilities.
Product Line: APUs, flight control actuators, environmental control units, and wheel brakes.
10. Spirit AeroSystems
Essential Tier-1 manufacturer specializing in large commercial composite and metallic aerostructures.
Founded: 2005 | HQ: Wichita, Kansas, USA.
Why It Ranks: Principal aerostructure supplier for the world's major commercial passenger jet programs.
Regional Dominance: Major manufacturing operations across the United States and the United Kingdom.
Product Line: Fuselage assemblies, wing pylon structures, engine nacelles, and wing spars.
Conclusion
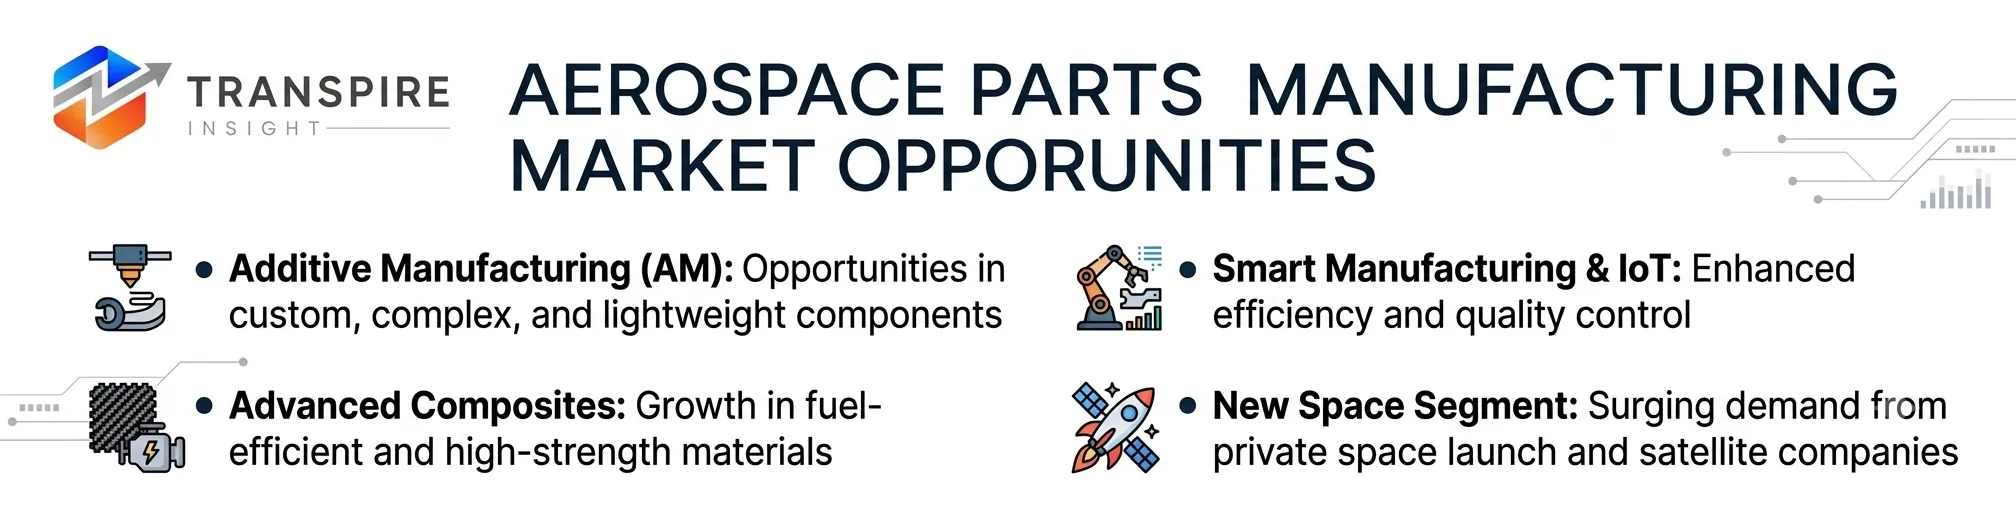
The aerospace parts manufacturing sector is moving into a tech-focused, resilient future with rapid digitalization and advanced composites moving to center stage. Growing order backlogs and defense modernization at the prime contractor level will continue to depend on Tier-1 and Tier-2 suppliers. The future leaders will be determined by strategic investments in Additive Manufacturing, localized supply chains, and materials with high-temperature capabilities. The next decade of sustainable aviation will be led by companies that make innovations in precision flight-critical components.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


