
Aug 19, 2026
By Transpire Insight
Description
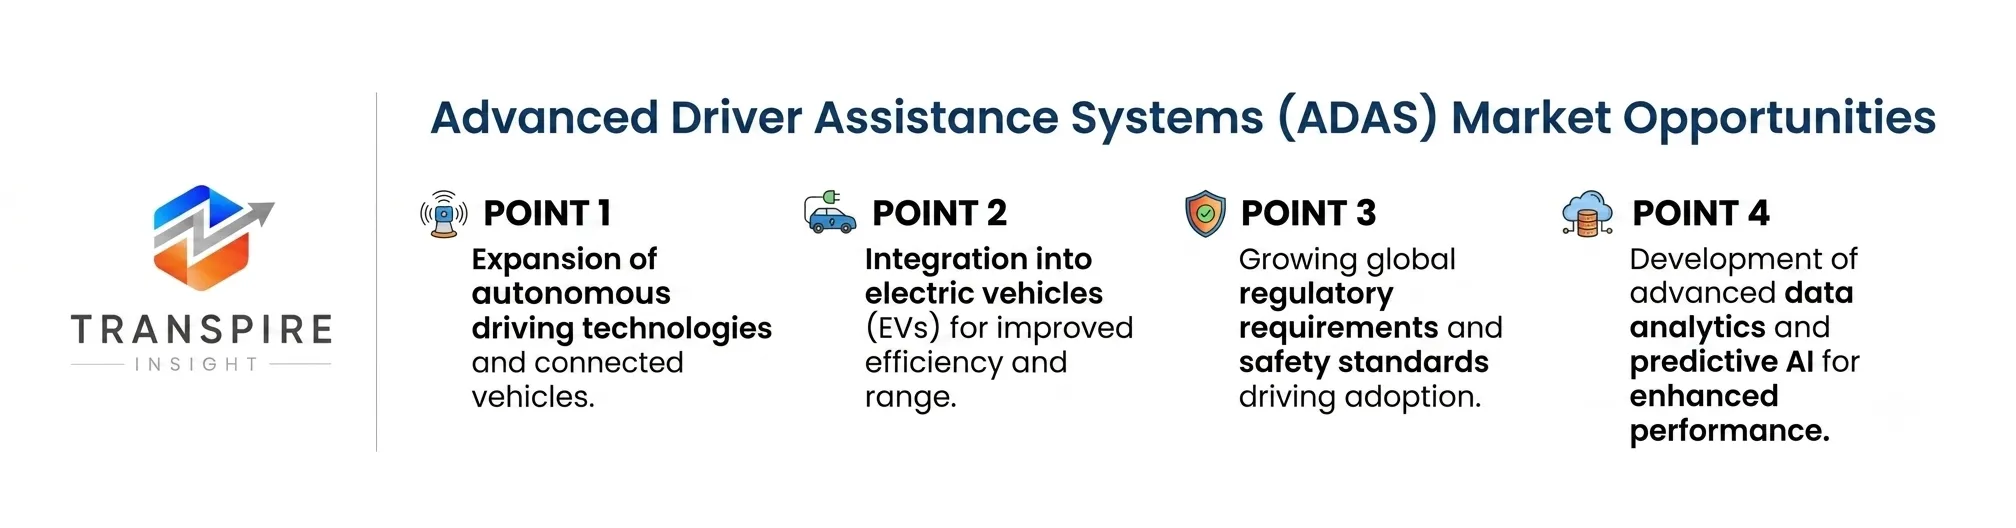
According to a research report published by Transpire Insight, the Advanced Driver Assistance Systems (ADAS) market size is projected to grow from USD 400.34 billion in 2026 to USD 930.25 billion by 2035, at a CAGR of 9.8% during the forecast period 2026-2035. The regulations that strongly mandate automated emergency braking and lane assistance systems are leading to the adoption of these systems. At the same time, consumer demand for semi-autonomous functionality, falling sensor production costs, and growth in EV architectures drive the smooth integration of digital safety features.
Introduction
Advanced Driver Assistance Systems (ADAS) are one of the key pillars of the modern automotive industry, connecting human-driven and fully autonomous modes of transportation. The systems that support ADAS use a sophisticated array of radar, camera, ultrasound, and LiDAR sensors and intelligent software processing that constantly monitor the surroundings. Active safety platforms are able to reduce human error on roads by performing real-time collision avoidance, automated braking, lane centering, and driver monitoring. The transition to software-defined mobility in vehicles makes Advanced Driver Assistance Systems (ADAS) vital building blocks to advanced levels of automated driving.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Advanced Driver Assistance Systems (ADAS) Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Automotive Advanced Technologies Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America is also expected to experience the highest demand with a market share of 34.02% by 2026 in the Advanced Driver Assistance Systems (ADAS) market. North America continues to be the primary market for ADAS, with U.S. OEMs and Tier-1s like Bosch, Continental, and Qualcomm dominating. Legacy OEMs and EV manufacturers are making early moves in connected cars, especially in areas like adaptive cruise control, automatic emergency braking, lane keeping systems; a well-developed, industrialized infrastructure for quickly implementing mass rollout of connected cars and safety tech; as well as a growing regulatory push for mandating collision-avoidance and driver-assist features. As automakers in the region increasingly design AI, sensors, and software into the vehicle itself, rather than as an afterthought, they are looking for suppliers who can integrate with their existing production lines, get to the market faster, and provide reliable support for high-volume passenger and commercial vehicle production. Most prominent use cases are adaptive cruise control and automatic emergency braking in light commercial vehicles or passenger cars, directly reducing collision rates and supporting regulatory compliance. Unlike the more dynamic emerging markets, North America's uptake of ADAS is more advanced and will help to maintain robust demand from high levels of consumer purchasing power and a robust pool of software and semiconductor expertise.
South Korea, China, and Japan are expected to be some of the biggest revenue drivers for the ADAS market during the forecast period, with the Asia-Pacific region showing the highest CAGR of approximately 14.8%. Asia-Pacific is expected to be driven by growth in China, Japan, South Korea, and India, setting the course for the next evolution of the adoption of ADAS. As the region's biggest player, China is centered on the electrification, connectivity, and autonomous-driving technologies of its high-volume passenger vehicle and EV production base, supported by robust export-based manufacturing. In urban China, over 30% of the vehicles on sale had pre-installed ADAS features. India's burgeoning domestic vehicle demand and fast industrial digitization are making it one of the fastest-growing markets for advanced safety and driver-assist systems in the world. Advanced automotive engineering makes Japan and South Korea remain in the vanguard of sensor innovation, robotics-based manufacturing, and driver-assist innovation through AI. Cost-competitive high-volume markets in the East are driving the adoption of ADAS and electrified drivetrains for efficiency and safety reasons, and new connectivity and telematics platforms with lower costs but cloud support are attracting manufacturers from across Southeast Asia to the platform. Asia-Pacific is expected to continue to be the major contributor to market growth during the forecast period due to the increasing production of vehicles in the region and the government-backed smart mobility programmes.
Top 15 Trends in the ADAS Market
Proceed to Checkout to purchase the exclusive Advanced Driver Assistance Systems (ADAS) Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
List of Top 25 Companies Leading the Advanced Driver Assistance Systems (ADAS) Market
Customize the exclusive Advanced Driver Assistance Systems (ADAS) Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Robert Bosch GmbH
market giant delivering high-reliability radar systems, multi-camera suites, and centralized domain controllers.
Founded: 1886 | HQ: Gerlingen, Germany.
Why It Ranks: Holds unmatched market share across complete hardware-software automated safety ecosystems.
Regional Dominance: Extensive market presence across Europe, North America, and the Asia-Pacific region.
Product Line: Radar sensors, video cameras, ultrasonic sensors, and ADAS domain controllers.
2. Continental AG
Pioneers intelligent mobility hardware and end-to-end perception systems for automakers.
Founded: 1871 | HQ: Hanover, Germany.
Why It Ranks: Key innovator in radar technology, surround-view vision, and holistic safety integration.
Regional Dominance: Strong industrial foothold spanning Europe, North America, and expanding Asian markets.
Product Line: Long-range radars, surround-view camera systems, LiDAR, and driver assistance ECUs.
3. Mobileye
Pioneer in vision-based driving assistance, chipsets, and cloud-enhanced crowd-sourced mapping solutions.
Founded: 1999 | HQ: Jerusalem, Israel.
Why It Ranks: World leader in specialized vision processing system-on-chip hardware for active safety.
Regional Dominance: supplier footprint serving leading automotive OEMs across all major continents.
Product Line: EyeQ system-on-chip devices, SuperVision platforms, and REM mapping software.
4. DENSO Corporation
Leading Japanese Tier-1 supplier delivering high-precision automotive electronics and advanced perception hardware.
Founded: 1949 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Industry benchmark for high-reliability sensor manufacturing and automotive safety system integration.
Regional Dominance: Undisputed market stronghold across Japan and Asia-Pacific, with major reach.
Product Line: Millimeter-wave radar, stereo vision sensors, perimeter monitoring, and driver status monitors.
5. Aptiv PLC
Specializes in advanced vehicle computing architecture, smart sensor integration, and software stacks.
Founded: 1994 | HQ: Dublin, Ireland.
Why It Ranks: Expert in centralizing vehicle electrical architectures and software-defined driver assistance capabilities.
Regional Dominance: Broad manufacturing and engineering footprint in North America, Europe, and Asia.
Product Line: Smart vehicle architecture, corner radars, central domain controllers, and sensing software.
6. Valeo SA
leader in ultrasonic sensing platforms, LiDAR units, and smart lighting systems.
Founded: 1923 | HQ: Paris, France.
Why It Ranks: Top provider of ultrasonic parking sensors and mass-production automotive LiDAR.
Regional Dominance: Strong primary presence across Europe, with rapidly growing production in Asia-Pacific.
Product Line: SCALA LiDAR sensors, ultrasonic parking assistance, surround-view systems, and front cameras.
7. ZF Friedrichshafen AG
Supplies integrated safety solutions encompassing sensing, central computing, and mechanical chassis actuation.
Founded: 1915 | HQ: Friedrichshafen, Germany.
Why It Ranks: Exceptional ability to seamlessly fuse digital sensing inputs directly with mechanical braking/steering.
Regional Dominance: Dominant enterprise presence throughout Europe, North America, and East Asian hubs.
Product Line: ProAI central controllers, full-range radar, smart camera systems, and brake-by-wire.
8. Magna International
Comprehensive automotive supplier delivering modular camera systems, electronic control units, and automated features.
Founded: 1957 | HQ: Aurora, Ontario, Canada.
Why It Ranks: High-capacity system integrator combining vision hardware with flexible automated driving software stacks.
Regional Dominance: Dominant supplier hold across North America and extensive European assembly operations.
Product Line: ICON digital radar, 360-degree camera systems, driver monitoring, and automated park assist.
9. Hyundai Mobis
Major automotive technology arm engineering integrated safety suites and intelligent driver assistance hardware.
Founded: 1977 | HQ: Seoul, South Korea.
Why It Ranks: Key driver of Level 2+ and Level 3 automated driving commercialization across Asia.
Regional Dominance: Leading market presence across South Korea, East Asia, and Hyundai-Kia networks.
Product Line: In-cabin driver monitoring systems, autonomous emergency braking controllers, and blind-spot radars.
10. Autoliv Inc.
automotive safety leader providing specialized occupant detection, driver monitoring, and night vision.
Founded: 1953 | HQ: Stockholm, Sweden.
Why It Ranks: Premier manufacturer of life-saving active and passive safety systems integrated with vehicle intelligence.
Regional Dominance: operational presence with deep commercial ties across Europe and the Americas.
Product Line: Driver monitoring cameras, night vision systems, radar sensors, and integrated safety electronics.
Schedule a meeting with our market experts to discuss the exclusive Advanced Driver Assistance Systems (ADAS) Market report and identify the best research solution for your organization.
Conclusion
The Advanced Driver Assistance Systems market continues to evolve into an indispensable component of modern automotive design. Fueled by strict safety regulations, falling sensor costs, and rapid consumer adoption of Level 2+ autonomy, ADAS platforms are rapidly becoming standard across mass-market vehicles. Industry leaders are shifting toward software-defined, centralized architectures that fuse radar, camera, and AI data in real time. As hardware costs decrease and software capabilities expand, ADAS will serve as the crucial technological ramp toward fully autonomous, zero-accident road transport.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


