
Jul 04, 2026
By Transpire Insight
Description
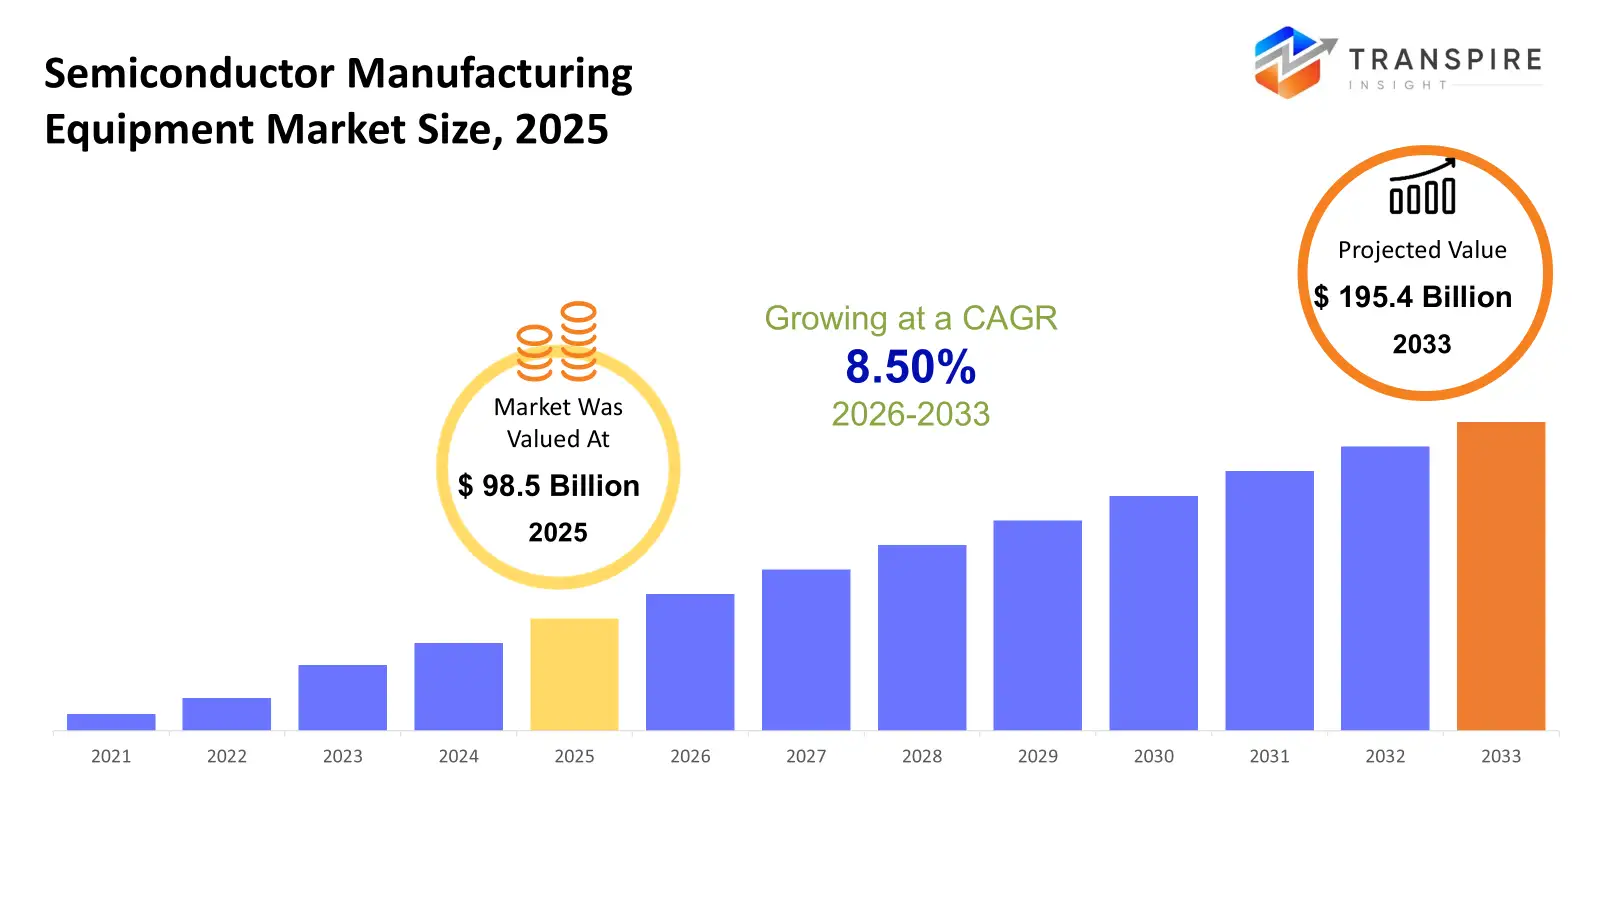
According to a research report published by Transpire Insight, the global semiconductor manufacturing equipment market size is projected to grow from USD 167 billion in 2026 to USD 347.36 billion by 2035, at a CAGR of 12.2% during the forecast period 2026-2035. The rising demand for AI chips, the growing presence of IoT devices, and significant investments in domestic semiconductor manufacturing foundries worldwide are the key growth drivers in the global semiconductor manufacturing equipment market.
Introduction
The semiconductor manufacturing equipment market serves as a backbone in the global electronics industry, providing cutting-edge technologies to manufacture, assemble, and test semiconductors. With technology moving into an ever-shrinking nanometer node and more sophisticated 3D packaging architectures, the complexity of this equipment grows rapidly. As a multi-billion-dollar industry, the market is the foundation for the advancement of high-performance computing, automotive electronics, data centers, and consumer devices around the world.
Recent Development News:
February 2026: ASML announced its High-NA EUV lithography systems are ready for high-volume chip production, marking a major shift for AI chip manufacturing and sub-2nm scaling.
June 2026: Applied Materials introduced new deposition and selective etch systems enabling precise fabrication of advanced 3D structures like GAA transistors and high-layer NAND.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Semiconductor Manufacturing Equipment Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Semiconductor Manufacturing Equipment Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
Asia-Pacific is anticipated to generate the highest demand and grow the fastest during the forecast period in the Semiconductor Manufacturing Equipment market. Asia-Pacific is expected to see this dominant growth rate, driven by the presence of some of the world's "megafoundries" as well as huge investments in new fabrication plants (fabs) and aggressive expansion of packaging and testing plants. Advanced extreme ultraviolet (EUV) lithography and high-volume wafer processing technologies are major investments being made by companies in the leading countries fueling this demand: China, Taiwan, South Korea, and Japan. An increase in Taiwan and South Korea’s key foundry players' accelerated fab modernization programs has driven the region's tool purchasing metrics to a new high in 2025 and 2026.
North America is expected to experience robust infrastructure expansion during the forecast period in the Semiconductor Manufacturing Equipment market. The area is strategically important due to the presence of major automated chip design companies, leading metrology suppliers, and the strong domestic semiconductor manufacturing efforts. Today, the United States is one of the main drivers of demand for equipment in this area, with significant federal investments under the CHIPS and Science Act to rebuild onshore supply chain resiliency. As U.S. domestic activities advance through 2025 and 2026, they are increasingly focused on the purchase of next-generation etching, deposition, and lithography tools that will be needed to develop advanced foundry facilities for sub-3nm architectures.
Top 15 Trends in the Semiconductor Manufacturing Equipment Market
Proceed to Checkout to purchase the exclusive Semiconductor Manufacturing Equipment Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
Top 25 Companies Leading the Semiconductor Manufacturing Equipment Market
Customize the exclusive Semiconductor Manufacturing Equipment Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
Leading Semiconductor Manufacturing Equipment Companies to Watch Globally
The top 25 companies dominate the semiconductor manufacturing equipment market.
Monopolizes the global market for critical extreme ultraviolet lithography systems.
Founded: 1984 | HQ: Veldhoven, Netherlands.
Why It Ranks: Unrivaled sole provider of advanced lithography machines for cutting-edge microchips.
Regional Dominance: Sweeps major manufacturing markets across Taiwan, South Korea, and China.
Product Line: Extreme ultraviolet and deep ultraviolet photolithography hardware for chipmakers.
Holds the largest, most diverse product portfolio across semiconductor equipment.
Founded: 1967 | HQ: Santa Clara, California, US.
Why It Ranks: Dominates globally by providing critical atomic layer material deposition solutions.
Regional Dominance: Spans heavily across major Asian fab hubs and expanding Western factories.
Product Line: Advanced engineering systems for deposition, etching, ion implantation, and polishing.
Leading innovator in complex vertical etching technologies for 3D semiconductors.
Founded: 1980 | HQ: Fremont, California, US.
Why It Ranks: Essential architect behind advanced atomic-scale material removal and wafer cleaning.
Regional Dominance: Secures high tool demand throughout massive East Asian foundry ecosystems.
Product Line: High-precision semiconductor etching, chemical vapor deposition, and single-wafer cleaning.
Global market standard for microchip yield management and defect inspection.
Founded: 1975 | HQ: Milpitas, California, US.
Why It Ranks: Critical for optimizing factory efficiency by detecting molecular-level chip imperfections.
Regional Dominance: Major supplier across American, Taiwanese, and South Korean advanced logic fabs.
Product Line: High-resolution optical inspection, metrology systems, and computational data analytics.
Asia's premier manufacturer covering multiple sequential chip production steps safely.
Founded: 1963 | HQ: Tokyo, Japan.
Why It Ranks: Essential provider of precise coater-developer systems tied directly to lithography.
Regional Dominance: Commands substantial market share across leading Japanese and pan-Asian foundries.
Product Line: Photoresist coater-developers, thermal processing furnaces, and dry etching equipment.
Global pioneer holding an immense market share for wafer cleaning equipment.
Founded: 1943 | HQ: Kyoto, Japan.
Why It Ranks: Prevents contamination by manufacturing industry-standard wet processing cleaning systems.
Regional Dominance: Highly integrated within specialized semiconductor fabrication plants across global regions.
Product Line: Single-wafer cleaners, wet stations, laser annealers, and measurement equipment.
Historic precision optical giant manufacturing deep ultraviolet immersion lithography scanners.
Founded: 1917 | HQ: Tokyo, Japan.
Why It Ranks: Deploys highly precise structural alignment technologies required for legacy nodes.
Regional Dominance: Sustains stable equipment integration throughout Asian and North American foundries.
Product Line: ArF immersion scanners, KrF steppers, and ultra-precise micro-measurement systems.
Disrupting conventional lithography through newly developed nanoimprint semiconductor technology.
Founded: 1937 | HQ: Tokyo, Japan.
Why It Ranks: Offers cost-effective, low-energy stamp alternatives to expensive standard optical lithography.
Regional Dominance: Embedded deeply across global memory, power devices, and automotive chipmakers.
Product Line: KrF/i-mode steppers, nanoimprint lithography systems, and organic LED displays.
Master of advanced electron beam metrology and high-resolution imaging tools.
Founded: 1947 | HQ: Tokyo, Japan.
Why It Ranks: Delivers unparalleled critical-dimension measurement accuracy for microscopic chip features.
Regional Dominance: Trusted specialized engineering supplier across American, European, and Asian foundries.
Product Line: Critical-dimension scanning electron microscopes, plasma etchers, and inspection instruments.
World-leading supplier of automated test equipment for advanced SoC devices.
Founded: 1954 | HQ: Tokyo, Japan.
Why It Ranks: Ensures reliability for AI chips by verifying integrated circuit performance.
Regional Dominance: Captures dominant hardware testing footprint across global chip packaging facilities.
Product Line: Automated semiconductor testers, electronic measuring instruments, and thermal handling systems.
Schedule a meeting with our market experts to discuss the exclusive Semiconductor Manufacturing Equipment Market report and identify the best research solution for your organization.
Conclusion
The semiconductor manufacturing equipment market is experiencing a significant transformation, bolstered by rising demand for artificial intelligence, next-generation 3D packaging, and advanced lithography. Further into the forecast period, large-scale capacity ramp-ups in Asia-Pacific and Western supply chain onshoring will remain the drivers, further driving capital spending higher. The equipment sector continues to be the bedrock of the future of global technology, computing, and industrial automation, and it is seeing relentless chip miniaturization and smart ecosystems growth.


Send us a brief description of your challenge and we'll get back to you within 24 hours.
 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


