
Jul 16, 2026
By Transpire Insight
Description
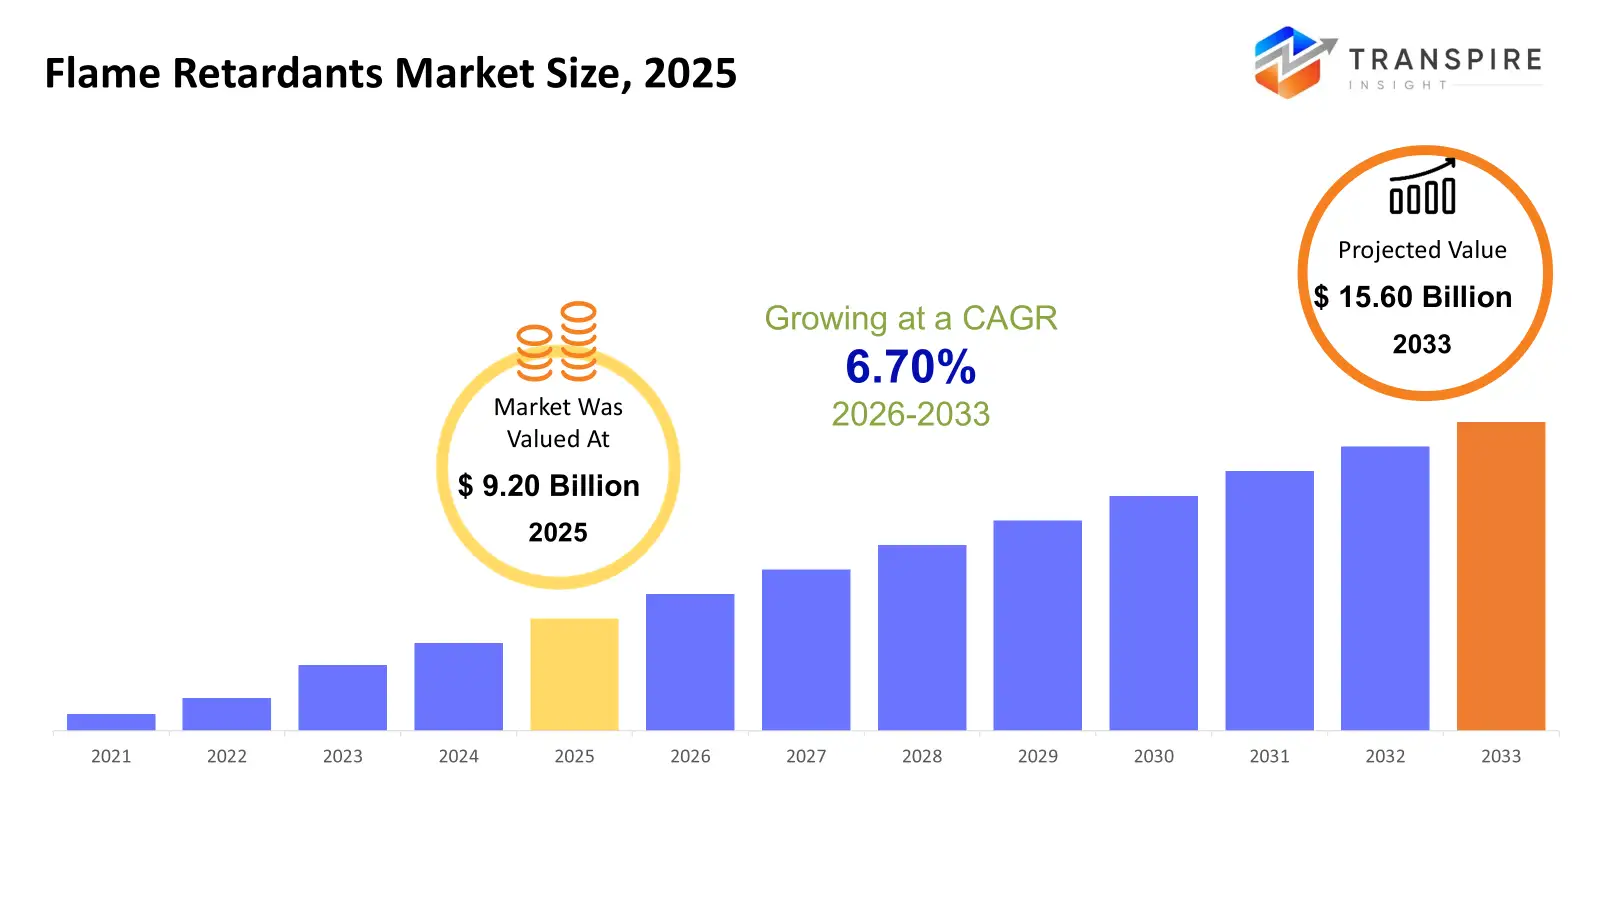
According to a research report published by Transpire Insight, the global flame retardants market size is projected to grow from USD 12.3 billion in 2026 to USD 19.02 billion by 2035, at a CAGR of 7.70% during the forecast period 2026-2035. The rising global electronic and automotive production, along with the rise in structural requirements for environment-friendly and halogen-free alternative compounds to replace conventional flame retardants, is the key factor driving the global flame retardants market.
Introduction
Flame retardants are integral components in protecting structural strength and reducing hazard risks all over the world in various manufacturing industries. These are embedded in the raw materials as special chemical components or as chemical reaction agents to help reduce ignition times and the speed at which flames spread in ignitable materials. The present market trends reflect the trend away from traditional halogenated products, driven by the rigorous environmental regulations. Rather, the industry is moving rapidly into sustainable, bio-based, and non-halogenated alternatives to meet the high-density electric vehicle (EV) battery architectures and current building codes.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Flame Retardants Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Global Flame Retardants Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
Asia Pacific is anticipated to generate the highest demand during the forecast period in the flame retardants market. It is expected that the Asia-Pacific region will witness the highest growth rate during the forecast period due to increasing demand for electronics, growing fleets of consumer vehicles, increased construction of building programs, and significant investment in electronics infrastructure. China, India, Japan, and South Korea are some of the rapidly growing nations regarding industrial manufacturing activities that drive the demand for advanced flame retardant technologies. In 2026, there will be an increase in the facility modernization programs by many chemical companies in China and India. This was done with the aim of ensuring energy-efficient flame-retardant systems.
North America is expected to exhibit steady development during the forecast period in the flame retardants market. The market is supported by the availability of leading players in terms of chemical manufacturing companies, polymer technology suppliers, and robust investment in construction. The United States is currently the biggest producer in the regional market, considering factors such as the presence of extensive electric vehicle manufacturing operations, efforts toward modernizing infrastructure safety, and continued advancement in chemical engineering. As of 2025, some of the chemical companies in the United States have undertaken production activities aimed at manufacturing superior flame retardants that would enhance next-generation commercial and automotive materials.
Top 15 Trends in the Flame Retardants Market
1.Halogen-Free Shift
The industries are shifting toward Halogen-free FRs that are composed of phosphorus, nitrogen and mineral compounds, yielding reduced smoke and toxic gas during combustion, and enhancing safety and sustainability.
Increasingly, battery packs need to be coated with phosphorus-nitrogen to ensure thermal and fire resistance, which is a key growth driver for electric mobility applications.
The International Fire Code reduced allowable flame spread and smoke development indices causing specifiers to use intumescent coatings and non-halogen building materials.
ECHA's proposal for restriction of deca-BDE also prompted redesign to aluminum diethylphosphinate and melamine polyphosphate, and states in the U.S. have identified legacy chemicals as priority hazards.
The electrical and electronics market segment had the largest market share at 41.5% in 2026, due to miniaturization and the increasing power density of devices.
Artificial Intelligence is the rising technology to advance the flame retardants market by streamlining the research and development (R&D) process and boosting the accuracy of tests, thereby boosting the rate of discovering new formulations.
Customize the exclusive Flame Retardants Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
Top 25 Companies Leading the Flame Retardants Market
Top 25 Companies Leading the Flame Retardants Market
1. Albemarle Corporation
Globally recognized as a premier provider of highly specialized brominated solutions.
Founded: 1887 | HQ: Charlotte, North Carolina, USA.
Why It Ranks: Holds massive global mineral reserves and scales production across broad regions.
Regional Dominance: Maintains top market shares throughout major heavy industrial manufacturing corridors.
Product Line: Delivers high-performance Saytex brominated additives built for robust polymer stabilization.
2. BASF SE
Integrates flame retardancy across an immense ecosystem of premium base plastics.
Founded: 1865 | HQ: Ludwigshafen, Germany
Why It Ranks: Leverages massive Verbund manufacturing setups to engineer highly specialized compounds.
Regional Dominance: Commands an extensive footprint, shaping Central Europe's engineering plastic standards.
Product Line: Focuses on premium Melapur nitrogen-based solutions targeting delicate electronic components.
3. ICL Group Ltd.
Utilizes direct access to unique Dead Sea resources for raw materials.
Founded: 1968 | HQ: Tel Aviv, Israel
Why It Ranks: Integrates raw mining extraction directly with advanced chemical synthesis operations.
Regional Dominance: Supplies extensive downstream networks crossing into European and American territories.
Product Line: Offers Fyrol and Mer-reducing phosphorus additives alongside versatile brominated products.
4. LANXESS AG
Shifting product pipelines heavily toward sustainable phosphorus-based safety material technologies.
Founded: 2004 | HQ: Cologne, Germany
Why It Ranks: Drives high-performance innovations replacing restricted legacy additives in global logistics.
Regional Dominance: Holds structural dominance across automotive and industrial molding hubs in Europe.
Product Line: Markets the specialized Disflamoll and Levagard organophosphorus product compound families.
4. Clariant AG
Pioneers of high-end non-halogenated innovations catering specifically to micro-scale electronics fields.
Founded: 1995 | HQ: Muttenz, Switzerland.
Why It Ranks: Dictates industry standards for sustainable development using bio-compatible chemical formulations.
Regional Dominance: Extends broad technological influence directly across Asian consumer electronics markets.
Product Line: Manufactures the flagship Exolit brand featuring highly stable, halogen-free phosphinates.
5. Italmatch Chemicals S.p.A.
Focuses operations exclusively on complex functional phosphorus and phosphonate additive synthesis.
Founded: 1997 | HQ: Genoa, Italy.
Why It Ranks: Acquires strategic niche companies to construct a comprehensive additive portfolio.
Regional Dominance: Maintains a deep, versatile supply infrastructure anchoring Mediterranean manufacturing hubs.
Product Line: Distributes Phoslite compounds tailored perfectly for delicate engineering thermoplastic formulations.
6. Huber Engineered Materials
Dominates global production pipelines for eco-friendly, non-toxic mineral thermal fillers.
Founded: 1883 | HQ: Atlanta, Georgia, USA.
Why It Ranks: Offers world-class surface modification technologies that optimize highly filled polymer compounds.
Regional Dominance: Controls expansive distribution lines servicing massive wire and cable industries.
Product Line: Processes widely utilize Hydral and Martinal alumina trihydrate smoke suppressants.
7. Nabaltec AG
Specializes deeply in ultra-pure, eco-friendly mineral-based chemical insulation systems globally.
Founded: 1994 | HQ: Schwandorf, Germany.
Why It Ranks: Delivers high-temperature performance grades that allow problem-free plastic extrusion processing.
Regional Dominance: Coordinates tightly with premium European infrastructure cable and piping formulators.
Product Line: Ships high-purity Apyral aluminum hydroxide and APYMAG magnesium hydroxide lines.
8. Dow Inc.
Incorporates fire safety science directly into broad silicone and elastomer technologies.
Founded: 1897 | HQ: Midland, Michigan, USA.
Why It Ranks: Deploys massive research budgets to integrate fire protection inside multi-layer materials.
Regional Dominance: Anchors major chemical supply chains stretching throughout the Western Hemisphere.
Product Line: Manufactures customized silicone-based additive modifiers that drastically mitigate heat release.
9. Adeka Corporation
Creates unique intumescent technologies that react actively when exposed to fire.
Founded: 1917 | HQ: Tokyo, Japan.
Why It Ranks: Solves complex polymer degradation challenges through precision Japanese chemical design.
Regional Dominance: Powers crucial semiconductor and electric vehicle hubs across East Asian territories.
Product Line: Features the advanced Adeka Stab FP family, providing high-efficiency char-forming protection.
10. Avient Corporation
Formulates customized polymer masterbatches directly matching specific client factory setups.
Founded: 2000 | HQ: Avon Lake, Ohio, USA.
Why It Ranks: Bridges the technical gap between raw chemical producers and plastic molders.
Regional Dominance: Runs responsive localized compounding facilities spread across diverse global markets.
Product Line: Designs localized OnCap flame-retardant concentrates tailored to custom processing constraints.
Schedule a meeting with our market experts to discuss the exclusive Flame Retardants Market report and identify the best research solution for your organization.
Conclusion
The flame retardants market is undergoing a structural change, with regulations and changing end-user expectations. With global building codes and automotive electrification raising safety standards, Tier-1 suppliers are successfully shifting to low-toxicity, halogen-free and high-purity versions of minerals and phosphorus. The group will ensure strong market progress into the next decade. It is a key sector in materials engineering and also plays an essential balancing act between essential fire protection and the required environmental stewardship.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


