
Jul 16, 2026
By Transpire Insight
Description
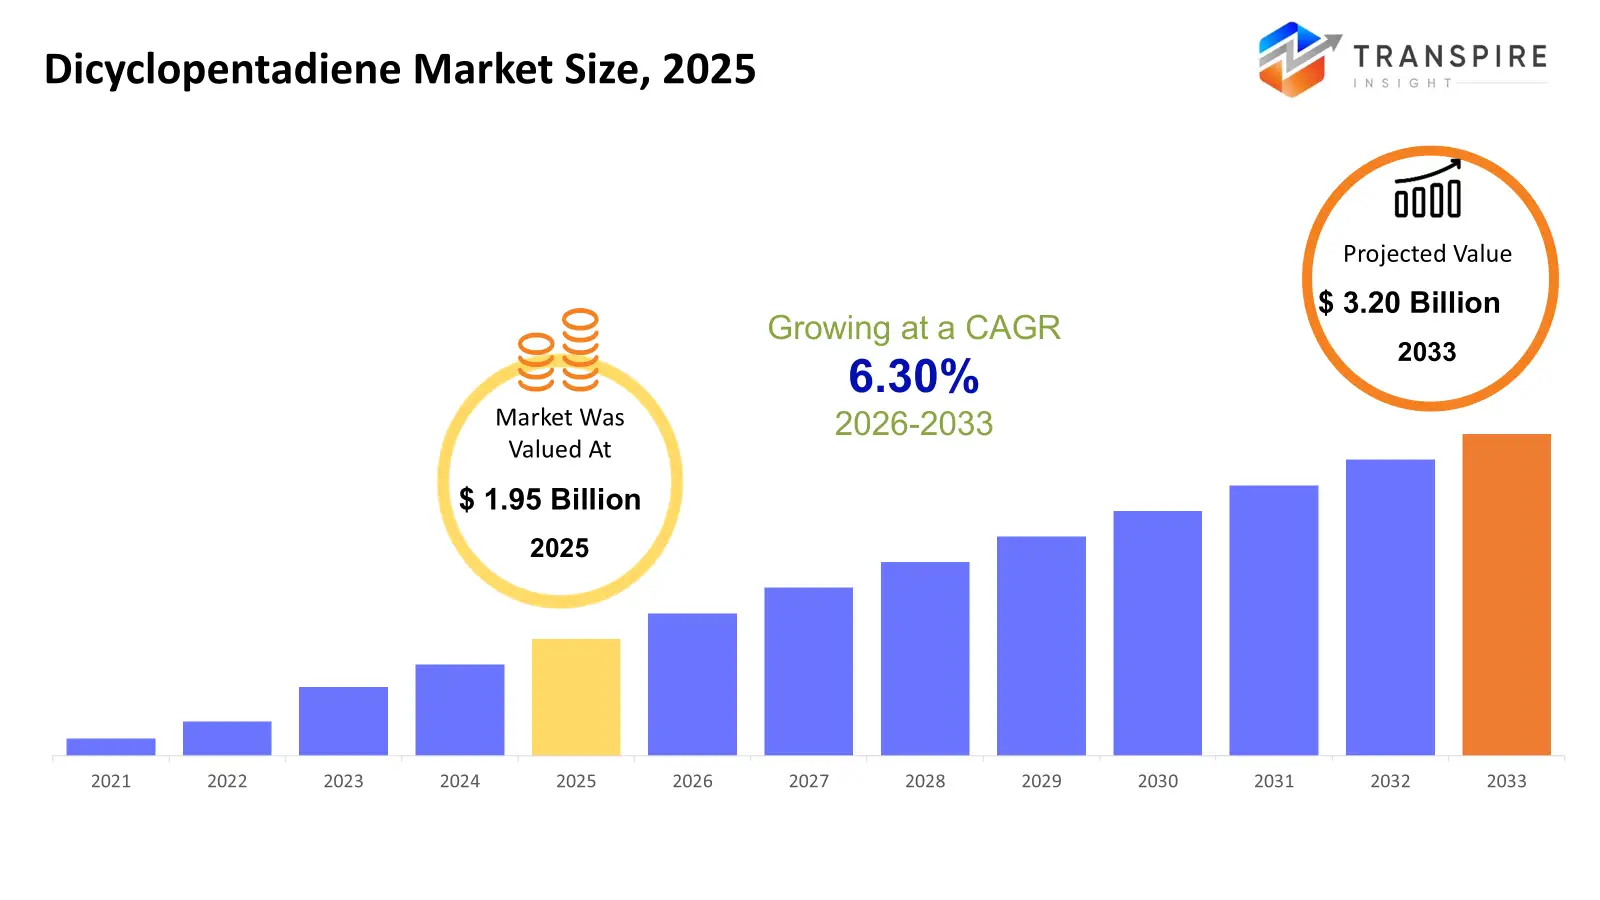
According to a research report published by Transpire Insight, the global dicyclopentadiene market size is projected to grow from USD 3.05 billion in 2026 to USD 6.20 billion by 2035, at a CAGR of 8.30% during the forecast period 2026-2035. The market is powered by increasing applications of automotive composites with lightweight and high strength, and growing wind power systems. Substantial growth is also driven by an increase in consumption of unsaturated polyester resins (UPR) used in worldwide construction.
Introduction
Dicyclopentadiene (DCPD) is a highly reactive, cyclic hydrocarbon byproduct obtained from the steam cracking of naphtha and crude oil fractions. It is used as an important chemical intermediate, mainly used for the production of unsaturated polyester resins, hydrocarbon resins, and EPDM elastomers. Due to its high durability, low weight, and resistance to damp, DCPD is an essential component used in many modern heavy industries such as automotive, marine, construction, and electronics. It is highly valued for its performance in high-stress infrastructure applications.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Dicyclopentadiene Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Dicyclopentadiene Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
North America's leadership is underpinned by a mature, well-integrated petrochemical infrastructure concentrated along the U.S. Gulf Coast, where established producers benefit from reliable feedstock access and decades of downstream resin manufacturing expertise. Strong demand from the automotive, construction, and paints & varnishes industries continues to anchor regional consumption, while producers steadily expand capacity to serve both domestic and export markets. The region's advanced manufacturing base and consistent investment in composite materials for automotive and industrial applications keep it ahead of other regions in absolute revenue terms. In a 2025 development, ExxonMobil Chemical Company announced plans to expand its DCPD production capacity by 20% at its Baton Rouge, Louisiana, facility, with completion expected in 2026 to meet growing demand from the adhesives and coatings industries.
Asia Pacific's accelerated growth is fueled by expanding automotive and construction sectors across China, India, Japan, and South Korea, where rising use of unsaturated polyester resin in electrical, electronic, and infrastructure applications continues to lift regional consumption. Government initiatives supporting construction and green-building development in emerging economies like India and China are reinforcing this momentum, alongside growing demand for plastics, adhesives, and coatings across the region. Producers are actively expanding local capacity to keep pace with this demand curve rather than relying solely on imports. In a notable 2025-2026 development, China National Petroleum Corporation announced a joint venture with Germany's BASF SE to build a new DCPD production plant in China with an annual capacity of 100,000 metric tons, expected to become operational by 2026.
Top 15 Trends in the Dicyclopentadiene Market
Proceed to Checkout to purchase the exclusive Dicyclopentadiene Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
Automakers increasingly use DCPD-based poly-DCPD composites in body panels and structural parts to cut vehicle weight, boost fuel efficiency, and meet strict emission regulations globally.
Specialty polymer and electronic-grade applications are driving demand for high-purity DCPD grades above ninety-nine percent, supporting advanced coatings, cyclic olefin copolymers, and precision electronic components.
Expanding wind turbine installations are boosting demand for poly-DCPD reaction injection molding composites, valued for lightweight strength and durability in large-scale blade and nacelle components.
New petrochemical steam cracker capacity additions across Asia and the Middle East are improving C5 hydrocarbon feedstock availability, supporting downstream DCPD production and derivative manufacturing.
Boat and hull manufacturers favor DCPD-modified resin systems for their superior corrosion resistance and structural strength, driving steady fiberglass-reinforced plastic demand across marine markets.
Refinery modernization and petrochemical integration projects across Saudi Arabia, the UAE, and South Africa are expanding export-oriented DCPD capacity, strengthening the Middle East's supply role.
Top 25 Companies Leading theDicyclopentadiene Market
Customize the exclusive Dicyclopentadiene Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. ExxonMobil Chemical
Large-scale hydrocarbon cracking yields massive quantities of essential dicyclopentadiene monomers daily.
Founded: 1999 | HQ: Spring, Texas, USA.
Why it Ranks: Leading integration with extensive steam crackers secures a dominant global volume advantage.
Regional Dominance: Massive infrastructure cements absolute market supremacy across North America and Europe.
Product Line: High-purity and resin-grade DCPD tailored for specialty adhesives and polymers.
2. Chevron Phillips Chemical Company
Co-product streams from the Texas facility fuel the regional dicyclopentadiene distribution engine.
Founded: 2000 | HQ: The Woodlands, Texas, USA.
Why it Ranks: Deep upstream integration guarantees highly consistent crude dicyclopentadiene supplies annually.
Regional Dominance: A strong logistical footprint asserts reliable commercial control across American manufacturing hubs.
Product Line: Heavy olefin co-products alongside raw crude dicyclopentadiene for specialized refinement.
3. Shell Chemicals
Heavy crackers isolate premium chemical building blocks for diverse industrial application needs.
Founded: 1929 | HQ: London, United Kingdom.
Why it Ranks: Unmatched historical expertise in petrochemical optimization secures massive enterprise market share.
Regional Dominance: Extensive supply networks maintain an airtight, unshakeable monopoly throughout European markets.
Product Line: Multi-tier chemical feedstocks including optimized dicyclopentadiene grades for industrial synthesis.
4. LyondellBasell Industries
Advanced olefins processing yields high-quality cyclic intermediates utilized across major industries.
Founded: 2007 | HQ: Houston, Texas, USA.
Why it Ranks: Giant manufacturing scale establishes them as a vital backbone for global buyers.
Regional Dominance: Dual-headquartered leverage ensures formidable, seamless market coverage across transatlantic territories.
Product Line: Premium olefins, cyclic dienes, and polyolefins engineered for performance-driven products.
5. Braskem S.A.
Sustainable chemical initiatives drive the production of essential thermoplastic resin precursors.
Founded: 2002 | HQ: São Paulo, Brazil.
Why it Ranks: Absolute command over South American refining infrastructure guarantees unmatched regional market placement.
Regional Dominance: Leading Latin American operations control supply dynamics across the southern hemisphere.
Product Line: Special chemical intermediates and high-performance resins containing critical dicyclopentadiene components.
6. Dow Inc.
Material science innovation leverages robust hydrocarbon outputs to create advanced materials.
Founded: 1897 | HQ: Midland, Michigan, USA.
Why it Ranks: Comprehensive portfolio synergy transforms basic chemical feeds into lucrative consumer plastics.
Regional Dominance: Extensive production facilities command massive industrial authority throughout global manufacturing sectors.
Product Line: Special monomers, synthetic elastomers, and high-value performance materials using dicyclopentadiene.
7. Eastman Chemical Company
Specialized resin manufacturing processes transform crude hydrocarbons into highly stable tackifiers.
Founded: 1920 | HQ: Kingsport, Tennessee, USA.
Why it Ranks: Strategic mastery of downstream formulations elevates demand for their specialty resins.
Regional Dominance: Deep domestic integration satisfies exact technical specifications within the American market.
Product Line: High-quality hydrocarbon resins, specialized tackifiers, and modified performance polymer additives.
8. Zeon Corporation
Specialized C5 fraction separation chemistry creates ultra-high-purity cyclo-olefin polymer products.
Founded: 1950 | HQ: Tokyo, Japan.
Why it Ranks: Global leadership in ultra-high-purity grades dictates premium medical material standards.
Regional Dominance: Technological superiority secures unmatched market share across advanced Asian electronics fabrication.
Product Line: High-purity dicyclopentadiene alongside advanced cyclo-olefin polymers for optical applications.
9. Kolon Industries
Hydrocarbon resin synthesis delivers critical binding agents for global adhesive markets.
Founded: 1957 | HQ: Seoul, South Korea.
Why it Ranks: Massive production capacities for hydrogenated resins meet heavy global export demands.
Regional Dominance: Deep Asian industrial roots power vast distribution networks into western economies.
Product Line: Premium hydrogenated hydrocarbon resins tailored for tires, inks, and adhesives.
10. ENEOS Corporation
Integrated crude oil refining produces vital raw aromatics for industrial manufacturing.
Founded: 1888 | HQ: Tokyo, Japan.
Why it Ranks: Core domestic oil refining dominance ensures steady, uninterrupted access to feedstocks.
Regional Dominance: Pivotal refining infrastructure controls critical supply lines throughout the East Asian sector.
Product Line: Major petrochemical commodities alongside refined dicyclopentadiene fractions for downstream industries.
Schedule a meeting with our market experts to discuss the exclusive Dicyclopentadiene Market report and identify the best research solution for your organization.
Conclusion
The dicyclopentadiene market is dominated by integrated oil companies and experts in material science. ExxonMobil and Shell are among the firms that use huge upstream steam cracking to achieve volume superiority. At the same time, Asian original equipment manufacturers (OEMs) such as Zeon and Kolon control high-dollar downstream applications in electronics and advanced resins. Geographically, production continues to focus around large refining centres in North America, Europe, and Asia. The top tenplayers's controlling capacity will keep shaping global supply dynamics, as demand for their products grows in both the automotive and construction sectors.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


