
United Kingdom Chemical Mechanical Planarization Market Size & Forecast:
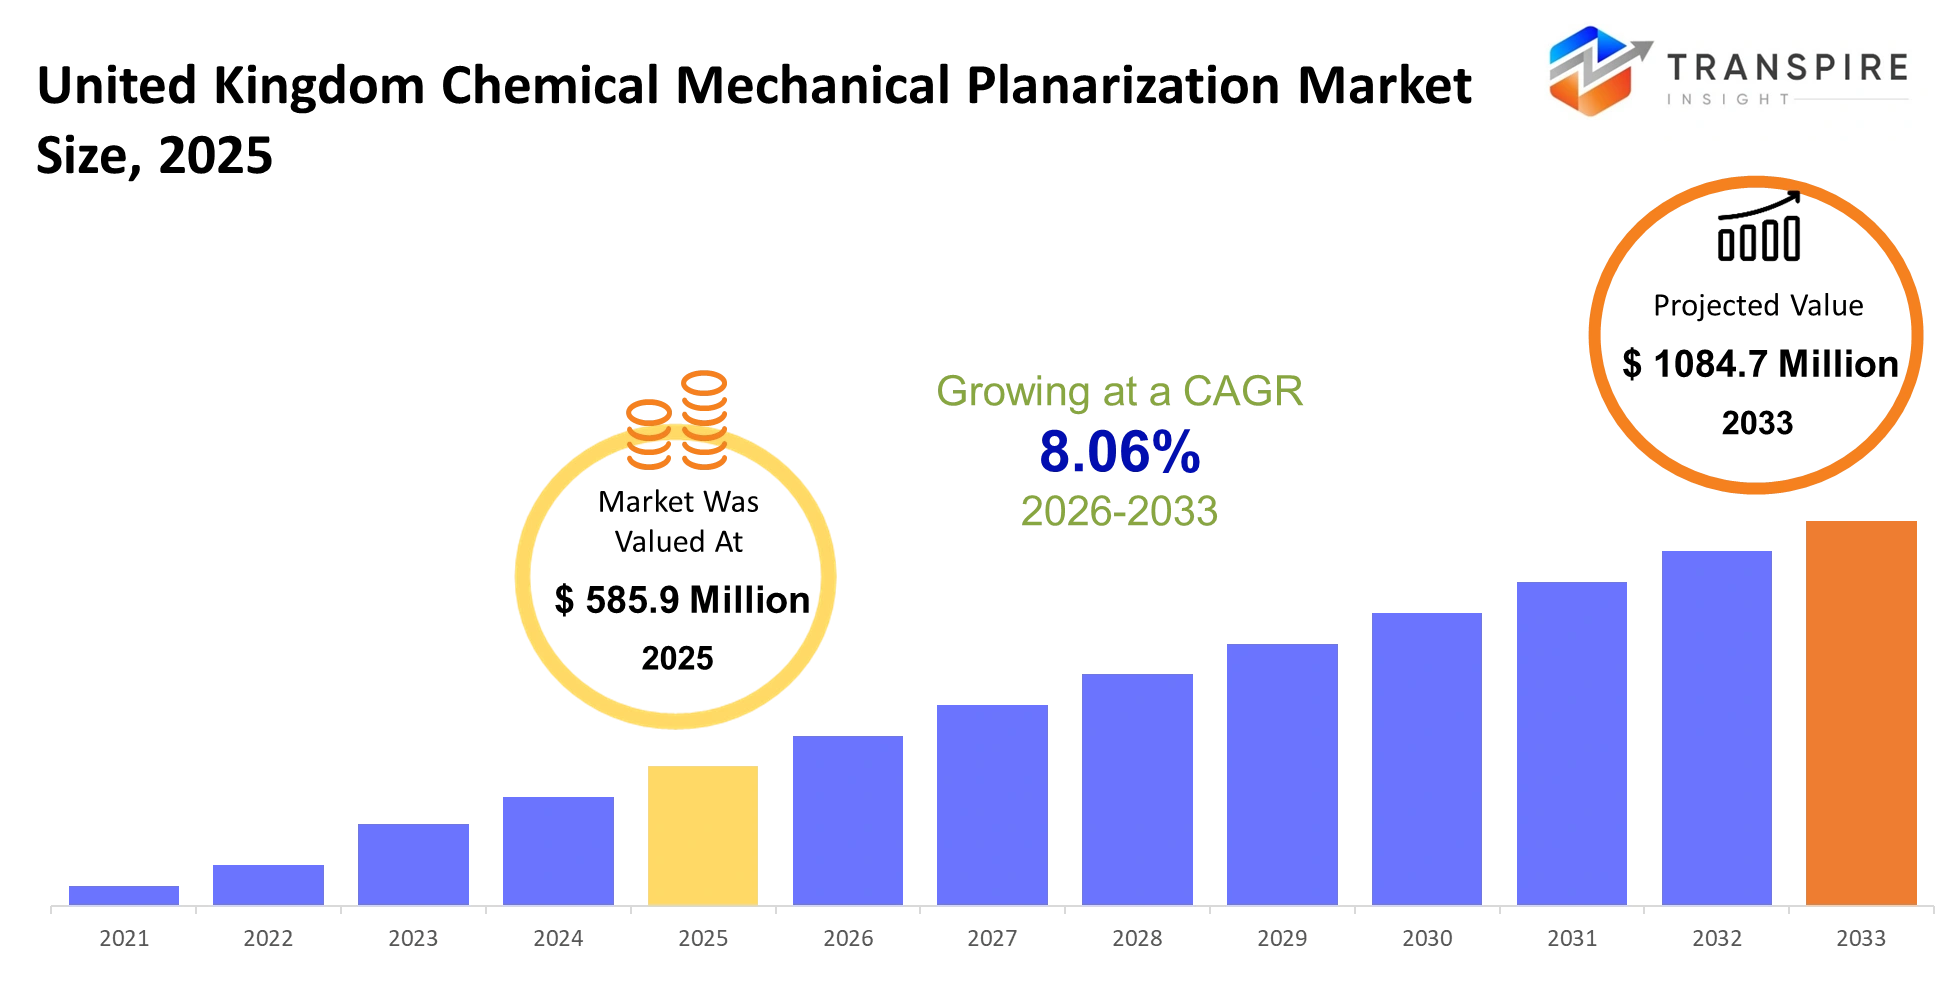
- United Kingdom Chemical Mechanical Planarization Market Size 2025: USD 585.9 Million
- United Kingdom Chemical Mechanical Planarization Market Size 2033: USD 1084.7 Million
- United Kingdom Chemical Mechanical Planarization Market CAGR: 8.06%
- United Kingdom Chemical Mechanical Planarization Market Segments: By Product Type (CMP Slurries, CMP Pads, CMP Conditioning Discs, CMP Cleaning Chemicals, CMP Equipment, Others); By Application (Semiconductor Fabrication, MEMS Manufacturing, Data Storage Devices, Optoelectronics, Advanced Packaging, Others); By Material (Silica-based Slurries, Ceria-based Slurries, Polyurethane Pads, Diamond Conditioning Discs, Others); By End User (Semiconductor Foundries, IDMs, Electronics Manufacturers, Research Institutes, Others); By Technology (Copper CMP, Tungsten CMP, Dielectric CMP, Silicon CMP, Others).
To learn more about this report,  Download Free Sample Report
United Kingdom Chemical Mechanical Planarization Market Summary
The United Kingdom Chemical Mechanical Planarization Market was valued at USD 585.9 Million in 2025. It is forecast to reach USD 1084.7 Million by 2033. That is a CAGR of 8.06% over the period.
Chemical mechanical planarization (CMP) has a big, kind of make it smoother and flatter effect in the United Kingdom’s semiconductor and advanced electronics manufacturing line, especially during chip production. In real day to day terms it helps makers level out wafer surfaces so you can keep building smaller, faster, and more power-efficient devices, and also avoid defects that show up when material layers end up uneven. Over the last five years, the market seems to have moved away from just supporting conventional semiconductor fabrication, and more into advanced node packaging, compound semiconductors, plus high-performance computing uses. Because of this, people are asking for more specialized stuff like slurries, polishing pads, and even tighter precision CMP hardware.
One major trigger came after the global semiconductor supply chain got disrupted, starting with the COVID-19 period, and then with escalating geopolitical tensions tied to chip exports. Those events really highlighted how the UK leaned on overseas semiconductor infrastructure, and they also sped up domestic investment in chip research, photonics, and wafer processing know-how. Now, as manufacturers push for higher chip yields and stricter production tolerances, CMP adoption is going up, not because it’s fashionable, but because even production errors at the nanometer scale can directly impact device reliability, manufacturing cost, and the overall commercial output.
Key Market Insights
- The United Kingdom Chemical Mechanical Planarization Market, kind of benefits from the rising adoption of AI processors ,5G infrastructure chips and also high-performance computing semiconductor apps.
- Advanced semiconductor packaging technologies also took more of the market in 2025, mostly because UK manufacturers really leaned into defect-free wafer surface finishing capabilities. It wasn’t just one thing though.
- On the demand side you see expanding electric vehicle electronics production, compound semiconductor research, and government-backed semiconductor resilience programs happening across the United Kingdom.
- When you look at consumables, slurry consumables pretty much lead the United Kingdom Chemical Mechanical Planarization Market with around 42% industry share, mainly due to those recurring replacement cycles inside wafer fabrication facilities.
- CMP polishing pads sit in the second-largest segment, and that’s tied to higher production volumes in precision microelectronics and integrated circuit manufacturing operations.
- Advanced CMP equipment is kinda the fastest growing segment through 2031, since fabs need nanometer level planarization accuracy for smaller chip layouts and all kinds of architectures.
- Regionally , England is pulling in the most revenue, with roughly 68% share in 2025 , backed by semiconductor research hubs and electronics production infrastructure.
- Scotland is expected to be the fastest growing regional market during the forecast window, mostly because the compound semiconductor , and photonics industries keep expanding.
- For end users, semiconductor fabrication plants stay #1, holding nearly 55% market share, and that’s supported by growing domestic wafer processing investment.
- Finally, research institutes and photonics laboratories are expected to grow the quickest, due to increasing public-private semiconductor innovation partnerships, plus all the related R&D momentum.
What are the Key Drivers, Restraints, and Opportunities in the United Kingdom Chemical Mechanical Planarization Market?
The primary driver shaping the United Kingdom Chemical Mechanical Planarization Market is the country’s renewed push toward semiconductor capability expansion after the global chip shortage kind of showed supply vulnerabilities across automotive, telecom, and defense. With government-backed semiconductor initiatives plus private investment in compound semiconductors, the procurement of advanced wafer processing technologies, including CMP systems, really picked up. That technology shift directly boosts revenue opportunities for slurry suppliers, polishing pad manufacturers, and equipment providers, because advanced chips basically need several planarization stages to keep production accuracy steady at smaller process nodes.
The biggest restraint is that the United Kingdom has limited large-scale semiconductor fabrication infrastructure compared with the United States and parts of East Asia. To build modern fabrication facilities you’re talking multibillion-pound capital commitments, long construction timelines, and a steady supply of highly specialized engineering talent. This structural issue hampers the immediate expansion of CMP equipment deployment, and it also lowers economies of scale for domestic consumable suppliers. so, some parts of the market still lean on imported semiconductor manufacturing capacity, which quietly suppresses local revenue generation.
A major opportunity is also showing up, due to the rapid development of compound semiconductor and photonics clusters in regions such as South Wales and Scotland. Investments that lean into gallium nitride and silicon carbide technologies, for electric vehicles, aerospace electronics, and 5G systems is pushing up demand for super high-precision planarization processes, sort of tuned for next generation materials.
What Has the Impact of Artificial Intelligence Been on the United Kingdom Chemical Mechanical Planarization Market?
Artificial intelligence and advanced digital technologies are, sort of, reshaping chemical mechanical planarization operations in the United Kingdom by boosting process precision, cutting down wafer defects, and generally squeezing more efficiency out of semiconductor production. More and more semiconductor makers are folding AI-enabled control systems into CMP hardware, so they can watch slurry flow rates, polishing pressure, pad wear , and wafer surface uniformity all at once, in real time. These automated monitoring platforms let fabs hold tighter process tolerances for advanced node manufacturing, where even tiny surface unevennesses can hurt chip yield.
Also, machine learning models are being put into practice for predictive maintenance across polishing tools and consumable setups. When they analyze vibration signals, temperature tendencies, and equipment utilization rates, predictive methods can spot likely component failures ahead of time, before any production stoppage pops up. Several companies mentioned clear gains in equipment uptime, along with less consumable waste, since smarter scheduling reduces those sudden maintenance shutdowns and keeps polishing behavior steadier. On top of that, AI-assisted process optimization is helping fabs trim energy use and reduce slurry usage per wafer, which really ties back to cost effectiveness in high-volume semiconductor environments.
Still, AI adoption runs into a major constraint. The integration cost can be heavy, especially for retrofitting older fabrication equipment with upgraded sensors, stronger data infrastructure , and real-time analytics. A lot of smaller facilities also do not have enough historical process data to train reliable machine learning models for the more complicated planarization workflows.
Key Market Trends
- Between 2021 and 2025, UK semiconductor manufacturers put more money into advanced wafer planarization tools, to back smaller process node chip production or so they said. And yeah, the direction kept moving, especially as the fab side wanted tighter control.
- Since 2022, compound semiconductor projects in South Wales and Scotland, shifted CMP demand toward silicon carbide plus gallium nitride wafer processing applications, rather than the older silicon-only approach.
- CMP slurry suppliers then introduced lower-defect formulations after advanced packaging adoption increased multi-layer wafer polishing complexity, across high-performance computing applications too.
- Semiconductor fabs increasingly adopted AI-enabled polishing control systems, after manufacturers reported measurable reductions in wafer defect density, and also in consumable waste since 2023.
- After these global chip shortages, UK electronics makers sort of cut down on overseas semiconductor supply, then sped up domestic semiconductor processing agreements, plus infrastructure planning all in one go, you know.
- In 2024, firms like Applied Materials and Tokyo Electron pushed out process optimization tools, in order to reach better logic and memory fabrication efficiency , more or less.
- From 2020 to 2025, CMP equipment buyers were basically focusing on predictive maintenance software, because unplanned fabrication downtime created bigger operational problems, and yield losses too, kinda quickly.
- At the same time, manufacturers leaned more into precision polishing pads with longer run times when consumable costs got more intense across semiconductor plants in 2024.
- And those research partnerships between universities and semiconductor companies, they grew faster once UK technology funding programs were more focused on photonics, quantum computing, and advanced materials development.
- Since 2023, environmental compliance standards pushed CMP operators to improve slurry waste treatment, and to reduce chemical discharge during wafer processes as well, they noted, during audits.
United Kingdom Chemical Mechanical Planarization Market Segmentation
By Product Type:
CMP slurry s , CMP pad s, CMP conditioning discs , CMP cleaning chemicals , CMP equipment, and a bunch of other supporting consumables shape how the United Kingdom Chemical Mechanical Planarization Market looks overall. CMP slurries sit right at the center, because wafer smoothing really relies on controlled chemical interaction plus abrasive action during the whole fabrication cycle. CMP pads and those conditioning discs help keep surface contact steady, while cleaning chemicals keep wafer purity on track. As for equipment, it supports end-to-end process integration, and in practice each product category works together so precision stays intact in semiconductor manufacturing.
Demand for CMP slurries and pads should keep climbing, mainly because semiconductor fabs are moving to smaller node production and the advanced packaging crowd now needs tighter control. Equipment uptake will grow too, since many manufacturers are pushing automation, and they want process stability , not surprises. Cleaning chemicals and conditioning discs will keep getting used at a steady pace because contamination control and pad performance are basically tied to wafer yield outcomes. In general, product development is expected to lean toward better efficiency and fewer defect rates across fabrication steps, even when the process window gets narrower.
By Application:
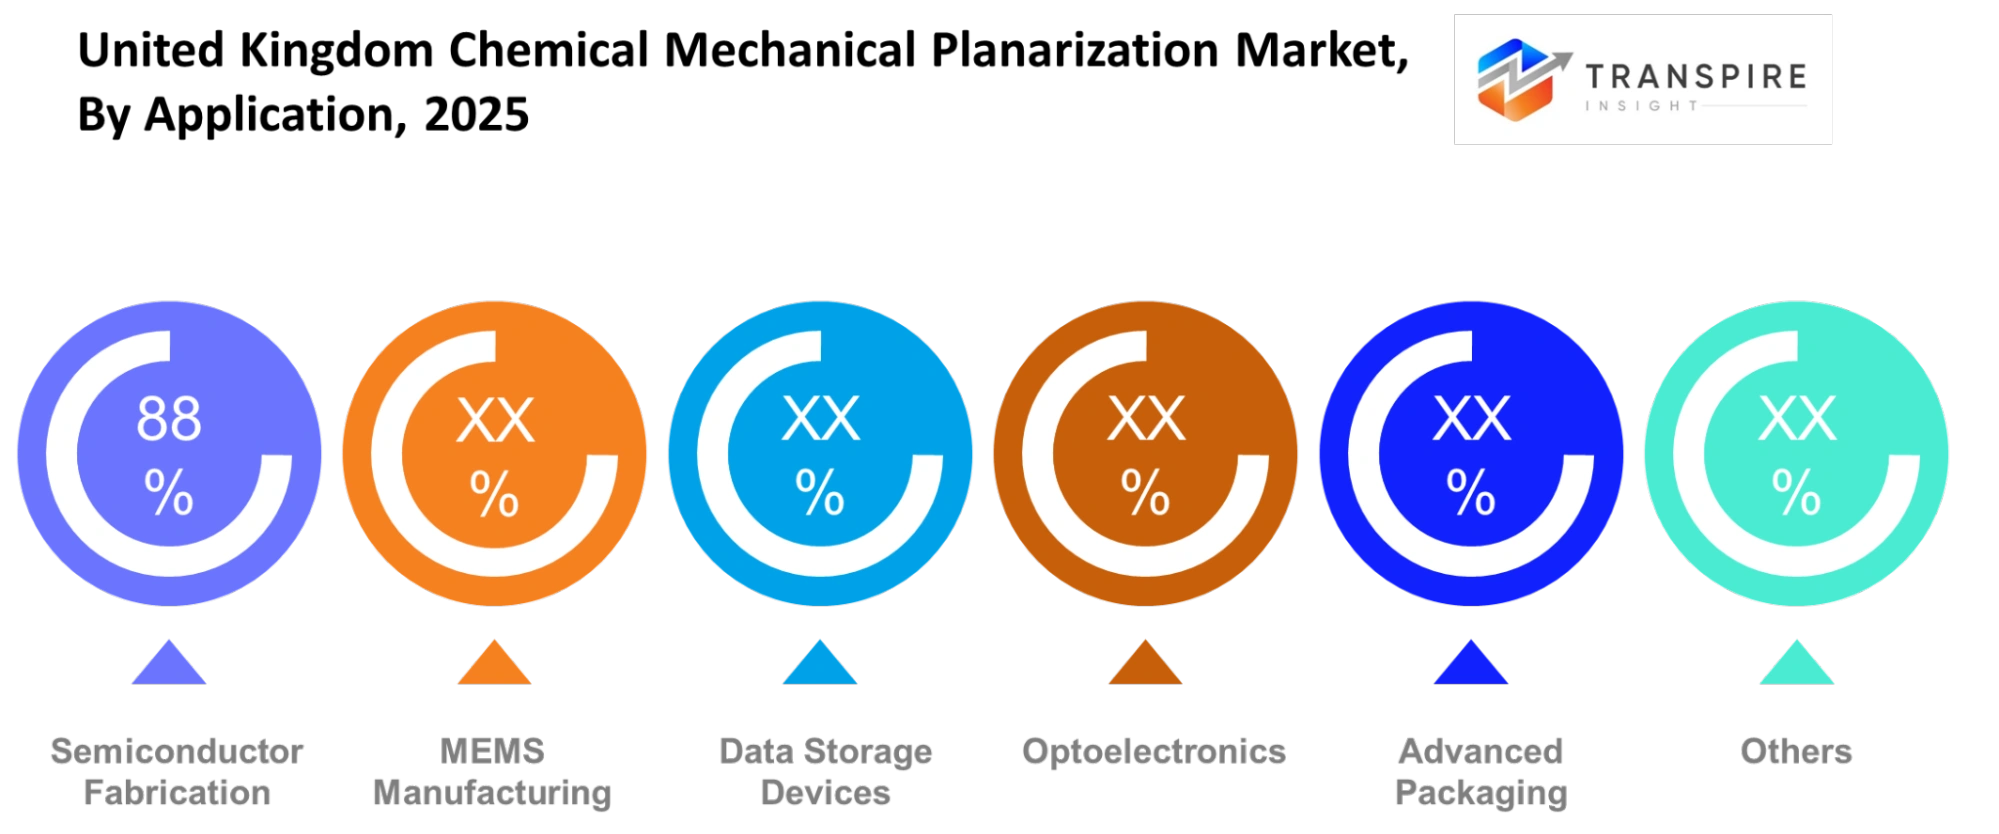
In the United Kingdom Chemical Mechanical Planarization Market, application demand is shaped by semiconductor fabrication, MEMS manufacturing, data storage devices, optoelectronics, advanced packaging, and a few other closely related uses. Semiconductor fabrication stays the main application because CMP is essential for creating those flat wafer surfaces needed for integrated circuits. MEMS manufacturing relies on CMP too, for precision micro device formation, and advanced packaging relies on multi-layer planarization in order to keep structures aligned.
Growth in advanced packaging applications is expected to happen quicker as chip designs turn more compact and increasingly layered for high performance computing and AI workloads. At the same time optoelectronics along with MEMS will keep expanding , driven by the rising adoption of sensors and communication systems. Data storage devices should keep fairly steady demand, helped by stronger reliability expectations. Overall the application direction is moving toward higher precision processes, and better yield efficiency across every segment, not just one corner of the market.
To learn more about this report, Download Free Sample Report
By Material:
Silica-based slurries, ceria-based slurries, polyurethane pads, diamond conditioning discs , and other materials pretty much make up the material foundation of the United Kingdom Chemical Mechanical Planarization Market. Silica-based slurries are widely used because they offer a nice, balanced polishing performance, while ceria-based slurries help with advanced dielectric planarization. Polyurethane pads give controlled surface interaction, and diamond conditioning discs ensure the pad regeneration plus stability, especially when things run at high volume.
Material demand will likely start shifting toward newer and more advanced formulations as chip designs get more complex and the surface tolerance requirements tighten , in practice. Ceria-based slurries will gain even more weight at advanced nodes, driven by the need for higher precision. Polyurethane pads will stay important, but they’ll probably improve in durability and overall effectiveness. Diamond conditioning discs are expected to get stronger utilization too, since fabs want steadier polishing efficiency and less time lost to downtime.
By End User:
Semiconductor foundries, integrated device manufacturers, electronics makers, research institutes, and other end users make up the demand base for the United Kingdom Chemical Mechanical Planarization Market, kinda like a layered ecosystem. Semiconductor foundries dominate usage, since large-scale wafer processing needs steady planarization cycles running without breaks. IDMs fold CMP into their own production workflows, whereas electronics manufacturers lean on CMP for device-level production too. Research institutes, meanwhile, back the push toward next-generation semiconductor technologies, and they do it with a more experimental angle than the rest.
Looking ahead, semiconductor foundries will probably stay in the lead as production volumes keep rising for advanced chips that power computing and communications. Research institutes may grow faster, because investments keep tilting toward photonics and compound semiconductors. Electronics manufacturers are also expected to bring in more CMP systems as device miniaturization keeps moving forward. IDMs will likely concentrate on boosting internal throughput and cutting down on reliance on outside supply, using more integrated manufacturing approaches overall.
By Technology:
Copper CMP, tungsten CMP, dielectric CMP, silicon CMP ,and other process technologies kinda define the whole technology structure for the United Kingdom Chemical Mechanical Planarization Market. Copper CMP is generally used for making the interconnect part, while tungsten CMP helps keep the contact layer smooth out. Dielectric CMP is the one that makes sure the insulation layer comes out planar, and silicon CMP is basically essential for prepping the wafer substrate.
As time goes on, technology evolution will shift toward more high precision copper and dielectric CMP processes, especially as chip architectures get more layered and tighter packed. Tungsten CMP should keep a steady demand, mostly because it still plays that contact formation role. Silicon CMP will back substrate-level upgrades for the newer advanced wafers. In general, the technology direction is likely to emphasize lowering defect density, boosting uniformity, and meeting the next generation semiconductor scaling needs, you know, with fewer issues overall.
What are the Key Use Cases Driving the United Kingdom Chemical Mechanical Planarization Market?
In the United Kingdom Chemical Mechanical Planarization Market, the biggest pull comes from semiconductor fabs, especially those running advanced logic and memory lines. Planarization here is the dominant step because it helps keep surface flatness tight, which then supports lithography yield and reduces rework. Even small waviness can ripple through the whole process, so buyers keep allocating more wafers to CMP tool capacity, it is kind of relentless demand.
After that, adjacent use cases are picking up pace in data center hardware and edge computing device plants. In these facilities, CMP supports reliable dielectric leveling and interconnect build outs for high density circuit boards and package substrates, which matters a lot for equipment makers serving the consumer electronics segment. Regulatory pressure around process control and waste handling also pushes consistent outcomes.
Looking forward, emerging use cases include compound semiconductor and power electronics, where thinner layers and tougher specs are starting to justify broader CMP adoption. Another early area is advanced packaging for medical electronics, driven by tighter performance expectations and qualification cycles, even if volumes are still modest.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 585.9 Million |
|
Market size value in 2026 |
USD 630.6 Million |
|
Revenue forecast in 2033 |
USD 1084.7 Million |
|
Growth rate |
CAGR of 8.06% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Middle East and Africa (Saudi Arabia, United Arab Emirates, South Africa, Rest of Middle East and Africa) |
|
Key company profiled |
Applied Materials, Ebara Corporation, Entegris, Cabot Microelectronics, DuPont, Fujimi Corporation, Lapmaster Wolters, Logitech Ltd., KCTech, Revasum, Okamoto Machine Tool Works, SK enpulse, Versum Materials, Saint-Gobain, 3M. |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (CMP Slurries, CMP Pads, CMP Conditioning Discs, CMP Cleaning Chemicals, CMP Equipment, Others); By Application (Semiconductor Fabrication, MEMS Manufacturing, Data Storage Devices, Optoelectronics, Advanced Packaging, Others); By Material (Silica-based Slurries, Ceria-based Slurries, Polyurethane Pads, Diamond Conditioning Discs, Others); By End User (Semiconductor Foundries, IDMs, Electronics Manufacturers, Research Institutes, Others); By Technology (Copper CMP, Tungsten CMP, Dielectric CMP, Silicon CMP, Others). |
Which Regions are Driving the United Kingdom Chemical Mechanical Planarization Market Growth?
England is leading the United Kingdom Chemical Mechanical Planarization Market, mostly because it has the strongest cluster of semiconductor research locations, advanced electronics build hubs, and government backed chip programs. There’s been real policy help for keeping domestic semiconductor ability growing, and that has encouraged people to keep investing, especially in wafer fabrication and precision materials processing. Also, having well-known supply routes for equipment, chemicals, and engineering talent helps production stay steady. Bigger research partnerships, between universities and industry, keep pushing new ideas in the planarization processes. So, this whole ecosystem keeps England right at the middle of high value CMP adoption, and even supports advanced node trials .
Scotland meanwhile contributes pretty steadily to the United Kingdom Chemical Mechanical Planarization Market with an industrial base that is smaller, but more niche, and more innovation driven. Unlike England, Scotland’s edge leans toward compound semiconductors and photonics, not huge scale wafer fabrication. Regional money is fairly consistent, and academic,industry links keep running in a dependable way. Electronics companies and research bodies continue with routine buying cycles for precision materials and polishing systems. That overall steadiness makes Scotland a dependable contributor, even if it does not match the same manufacturing volume you see in England .
Northern Ireland is showing the quickest sort of growth in the United Kingdom Chemical Mechanical Planarization Market, because of recent expansion in advanced electronics and precision engineering investment. New industrial development programms, and upgraded manufacturing facilities have basically pushed the adoption of semiconductor processing tools along. At the same time increased involvement in UK wide semiconductor resilience initiatives has made it easier to access advanced fabrication technologies, and that seems to be helping a lot. Overall this change is really pointing toward a move into localized capability building, not so much import dependence anymore.
For investors and market entrants, this region offers early stage opportunities with meaningful upside potential from 2026 to 2033, as the infrastructure maturity keeps improving.
Who are the Key Players in the United Kingdom Chemical Mechanical Planarization Market and How Do They Compete?
The United Kingdom Chemical Mechanical Planarization Market seems to have a moderately consolidated competitive landscape, mostly led by global semiconductor equipment and materials suppliers, not so much by local manufacturers. What really makes the competition move is technology performance, process accuracy , and how well the long-term service actually fits with fabrication facilities. The established players defend their standing with sophisticated process control systems and carefully engineered consumables, but for new entrants it can be rough, mostly because the capital requirements are huge and semiconductor fabs are strict about qualification. Buyers care a lot about lowering defects and keeping yield steady, so the rivalry ends up circling innovation, rather than just competing on pricing.
Applied Materials holds its ground using more advanced CMP equipment platforms, the kind that fold in process monitoring and automation, that in turn helps improve wafer uniformity for leading-edge nodes. Tokyo Electron leans into high precision engineering, and keeps expanding via partnerships with semiconductor foundries, so the tools line up with next generation chip architectures. DuPont, meanwhile, stands apart through slurry chemistry advancement, working on formulations intended to cut down defect rates for advanced packaging, and also for high density interconnect layers.
Cabot Microelectronics competes by optimizing the consumable lifecycle, offering polishing pads and slurries that are designed for longer operational stability, plus a better cost per wafer over time. Ebara Corporation expands by strengthening its CMP equipment service coverage and by pushing improved tool uptime support across Europe, which helps manufacturers reduce production interruptions and keep output quality more consistent.
Company List
- Applied Materials
- Ebara Corporation
- Entegris
- Cabot Microelectronics
- DuPont
- Fujimi Corporation
- Lapmaster Wolters
- Logitech Ltd.
- KCTech
- Revasum
- Okamoto Machine Tool Works
- SK enpulse
- Versum Materials
- Saint-Gobain
- 3M
Recent Development News
In April 2026, Advanced Micro-Fabrication Equipment (AMEC) announced the acquisition of a stake in CMP equipment firm Sizone. The transaction expands CMP (chemical mechanical planarization) tool capabilities, indirectly impacting semiconductor fabrication processes relevant to UK-linked advanced chip manufacturing supply chains.
Source: https://www.digitimes.com/
In April 2026, the UK Competition and Markets Authority (CMA) continued its merger inquiry into LB Group’s acquisition of Venator’s UK titanium dioxide assets. While not CMP-specific, the transaction affects UK specialty chemicals supply chains that feed semiconductor and materials processing ecosystems, including planarization-related inputs.
Source: https://www.gov.uk/
What Strategic Insights Define the Future of the United Kingdom Chemical Mechanical Planarization Market?
The United Kingdom Chemical Mechanical Planarization Market is, you know, structurally moving toward higher precision and AI-assisted process control, plus this deeper integration with advanced semiconductor packaging ecosystems over the next 5 to 7 years. The push behind it is basically the shift to smaller node architectures and the growing need for defect-free wafer surfaces in AI, automotive, and photonics use cases. There is also a less obvious risk sitting in the background, which is supply chain concentration for high-purity slurry materials, where reliance on a limited set of global chemical suppliers could end up bringing cost volatility and even production bottlenecks if disruptions happen.
At the same time an opportunity is quietly building, it looks like around compound semiconductor expansion in regional UK clusters, where silicon carbide and gallium nitride production is still in early scaling stages but getting serious industrial support fast. This area should start pulling in specialized CMP process tools designed for non-silicon materials, and that could create new differentiation layers for suppliers. Market participants should really focus on localization by pairing up with UK-based research institutions and early-stage fabs, so they can lock in long-term qualification advantages. If companies align early with these connected ecosystems, they’ll likely be better positioned to ride the next wave of advanced materials adoption and, importantly, avoid the awkward late-stage entry barriers.
United Kingdom Chemical Mechanical Planarization Market Report Segmentation
By Product Type
- CMP Slurries
- CMP Pads
- CMP Conditioning Discs
- CMP Cleaning Chemicals
- CMP Equipment
By Application
- Semiconductor Fabrication
- MEMS Manufacturing
- Data Storage Devices
- Optoelectronics
- Advanced Packaging
By Material
- Silica-based Slurries
- Ceria-based Slurries
- Polyurethane Pads
- Diamond Conditioning Discs
By End User
- Semiconductor Foundries
- IDMs
- Electronics Manufacturers
- Research Institutes
By Technology
- Copper CMP
- Tungsten CMP
- Dielectric CMP
- Silicon CMP
Frequently Asked Questions
Find quick answers to common questions.
The United Kingdom Chemical Mechanical Planarization Market size is USD 1084.7 Million in 2033.
Key segments for the United Kingdom Chemical Mechanical Planarization Market are By Product Type (CMP Slurries, CMP Pads, CMP Conditioning Discs, CMP Cleaning Chemicals, CMP Equipment, Others); By Application (Semiconductor Fabrication, MEMS Manufacturing, Data Storage Devices, Optoelectronics, Advanced Packaging, Others); By Material (Silica-based Slurries, Ceria-based Slurries, Polyurethane Pads, Diamond Conditioning Discs, Others); By End User (Semiconductor Foundries, IDMs, Electronics Manufacturers, Research Institutes, Others); By Technology (Copper CMP, Tungsten CMP, Dielectric CMP, Silicon CMP, Others).
Major United Kingdom Chemical Mechanical Planarization Market players are Applied Materials, Ebara Corporation, Entegris, Cabot Microelectronics, DuPont, Fujimi Corporation, Lapmaster Wolters, Logitech Ltd., KCTech, Revasum, Okamoto Machine Tool Works, SK enpulse, Versum Materials, Saint-Gobain, 3M.
The United Kingdom Chemical Mechanical Planarization Market size is USD 585.9 Million in 2025.
The United Kingdom Chemical Mechanical Planarization Market CAGR is 8.06% from 2026 to 2033.
- Applied Materials
- Ebara Corporation
- Entegris
- Cabot Microelectronics
- DuPont
- Fujimi Corporation
- Lapmaster Wolters
- Logitech Ltd.
- KCTech
- Revasum
- Okamoto Machine Tool Works
- SK enpulse
- Versum Materials
- Saint-Gobain
- 3M
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Fiber Optic Faceplates Market
Fiber Optic Faceplates Market Size, Share & Analysis Report By Type (< 300 mm2, 300-350 mm2, and > 350 mm2, By Application (Night Vision, Holographic Imaging, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
High Temperature Superconductors Market
High Temperature Superconductors Market Size, Share & Analysis Report By Type (1G HTS, and 2G HTS), By Application (Power Cable, Fault Current Limiter, and Transformer), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Industrial Plugs and Socket Market
Industrial Plugs and Socket Market Size, Share & Analysis Report By Type (Industrial Plugs, Industrial Sockets), By Current (Up to 32 A, 32 to 125 A, Above 125 A), By Protection (Dustproof and Splash Proof, Waterproof, Explosion Proof), By End User (Heavy Industries, Oil and Gas, Chemicals and Pharmaceuticals, Power Generation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
InGaAs Avalanche Photodiodes Market
InGaAs Avalanche Photodiodes Market Size, Share & Analysis Report By Type (1100 - 1700 nm, and 1000 - 1600 nm), By Application (Missile Warning System, Muzzle Flash Detection, Wafer Defect Inspection, Laser Rangefinders, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031