
United Kingdom Carbon Fiber Reinforced Plastic Market Size & Forecast:
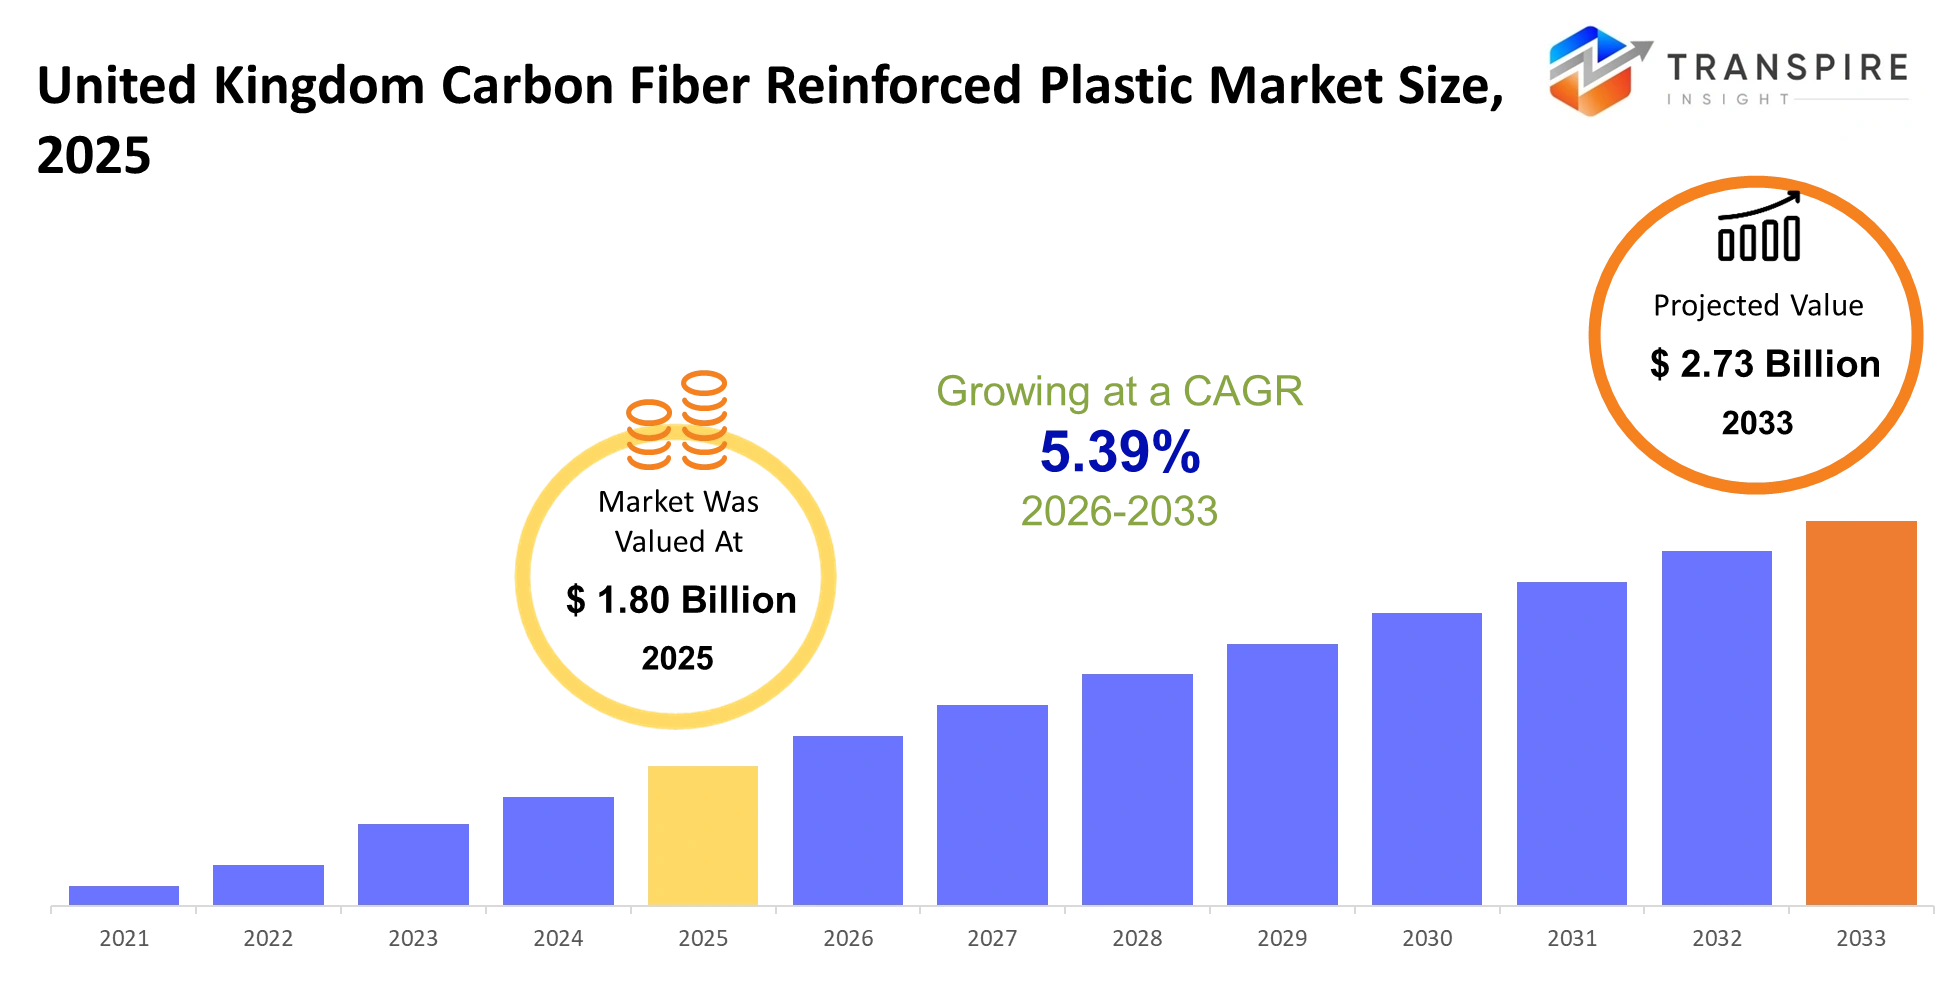
- United Kingdom Carbon Fiber Reinforced Plastic Market Size 2025: USD 1.80 Billion
- United Kingdom Carbon Fiber Reinforced Plastic Market Size 2033: USD 2.73 Billion
- United Kingdom Carbon Fiber Reinforced Plastic Market CAGR: 5.39%
- United Kingdom Carbon Fiber Reinforced Plastic Market Segments: By Resin Type (Epoxy-based CFRP, Polyester-based CFRP, Vinyl Ester CFRP, Thermoplastic CFRP, Polyurethane CFRP, Others); By Application (Aerospace Components, Automotive Components, Wind Energy Blades, Sports Equipment, Construction Materials, Marine Components, Others); By Manufacturing Process (Lay-up Process, Compression Molding, Injection Molding, Filament Winding, Pultrusion, Others); By End User (Aerospace Industry, Automotive Industry, Energy Sector, Construction Industry, Sporting Goods Industry, Others); By Product Form (Sheets & Panels, Tubes & Pipes, Fabrics, Rods, Others).
To learn more about this report,  Download Free Sample Report
United Kingdom Carbon Fiber Reinforced Plastic Market Summary
The United Kingdom Carbon Fiber Reinforced Plastic Market was valued at USD 1.80 Billion in 2025. It is forecast to reach USD 2.73 Billion by 2033. That is a CAGR of 5.39% over the period.
The United Kingdom Carbon Fiber Reinforced Plastic Market feels kinda crucial for cutting down on weight, while not really throwing away structural strength, across aerospace, automotive, wind energy, and those demanding high-performance industrial use cases. Manufacturers go with carbon fiber reinforced plastics because it helps with lower fuel burn, better corrosion resistance and also, frankly, longer service life for parts operating in places where metal options bring extra operating expense and more maintenance hassle.
Over the last five years, it seems the market moved, kind of slowly at first, from being mostly a niche aerospace thing toward wider industrial uptake. That’s especially true in electric vehicles, offshore wind blades , and hydrogen storage systems. The momentum picked up after the UK strengthened its net zero manufacturing approach, and added more capital to lightweight mobility technologies after Brexit related industrial reshaping, yes. During the COVID-19 stretch, supply chain problems also nudged makers to source advanced materials closer to home and automate composite production, instead of relying so much on long-distance deliveries.
Now, since OEMs keep focusing on energy efficiency plus lifecycle performance, carbon fiber reinforced plastic suppliers are landing more premium contracts linked to lightweight engineering, advanced mobility platforms, and renewable infrastructure growth, even if it all sounds a bit high stakes, because it is.
Key Market Insights
- In the United Kingdom, the Carbon Fiber Reinforced Plastic Market hit USD 1.80 billion in 2025, mainly backed by aerospace, EV, and offshore wind manufacturing needs, although the exact pressure behind it sometimes feels a bit “spread out.”
- For 2025, aerospace applications led overall, taking nearly 38% of the market share, driven by aircraft part replacement cycles and the usual lightweight structural demands that never really go away.
- Automotive composites were the quickest mover, growing more than 6% year on year ,as EV makers focused on cutting vehicle mass to support battery efficiency.
- England brought in over 68% of the UK market revenue, because aerospace activity and advanced production clusters are heavily concentrated there and that matters in practice.
- Meanwhile Scotland showed the most rapid expansion, boosted by investments tied to offshore wind blade fabrication ,and also by hydrogen infrastructure development running between 2024 and 2033.
- Thermoplastic CFRP usage climbed by roughly 20% since 2021. That shift happened mostly because manufacturers leaned into recyclability and faster production cycle times, even if some plants take time to fully adjust. In wind energy, applications captured around 18% industry share as turbine OEMs started preferring longer, lighter composite blades.
- Key players like Hexcel Corporation, Toray Industries, SGL Carbon, Mitsubishi Chemical Group, and Solvay strengthened their UK supply partnerships, plus they pushed automated composite processing capabilities that help keep output consistent.
- On the shop floor, makers have been adding robotic layup systems ,and AI-assisted quality inspection too, to reduce production waste and improve uniformity for high-volume work.
- Finally, strategic collaborations between aerospace OEMs and material suppliers sped up progress on recyclable composite materials, for the next wave of aircraft as well as mobility platforms that are trying to get lighter, faster, and cleaner.
What are the Key Drivers, Restraints, and Opportunities in the United Kingdom Carbon Fiber Reinforced Plastic Market?
The main thing pushing the United Kingdom Carbon Fiber Reinforced Plastic Market forward is basically the fast move toward lighter transport, and also more energy-smart industrial setups. In the UK, aerospace builders, electric vehicle makers, and offshore wind operators are being pushed to cut day to day emissions, while at the same time keeping or improving structural strength. Honestly this momentum got even stronger after the UK government tightened decarbonization goals and then rolled out funding schemes for advanced manufacturing, plus clean mobility know how. Because of that, OEMs are increasingly swapping aluminum and steel for carbon fiber composites in aircraft interiors, battery housings, pressure vessels , and even turbine blades. The direct commercial effect seems pretty clear: more material use per unit made, and longer term supply commitments with composite suppliers who can actually deliver at scale.
The biggest restraint is still the fact that production and processing can be expensive. To make carbon fiber you usually need energy heavy precursor processing, specialized curing systems, and people with very specific skills. These obstacles don’t get solved overnight, since they depend on big infrastructure spending and technology standardization. Smaller firms often sit on the sidelines too, mainly because tooling is costly and the return on investment looks uncertain, so broader adoption gets slowed especially in industries where price sensitivity is high.
One notable opening is starting to show up via recyclable thermoplastic composites, and also the growth of hydrogen mobility infrastructure. Investments in the UK around hydrogen storage tanks, lightweight rail systems, and newer aerospace platforms are building demand for CFRP materials that last longer, but can also be recycled.
What Has the Impact of Artificial Intelligence Been on the United Kingdom Carbon Fiber Reinforced Plastic Market?
Artificial intelligence along with advanced digital fabrication technologies are sort of reshaping the United Kingdom Carbon Fiber Reinforced Plastic Market, mostly by pushing better production precision, cutting down on material waste, and tuning lifecycle performance in a more controlled way. In practice, manufacturers are more and more deploying AI powered inspection systems, to catch tiny defects in composite layers during automated fiber placement and resin transfer molding. Instead of relying so much on hands on checks, these approaches reduce the time spent on manual inspection, and they also boost consistency in aerospace grade parts, where structural dependability really touches certification schedules.
On top of that, machine learning models are helping with predictive maintenance across composite production lines. Sensors that are embedded in curing ovens, robotic layup machinery, and autoclave setups keep watching temperature, pressure, and vibration patterns, so failures can be forecasted before production downtime really hits. Several UK aerospace and automotive suppliers say they’re seeing real reductions in scrap rates, and fewer unplanned maintenance disruptions after they rolled out digital monitoring platforms across their composite operations.
Then there’s advanced simulation software which improves performance targeting by forecasting stress response, fatigue strength, plus material deformation under conditions that feel closer to everyday use. With this, prototype timelines get shorter and the overall testing budget tends to drop, whether we’re talking about aircraft structures, EV battery casings, or even wind turbine components.
Still, AI take up has limitations, largely because integration costs are high and the production data is fragmented across older manufacturing systems. A lot of mid sized composite producers don’t yet have standardized datasets, so they can’t reliably train machine learning models, which ends up slowing wider deployment of intelligent manufacturing systems overall.
Key Market Trends
- After 2021, aerospace manufacturers started leaning more heavily on automated fiber placement systems, in order to squeeze down production waste a bit and also to move aircraft component manufacturing faster.
- This shift was noticeable not just in one or two sites but across the broader supply chain, kinda all at once.
- Electric vehicle manufacturers likewise raised CFRP usage for battery housings, and for structural panels too, aiming to stretch driving range while cutting platform mass . Some of them also talked about lower overall weight as a kind of knock on benefit, which makes sense.
- Thermoplastic composite adoption kept climbing , it went up by almost 20% since 2022, mainly because recyclability requirements became more prominent across automotive and aerospace procurement rules. In other words, the “green” clause started showing up harder in tenders and specs.
- Offshore wind developers pushed for lighter composite blades as UK renewable projects targeted bigger turbine capacities, especially those exceeding 15 MW, which tends to demand better materials up front. Those updates sort of forced the whole blade ecosystem to adapt.
- Meanwhile UK manufacturers reduced their reliance on imported intermediate materials after COVID-19 disruptions, because the weak points in global composite supply chains became harder to ignore. Once those channels broke down, everyone paid attention to continuity and sourcing.
- Gurit Holding AG together with Teijin Limited expanded their joint material development efforts, focusing on recyclable industrial composites. They seemed to be aiming at a smoother path from lab trials to industrial scale, though details were spread out.
- Automotive suppliers also ramped up robotic composite molding investments between 2023 and 2025, trying to improve cycle efficiency for mid-volume EV production. That emphasis on cycle timing, and repeatability, showed up a lot.
- Hydrogen storage infrastructure projects increased interest in high-pressure CFRP tanks, mostly because metal alternatives added extra system weight and also brought corrosion risk along with them. So, the composite option looked less heavy and a bit safer long term.
- Digital twin technologies gained real momentum among aerospace OEMs, used for near real time stress analysis and predictive lifecycle monitoring of composite components. It’s like they want a living model, not just a static inspection report.
- Finally, composite recycling initiatives expanded across the UK, as manufacturers responded to stricter environmental standards and newer end-of-life material recovery regulations. The pressure there felt constant, not seasonal or occasional.
United Kingdom Carbon Fiber Reinforced Plastic Market Segmentation
By Resin Type
Epoxy based CFRP still seems to hold the stronger market spot, since aerospace, automotive and wind energy makers kind of always push for higher mechanical strength, steady thermal behavior, and reliable adhesion results. It shows up a lot in aircraft structures and other high load industrial parts, which really helps it stay on top, also because certification rules are strict and these products need long operational lifetimes. Polyester based CFRP stays more secondary, more like a backup choice, where price sensitivity matters more than “top tier” structural capability, especially for construction panels and typical industrial use. Vinyl ester CFRP keeps slowly picking up momentum in corrosion heavy areas, like marine setups and chemical processing tools, because staying durable during moisture exposure is still a big deal. Thermoplastic CFRP looks like the fastest growing resin class, since manufacturers more and more want recyclable composites and quicker production cycles that fit automated manufacturing. Polyurethane CFRP and other specialty resin systems are mostly kept for niche uses, where flexibility, impact resistance, or a more customized performance profile is required.
Epoxy formulations are expected to keep leading, because aerospace and defense programs continue to favor lightweight structural materials with well known reliability expectations. Thermoplastic CFRP is set up for faster growth as electric vehicle output increases and recyclable composite rules change the way people buy materials across Europe. Polyester and vinyl ester materials should remain steady in industrial demand, mainly because cost effectiveness and corrosion resistance still beat out the need for ultra high structural performance.
By Application
Aerospace Components keep the leading application position because aircraft manufacturers kinda rely on lightweight composite structures, to boost fuel efficiency, cut down on maintenance costs ,and also to hit decarbonization targets. There is still heavy demand for fuselage sections, wing assemblies ,and interior structural parts which helps keep the push going for aerospace-grade composite materials. Automotive Components come in as the second-largest segment since electric vehicle makers increasingly swap metal structures with lighter options so they can raise battery efficiency, and expand driving range. Wind Energy Blades are still growing steadily because offshore renewable projects ask for larger and lighter turbine blades, that improve power generation efficiency. Sports Equipment and Construction Materials hold pretty stable demand, driven by premium consumer products and infrastructure reinforcement systems, while Marine Components are gaining momentum in corrosion-prone conditions where they have a real advantage. Other uses stay fairly concentrated in defense systems, industrial robotics, and hydrogen storage infrastructure.
For the outlook, Aerospace demand should keep looking solid, mostly from long-term aircraft replacement programs and more defense procurement activity. Automotive looks set to grow quickest as automated composite manufacturing lowers production costs, especially for mid-volume electric vehicle platforms. Wind installations are expected to keep supporting large-scale composite consumption as turbine capacities keep rising across offshore developments. Marine and construction applications are expected to see selective growth, in places where corrosion resistance and structural durability deliver measurable operational benefits.
To learn more about this report, Download Free Sample Report
By Manufacturing Process
The Lay-up Process keeps a dominant market position because aerospace and wind energy manufacturers keep leaning on manual or semi-automated layering methods for complex structural components, and yes it is still pretty common. There is also strong adoption even if production times are comparatively longer, since the customization ability is high and it stays compatible with large composite structures. Compression Molding sits in a major secondary place due to its increasing use in automotive and industrial applications, where faster cycle times matter and repeatable production quality is basically the point. Injection Molding is still expanding in thermoplastic composite uses because lightweight consumer and automotive parts now more often need scalable high-volume manufacturing solutions. Filament Winding remains strategically relevant for pressure vessels, pipes, and cylindrical structures that need high tensile strength, while Pultrusion backs structural profiles used in construction and infrastructure systems. The other manufacturing methods stay relatively limited to experimental composite fabrication and specialized industrial production.
Lay-up systems are expected to stay relevant in aerospace programs, since structural complexity and certification standards make rapid process switching difficult. Compression and injection molding technologies are likely to show stronger growth as automotive electrification speeds up the demand for scalable lightweight component production. Filament winding is set up for steady growth too, driven by rising investment in hydrogen storage tanks and industrial pressure systems. Pultrusion demand should hold steady in infrastructure and construction uses where durable composite beams and profiles are required.
By End User
The Aerospace Industry keeps the dominant end-user position, because aircraft manufacturers use big volumes of high-performance composite materials, for structural as well as interior applications. Strict fuel-efficiency targets, and also long-term fleet modernization programs keep backing solid procurement activity across both commercial aviation and defense, so it kind of never really slows down.
The Automotive Industry looks like the fastest-growing end-user segment, since electric vehicle producers push for lighter materials to offset battery mass and stretch the driving range. The Energy Sector stays in a strong market spot, mainly through offshore wind blade manufacturing, hydrogen storage systems, and renewable infrastructure projects. The Construction Industry demand stays fairly stable in reinforcement panels and corrosion-resistant structures, while the Sporting Goods Industry keeps expanding, especially in premium bicycles, rackets and protective equipment. Most other end users are more concentrated in industrial machinery, robotics, and defense equipment manufacturing, as you might expect.
Aerospace manufacturers are projected to preserve long-term material leadership, since aircraft replacement cycles keep running, and defense spending growth stays supportive. Automotive demand will likely ramp up more, as thermoplastic composites become more commercially realistic for mass production. Energy-sector applications are set up for continued growth because offshore renewable installations and hydrogen mobility investments need lightweight structural solutions. Construction and sporting goods segments should keep benefiting from durability plus performance edges in niche uses.
By Product Form
Sheets & Panels keep the top market spot, mostly because aerospace, automotive, and construction makers still need flat composite structures, for things like body panels , interior systems, and reinforcement tasks. There’s also strong fit with automated cutting and molding tech which really supports the demand, especially in big scale industrial production spaces.
Tubes & Pipes hold a fairly large secondary role, and that’s largely tied to industrial transport upgrades, marine needs, and hydrogen infrastructure , where lightweight plus corrosion resistant structures are the whole point. Fabrics are still climbing, since woven carbon fiber materials give flexibility for bespoke composite manufacturing and for those high strength structural layers that everyone wants to stack cleanly. Rods stay relevant too, in infrastructure reinforcement, sporting equipment, and industrial engineering, where high tensile strength with low weight boosts performance efficiency.The other product forms, they stay more concentrated and niche, like specialized industrial work and defense programs.
Looking ahead, Sheets and panels are expected to stay in the lead because automated composite assembly is leaning more and more on standardized structural formats. Fabric based composites should post faster growth, as aerospace and automotive producers look for reinforcement materials that can work with advanced molding systems. Tubes and pipes will keep getting a lift from hydrogen transport buildouts , and from corrosion resistant industrial piping demand. Rod usage seems set for steady expansion in construction reinforcement and lightweight engineering systems.Across the forecast period, product innovation should increasingly emphasize modular composite formats, recyclable materials , and compatibility with automated manufacturing platforms, you know, the usual high throughput requirements.
What are the Key Use Cases Driving the United Kingdom Carbon Fiber Reinforced Plastic Market?
The biggest real use case for carbon fiber reinforced plastic in the United Kingdom comes from aerospace manufacturing. Aircraft producers lean on CFRP materials for fuselage sections, wing parts, interior structures, and engine assemblies, because lightweight composites bump up fuel efficiency while still holding structural integrity when things get really extreme during operations.
Automotive and renewable energy applications are also growing fast. Electric vehicle makers increasingly put CFRP in battery enclosures, chassis setups, and body panels, to offset the battery weight and stretch driving range. Offshore wind developers meanwhile depend on advanced composites for longer turbine blades that can handle harsh marine surroundings, while also boosting energy capture efficiency.
Newer uses show up too—think hydrogen storage tanks, lighter rail transport structures, and advanced defense systems. On top of that, manufacturers are looking at recyclable thermoplastic composites for urban air mobility platforms and next generation industrial robotics. In those cases, durability, weight reduction, and thermal stability, start to matter as core performance requirements, more and more.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 1.80 Billion |
|
Market size value in 2026 |
USD 1.89 Billion |
|
Revenue forecast in 2033 |
USD 2.73 Billion |
|
Growth rate |
CAGR of 5.39% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United Kingdom |
|
Key company profiled |
Toray Industries, Hexcel Corporation, SGL Carbon, Mitsubishi Chemical Group, Solvay, Teijin Limited, Owens Corning, Hyosung Advanced Materials, Formosa Plastics, Gurit, Nippon Graphite Fiber, DowAksa, Tencate Advanced Composites, Huntsman Corporation, BASF Hyundai Heavy Industries Co. Ltd., Kohler Co., Scania AB. |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Resin Type (Epoxy-based CFRP, Polyester-based CFRP, Vinyl Ester CFRP, Thermoplastic CFRP, Polyurethane CFRP, Others); By Application (Aerospace Components, Automotive Components, Wind Energy Blades, Sports Equipment, Construction Materials, Marine Components, Others); By Manufacturing Process (Lay-up Process, Compression Molding, Injection Molding, Filament Winding, Pultrusion, Others); By End User (Aerospace Industry, Automotive Industry, Energy Sector, Construction Industry, Sporting Goods Industry, Others); By Product Form (Sheets & Panels, Tubes & Pipes, Fabrics, Rods, Others). |
Which Regions are Driving the United Kingdom Carbon Fiber Reinforced Plastic Market Growth?
England is still the main region in the United Kingdom Carbon Fiber Reinforced Plastic Market, mostly because it has, the country’s biggest aerospace , automotive, and advanced making clusters. It also gets a big lift from government-backed innovation programs, solid R&D connections, and that practical access to aerospace supplier chains tied to Bristol, Derby and the Midlands. Big composite production sites, testing facilities, plus university research partnerships keep pushing commercialization of those lightweight materials into multiple industrial uses. Because of this whole setup, companies can ramp output faster, lock in long-running OEM deals, and also stay ahead with aerospace-grade composite solutions.
Scotland is growing in a bit of a different way, it leans on renewable power and offshore engineering know-how instead of being so concentrated in aerospace. The area built a fairly steady composite demand base through offshore wind turbine manufacturing, marine engineering activities, and hydrogen infrastructure investments. With regular public funding for clean energy programs, and close cooperation between local manufacturers and energy developers, revenue stability stays intact over time. So, rather than England’s higher-volume aerospace push, Scotland’s strength is more about durable infrastructure spending and long-cycle renewable energy rollouts.
Wales looks like it’s becoming the fastest-growing region, mainly due to fresh investments in advanced manufacturing sites and automotive electrification work. New composite processing technologies, plus regional skills initiatives and government-supported industrial decarbonization measures are speeding up adoption across transport and energy uses since 2024.
Who are the Key Players in the United Kingdom Carbon Fiber Reinforced Plastic Market and How Do They Compete?
The United Kingdom Carbon Fiber Reinforced Plastic Market is still kind of moderately consolidated, where competition mostly circles around material performance, the ability to scale production, and these advanced composite engineering skills. Big, established manufacturers keep trying to hold their market share via aerospace certifications, proprietary resin systems, and automated manufacturing tools, not really by racing on price only. Meanwhile, smaller specialized composite firms are starting to gain more traction, by pushing recyclable thermoplastic materials, and by looking harder at customized industrial applications. Overall, the competitive situation seems to increasingly reward firms that can blend lightness and performance with lower processing expenses, plus faster production cycles, without losing consistency.
Toray Industries stands out thanks to thermoplastic composite innovation, and also a strong aerospace integration angle across Europe. They’ve been expanding recyclable composite development, and improving UK distribution capacity through strategic agreements with local composite suppliers or partners, depending on how you see it. Hexcel Corporation, on the other hand, leans heavily into high-performance aerospace and pressure vessel work, and it uses proprietary HexTow carbon fiber technologies to lock in contracts that often connect to hydrogen storage, and defense-related systems. Their edge typically comes from prepreg systems that are tuned for automated manufacturing, while still delivering high-strength structural performance.
SGL Carbon competes with industrial-grade carbon fiber solutions that are geared for automotive lightweighting and renewable energy projects. Solvay places emphasis on specialty resin systems, plus aerospace-certified composite materials that can handle high-temperature, and chemically demanding settings.
Company List
- Toray Industries
- Hexcel Corporation
- SGL Carbon
- Mitsubishi Chemical Group
- Solvay
- Teijin Limited
- Owens Corning
- Hyosung Advanced Materials
- Formosa Plastics
- Gurit
- Nippon Graphite Fiber
- DowAksa
- TenCate Advanced Composites
- Huntsman Corporation
- BASF
Recent Development News
“In April 2026, Toray Advanced Composites entered a distribution partnership with VAC Innovation Ltd in the United Kingdom. The agreement expanded UK access to AmberTool® HX56 composite tooling prepreg and strengthened localized supply capabilities for aerospace and industrial composite manufacturers.
Source: https://compositesuk.co.uk
“In February 2026, Toray Industries announced new recyclable and bio-based composite material showcases at JEC World 2026. The initiative highlighted the company’s strategic focus on circular composite technologies for aerospace, automotive, and industrial applications, reinforcing its sustainability-driven market positioning.
Source: https://www.toraytac.com
“In September 2025, Hexcel Corporation unveiled an advanced composite pressure vessel developed with HyPerComp Engineering Inc. The new Type IV carbon overwrap pressure vessel strengthened Hexcel’s position in lightweight hydrogen and aerospace storage applications using high-performance HexTow® carbon fiber technology.
Source: https://www.hexcel.com
What Strategic Insights Define the Future of the United Kingdom Carbon Fiber Reinforced Plastic Market?
The United Kingdom Carbon Fiber Reinforced Plastic Market is kinda heading, structurally, toward automated, recyclable, and energy efficient composite production over the next decade. That shift is being pushed by that mix of aerospace decarbonization targets, the ongoing expansion of electric mobility, and big investments in offshore renewable infrastructure at scale. Still, there’s this one sort of hidden snag: the market really leans on concentrated global carbon fiber supply chains especially for precursor materials and aerospace grade fibers. If there’s any disruption tied to trade restrictions, geopolitical tensions, or raw material shortages, production costs could climb a lot and industrial take up might get delayed, or at least slow down more than people expect.
There’s also a pretty notable opening that’s starting to form around thermoplastic composite recycling and hydrogen mobility infrastructure. Firms that can scale recyclable composite methods for pressure vessels, lighter transport systems, and modular industrial parts might land new mid volume opportunities across UK industries. So companies in the UK market should put emphasis on partnerships that focus on automated manufacturing, localized material sourcing and digital quality control systems. The goal would be to boost resilience, cut down processing expenses, and lock in longer term agreements in those fast growing composite use cases.
United Kingdom Carbon Fiber Reinforced Plastic Market Report Segmentation
By Resin Type
- Epoxy-based CFRP
- Polyester-based CFRP
- Vinyl Ester CFRP
- Thermoplastic CFRP
- Polyurethane CFRP
- Others
By Application
- Aerospace Components
- Automotive Components
- Wind Energy Blades
- Sports Equipment
- Construction Materials
- Marine Components
- Others
By Manufacturing Process
- Lay-up Process
- Compression Molding
- Injection Molding
- Filament Winding
- Pultrusion
- Others
By End User
- Aerospace Industry
- Automotive Industry
- Energy Sector
- Construction Industry
- Sporting Goods Industry
- Others
By Product Form
- Sheets & Panels
- Tubes & Pipes
- Fabrics
- Rods
- Others
Frequently Asked Questions
Find quick answers to common questions.
The expected United Kingdom Carbon Fiber Reinforced Plastic Market size for the market will be USD 2.73 Billion in 2033.
Key segments for the United Kingdom Carbon Fiber Reinforced Plastic Market are By Resin Type (Epoxy-based CFRP, Polyester-based CFRP, Vinyl Ester CFRP, Thermoplastic CFRP, Polyurethane CFRP, Others); By Application (Aerospace Components, Automotive Components, Wind Energy Blades, Sports Equipment, Construction Materials, Marine Components, Others); By Manufacturing Process (Lay-up Process, Compression Molding, Injection Molding, Filament Winding, Pultrusion, Others); By End User (Aerospace Industry, Automotive Industry, Energy Sector, Construction Industry, Sporting Goods Industry, Others); By Product Form (Sheets & Panels, Tubes & Pipes, Fabrics, Rods, Others).
Major United Kingdom Carbon Fiber Reinforced Plastic Market players are Toray Industries, Hexcel Corporation, SGL Carbon, Mitsubishi Chemical Group, Solvay, Teijin Limited, Owens Corning, Hyosung Advanced Materials, Formosa Plastics, Gurit, Nippon Graphite Fiber, DowAksa, Tencate Advanced Composites, Huntsman Corporation, BASF.
The United Kingdom Carbon Fiber Reinforced Plastic Market size is USD 1.80 Billion in 2025.
The United Kingdom Carbon Fiber Reinforced Plastic Market CAGR is 5.39% from 2026 to 2033.
- Toray Industries
- Hexcel Corporation
- SGL Carbon
- Mitsubishi Chemical Group
- Solvay
- Teijin Limited
- Owens Corning
- Hyosung Advanced Materials
- Formosa Plastics
- Gurit
- Nippon Graphite Fiber
- DowAksa
- TenCate Advanced Composites
- Huntsman Corporation
- BASF
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
May 2026
Healthcare Polymer Packaging Market
Healthcare Polymer Packaging Market Size, Share & Analysis Report By Packaging Type (Syringes, IV Bottles and Pouches, Clamshells, Blisters, Bottles & Jars, Containers, Tubes, IV Parental Packaging, Others), By Type (Regulated, Non-regulated), By Polymer Type (LDPE (Low-Density Polyethylene), HDPE (High-Density Polyethylene), Homo-polymer (Homo), Random Copolymer (Random), Block Copolymer (Block), PET, Polystyrene, Polyvinyl Chloride, Polyamide/EVOH, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Hydrophilic Tape (Waterstop) Market
Hydrophilic Tape (Waterstop) Market Size, Share & Analysis Report By Type (Bentonite-Based Hydrophilic Tape, Rubber-Based Hydrophilic Tape), By Application (Residential Buildings, Commercial Buildings, Infrastructure Projects), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Metalens Market
Metalens Market Size, Share & Analysis Report By Type (Visible Light Metalens, and Infrared Metalens), By Application (Consumer Electronics, Automotive Electronics, Industrial, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
PBT Resin Market
PBT Resin Market Size, Share & Analysis Report By Type (Reinforced PBT Resin, Unreinforced PBT Resin), By Processing Method (Injection Molding, Extrusion, Blow Molding, Others), By End-User (Automotive, Electrical & Electronics, Consumer Appliances, Industrial Machinery, Medical Devices, Packaging, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031