
Non-Invasive Surgical Wound Closure Market Summary:
According to Transpire Insight, a detailed research report on the market reflects that the adhesives product segment dominates the Non-Invasive Surgical Wound Closure Market, accounting for approximately 28% of the total share worldwide. Ethicon leads the market with approximately (around USD 1.5 billion) in annual revenue and an estimated 22-24% market share, making it the leading contributor to market development, innovation, advanced non-invasive surgical wound closure product development, expanding manufacturing capabilities, and growth dynamics.
Market Snapshot
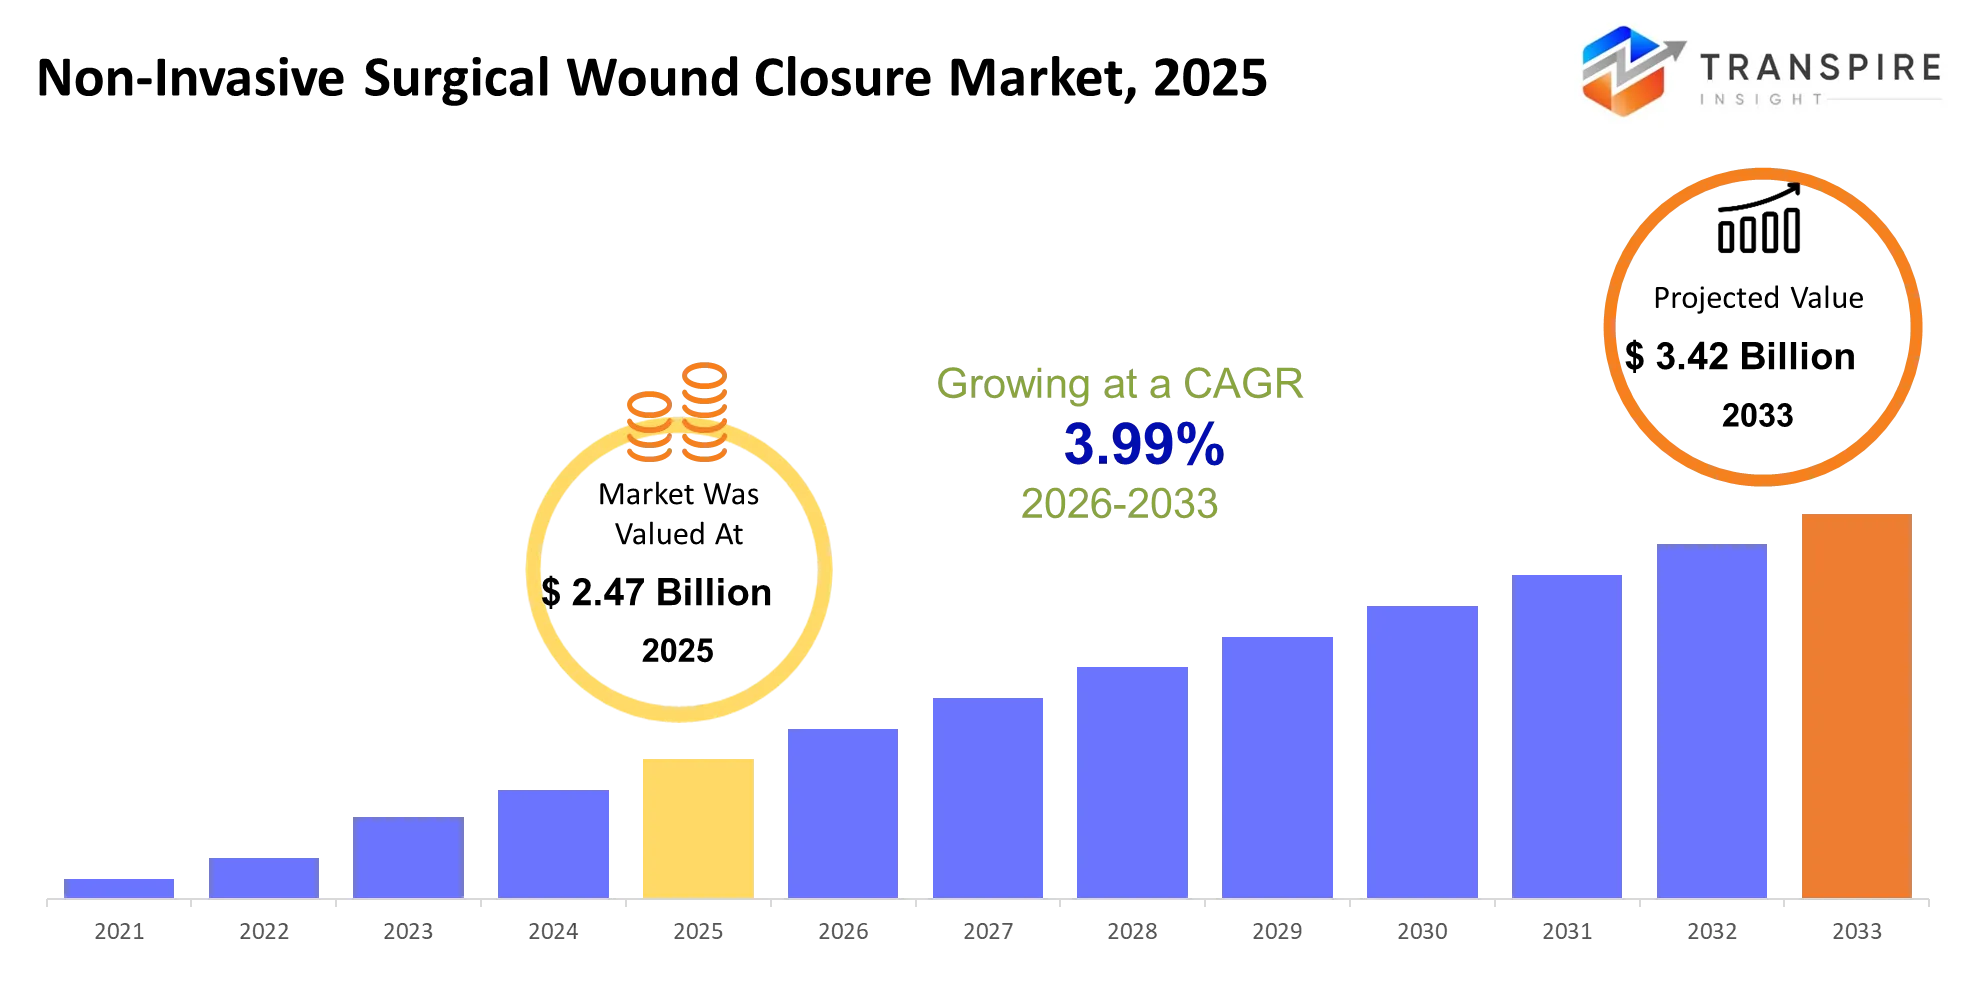
- Market Value (2025): USD 2.47 Billion.
- Expected Market Value (2026): USD 2.60 Billion.
- Estimated Market Value (2033): USD 3.42 Billion.
- Forecast CAGR (2026-2033): 3.99%.
- Leading Region in 2025: North America
- Second-largest Region: Europe
- Fastest Growing Region: Asia Pacific
Introduction
The Non-Invasive Surgical Wound Closure Market consists of cutting-edge medical methods and products that enable approximation and approximation of skin edges without using traditional penetrating sutures or staples. Some important technologies used include tissue adhesives, adhesive strips for wound closure, and zip-based skin closure technology, which help in achieving fast closure of appropriate surgical incisions and traumatic wounds. Tissue adhesives consist of medical-grade cyanoacrylate that helps in bonding the approximated skin edges by polymerizing on coming into contact with water. Some of the other important factors aiding the growth of this market include rising preference for minimally invasive surgery, as well as the increasing trend of out-patient surgeries. Important applications include general surgery, minimally invasive surgeries, plastic and reconstructive surgeries, and emergency wound treatment.
For instance:-
- North America holds a dominant market share owing to high levels of surgeries, advanced healthcare infrastructure, growth in ambulatory surgery centers, and increased use of adhesive and needleless surgical wound closures.
- The Asia-Pacific region is witnessing rapid market growth owing to rising number of surgeries, improved access to healthcare facilities, growing healthcare infrastructure, and increasing usage of minimally invasive surgical wound closures.
Key Market Highlights: -
- North America is expected to grow at a rapid CAGR in the Non-Invasive Surgical Wound Closure Market by holding around 45% of the share during the forecast period.
- Europe is anticipated to hold roughly 23.90% share of the Non-Invasive Surgical Wound Closure Market over the predicted timeframe.
- Asia Pacific is anticipated to hold nearly 23% share of the Non-Invasive Surgical Wound Closure Market over the predicted timeframe.
- By Product, the Tissue Sealants & Hemostats dominated the market and holds nearly 45% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- By Application, the General Surgery dominated the market and holds close to 32% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- By Wound Type, the Multinational Corporations dominated the market and holds about 57% share in 2025 and is projected to grow at a substantial CAGR during the forecast period.
- Government healthcare policies, regulations related to medical devices, infection control programs, and domestic manufacturing strategies are making the environment conducive for innovative non-invasive surgical wound closure technologies.
How is Technology Driving Growth in the Non-Invasive Surgical Wound Closure Market?
Technological factors are playing an important role in the expansion of the Non-Invasive Surgical Wound Closure Market by the use of novel tissue adhesives, bio-compatible materials, and mechanical wound closure devices. The use of cyanoacrylate based adhesives helps in achieving fast skin edge approximation along with easy applicability. Some of these adhesives come with antimicrobial properties that help in forming barriers against microbial contamination. Novel polymers along with hydrogel based materials are helping in improving the adhesion capability along with the biocompatibility. Non-invasive mechanical devices such as zipper-like devices and adhesive devices do not require traditional skin perforations for wound closure.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 2.47 Billion |
|
Market size value in 2026 |
USD 2.60 Billion |
|
Revenue forecast in 2033 |
USD 3.42 Billion |
|
Growth rate |
CAGR of 3.99% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
United States; Canada; Mexico; United Kingdom; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; United Arab Emirates |
|
Key company profiled |
Johnson & Johnson/Ethicon, 3M, Baxter, Medtronic, Smith+Nephew, B. Braun, Integra LifeSciences, Advanced Medical Solutions, CryoLife, Peters Surgical, Derma Sciences, ZipLine Medical, Ethicon, Chemence Medical, Artivion |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product (Adhesives, Tissue Sealants & Hemostats, Zip Products, Surgical Tapes, Skin Closure Strips, Mesh Closure Devices, Liquid Bandages, Others); By Application (General Surgery, Orthopedic Surgery, Cardiovascular Surgery, Plastic Surgery, Gynecological Surgery, Urological Surgery, Ophthalmic Surgery, Others); By Wound Type (Surgical Incisions, Traumatic Wounds, Chronic Wounds, Lacerations, Burns, Post-operative Wounds, Cosmetic Wounds, Others); By End User (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, Emergency Centers, Physician Offices, Home Healthcare, Research Institutions, Others); By Material (Cyanoacrylate, Silicone, Polyurethane, Hydrogel, Polyester, Nylon, Collagen, Others); By Distribution (Hospital Pharmacies, Retail Pharmacies, Direct Sales, Distributors, Online, Specialty Stores, Clinics, Others); By Procedure (Minimally Invasive Surgery, Open Surgery, Robotic Surgery, Laparoscopic Surgery, Cosmetic Procedures, Trauma Procedures, Outpatient Procedures, Others) |
Market Drivers
The SSD Market is being driven by the rapid developments of AI and adoption of hyperscale data centers, growing need for large storage capacity solutions within enterprises, as well as trends in transition to PCIe 5.0 and NVMe architectures. QLC SSDs are becoming more common with cloud providers adopting them to reduce the costs and achieve higher densities of storage capacity required for AI, vector databases, and inference workloads. The investments in semiconductor industry and the adoption of measures such as the European Chips Act have been improving regional manufacturing capabilities, but do not directly influence SSDs production yet.
For instance:-
- The Europe market is driven by well-established healthcare systems, preference for patient-friendly closure techniques, advanced surgical infrastructure, and growing use of tissue adhesives and specific wound closures.
- The Latin America market offers growth opportunities with the development of healthcare infrastructure, growth in surgical capabilities, and adoption of surgical wound closure technologies in hospitals.
Restrain
Restricting factors for the Non-Invasive Surgical Wound Closure Market include the increased costs of the latest surgical wound closure adhesives, devices, and materials when compared with the traditional sutures and staples. The absence of proper reimbursement along with the fluctuating procurement policies in health care institutions is one other restricting factor. Some technical challenges hinder the use of such products in high tension wounds and in complicated wound closures. Skin irritation and contact dermatitis resulting from some adhesives or tapes can act as barriers too.
|
Driver |
Relative Impact on Growth (%) |
Geographic Relevance |
Impact Timeline |
Demand Strength |
Growth Mechanism |
Key Beneficiaries |
Major Constraint |
|
Rising Minimally Invasive and Ambulatory Surgical Procedures |
25% |
North America, Europe, Asia Pacific |
Short-term |
High |
Enables faster, simplified closure following minimally invasive procedures. |
Closure-device manufacturers; ambulatory centers; surgeons; patients |
Limited suitability for complex or deep wounds |
|
Growing Demand for Tissue Adhesives and Advanced Closure Technologies |
23% |
North America, Europe, Asia Pacific |
Short-term |
High |
Improves approximation while reducing closure time and procedural complexity. |
Tissue-adhesive manufacturers; hospitals; surgeons; technology suppliers |
Adhesion performance varies across wound conditions |
|
Increasing Focus on Surgical-Site Infection Prevention |
20% |
Asia Pacific, North America, Europe |
Medium-term |
High |
Supports adoption of closure methods supporting controlled wound approximation. |
Hospitals; infection-control teams; device manufacturers; patients |
Infection risk depends on multiple clinical factors |
|
Technological Advancements in Biocompatible and Smart Closure Materials |
17% |
North America, Europe, Asia Pacific |
Medium-term |
Medium |
Enables stronger, flexible, biodegradable, and patient-friendly closure solutions. |
Medtech companies; material developers; hospitals; patients |
Development costs and clinical validation requirements |
|
Expansion of Healthcare Infrastructure and Surgical Access |
15% |
Asia Pacific, Latin America, Middle East & Africa |
Long-term |
High |
Expanding surgical capacity increases demand for efficient closure products. |
Manufacturers; hospitals; distributors; surgical providers |
Uneven healthcare funding and infrastructure availability |
Analysis of Prices and Consumer Behaviour
Non-Invasive Surgical Wound Closure market consists mostly of high quality closure products (68% of the entire market share; due to the fact that there is a high demand for such products from hospitals, ambulatory surgical centers and minimally invasive surgeries). It is anticipated that the cost of a high performing, standardized closure product would be 35% higher than the cost of other products as the closure product will be manufactured using advanced technology, certified and will give consistent closure results. Around 45% of all unit sales of non-invasive surgical wound closures products is accounted for the sales of adhesive-based closure products. This is mainly due to the fact that such products are easy to use in surgical operations and are very convenient in application. Minimally invasive surgery and ambulatory surgery industries comprise around 70% of the demand from these industries. The buying pattern of healthcare providers shows that 55% of buyers value closure performance, safety and consistency of results while purchasing. Around 33% of buyers buy products under bulk agreements or contracts as they are keen on reducing their cost of procurement of products.
|
Company |
Est. Revenue Share Range |
Key Offerings |
Strategic Positioning |
Geographic Strength |
Technology Focus |
|
Johnson & Johnson MedTech (Ethicon) |
22-24% |
DERMABOND ADVANCED, DERMABOND PRINEO, DERMABOND Mini |
Market leadership through diversified closure portfolio |
North America, Europe, Asia Pacific |
Cyanoacrylate adhesives and mesh-based closure systems |
|
3M Company |
15-17% |
Steri-Strip Skin Closures, Reinforced Skin Closures, Steri-Strip Wound Closure System |
High-volume adhesive closure and wound-care positioning |
North America, Europe, Asia Pacific |
Reinforced adhesive strips and antimicrobial closure materials |
|
Medtronic plc |
8-10% |
LiquiBand Exceed, LiquiBand Exceed XS, LiquiBand XL, SwiftSet |
Broad topical adhesive portfolio for surgical applications |
North America, Europe, Asia Pacific |
Octyl-cyanoacrylate topical adhesive formulations |
|
Stryker Corporation |
8-10% |
Zip Skin Closure, Zip Plus |
Puncture-free closure technology differentiation |
North America, Europe, Asia Pacific |
Dynamic compression and adhesive strap closure |
|
Smith+Nephew plc |
7-9% |
Skin closure solutions, surgical wound-management products, adhesive closure technologies |
Surgical wound-management specialization and innovation |
Europe, North America, Asia Pacific |
Advanced wound closure and tissue-management technologies |
|
Advanced Medical Solutions Group plc |
6-8% |
LiquiBand, LiquiBand XL, LiquiBand Exceed, LiquiBand Rapid |
Specialist wound-closure manufacturer with distribution |
Europe, North America, Asia Pacific |
Cyanoacrylate adhesives and topical closure technologies |
|
B. Braun Melsungen AG |
4-6% |
Histoacryl, surgical closure products, tissue adhesives |
Integrated surgical portfolio with adhesive specialization |
Europe, Asia Pacific, Latin America |
Tissue adhesives and surgical wound-management systems |
|
Baxter International Inc. |
3-5% |
Tissue sealants, surgical hemostasis and closure solutions |
Diversified surgical-care portfolio supporting closure procedures |
North America, Europe, Asia Pacific |
Tissue sealants and advanced surgical materials |
|
Teleflex Incorporated |
2-4% |
Surgical closure products, wound-management solutions, medical-device components |
Specialized surgical-device and procedural portfolio |
North America, Europe, Asia Pacific |
Procedure-focused closure and medical-device technologies |
|
Healthium Medtech |
2-4% |
Surgical sutures, skin closure products, wound-care solutions |
Value-focused surgical portfolio with emerging-market reach |
Asia Pacific, Middle East & Africa, Europe |
Cost-efficient closure materials and surgical consumables |
Who are the Key Players in the Non-Invasive Surgical Wound Closure Market and how do they compete?
The competitiveness in the market of the Non-Invasive Surgical Wound Closure Market lies in companies that focus on developing new technologies, surgical-specific solutions, and distribution network worldwide. Competing on the basis of technological wound closure, bio-compatible materials, innovative wound closure solutions, and surgical workflow integration, this way of competing will result in continuous innovation of products, as well as increased procedure efficiency, patient convenience, consistent wound closure and positive procedural outcome for healthcare organizations.
With the help of advanced tissue adhesives, innovative skin closure system, and specialized wound closure technologies, Johnson & Johnson/Ethicon creates competitive advantage for itself in this market. Developing innovative wound closure products for surgery, skin approximation, and other clinical procedures, 3M distinguishes itself among its competitors. Baxter creates competitive advantage through offering integrated solutions in the field of surgical wound management, tissue adhesives, wound closure technologies, and advanced healthcare products.
Top Companies in the Non-Invasive Surgical Wound Closure Market
- Johnson & Johnson/Ethicon
- 3M
- Baxter
- Medtronic
- Smith+Nephew
- B. Braun
- Integra LifeSciences
- Advanced Medical Solutions
- CryoLife
- Peters Surgical
- Derma Sciences
- ZipLine Medical
- Ethicon
- Chemence Medical
- Artivion
|
Investment Factor |
Why It Matters to Investors |
Opportunity |
Investment Implication |
|
Growth of Minimally Invasive and Ambulatory Surgery |
Expanding minimally invasive procedures increase demand for rapid, incision-focused closure solutions. |
Develop closure products optimized for laparoscopic and ambulatory procedures. |
Short-to-medium term: scalable procedural demand supports portfolio expansion. |
|
Advanced Tissue Adhesives and Combination Closure Systems |
Adhesive chemistry and integrated mesh systems enable differentiated clinical and procedural performance. |
Invest in advanced adhesives, mesh-assisted closure, and application-specific systems. |
Medium-to-long term: differentiated products can strengthen pricing power. |
|
Surgical-Site Infection and Wound-Management Priorities |
Hospitals increasingly emphasize controlled wound closure and postoperative complication reduction. |
Develop antimicrobial, barrier-forming, and wound-protection closure technologies. |
Medium term: clinical-performance differentiation can influence procurement decisions. |
|
Emerging-Market Surgical Infrastructure |
Expanding surgical capacity creates additional demand beyond established North American and European markets. |
Target Asia Pacific, Latin America, and Middle Eastern healthcare systems. |
Medium-to-long term: regional expansion broadens addressable customer base. |
|
Premium Biocompatible and Next-Generation Materials |
Adhesive strength, flexibility, setting characteristics, and biocompatibility differentiate competing products. |
Develop low-irritation, flexible, biodegradable, and application-specific formulations. |
Long term: material innovation can create defensible technology positions. |
|
Regulatory and Clinical-Validation Barriers |
Device classification requires evidence addressing safety, effectiveness, performance, sterility, and biocompatibility. |
Acquire validated technologies or partner with experienced regulatory manufacturers. |
All horizons: regulatory expertise reduces commercialization and compliance risk. |
Non-Invasive Surgical Wound Closure Market Segmentation
The Non-Invasive Surgical Wound Closure Market share is divided into seven categories: By Product, By Application, By Wound Type, By End User, By Material, By Distribution, By Procedure.
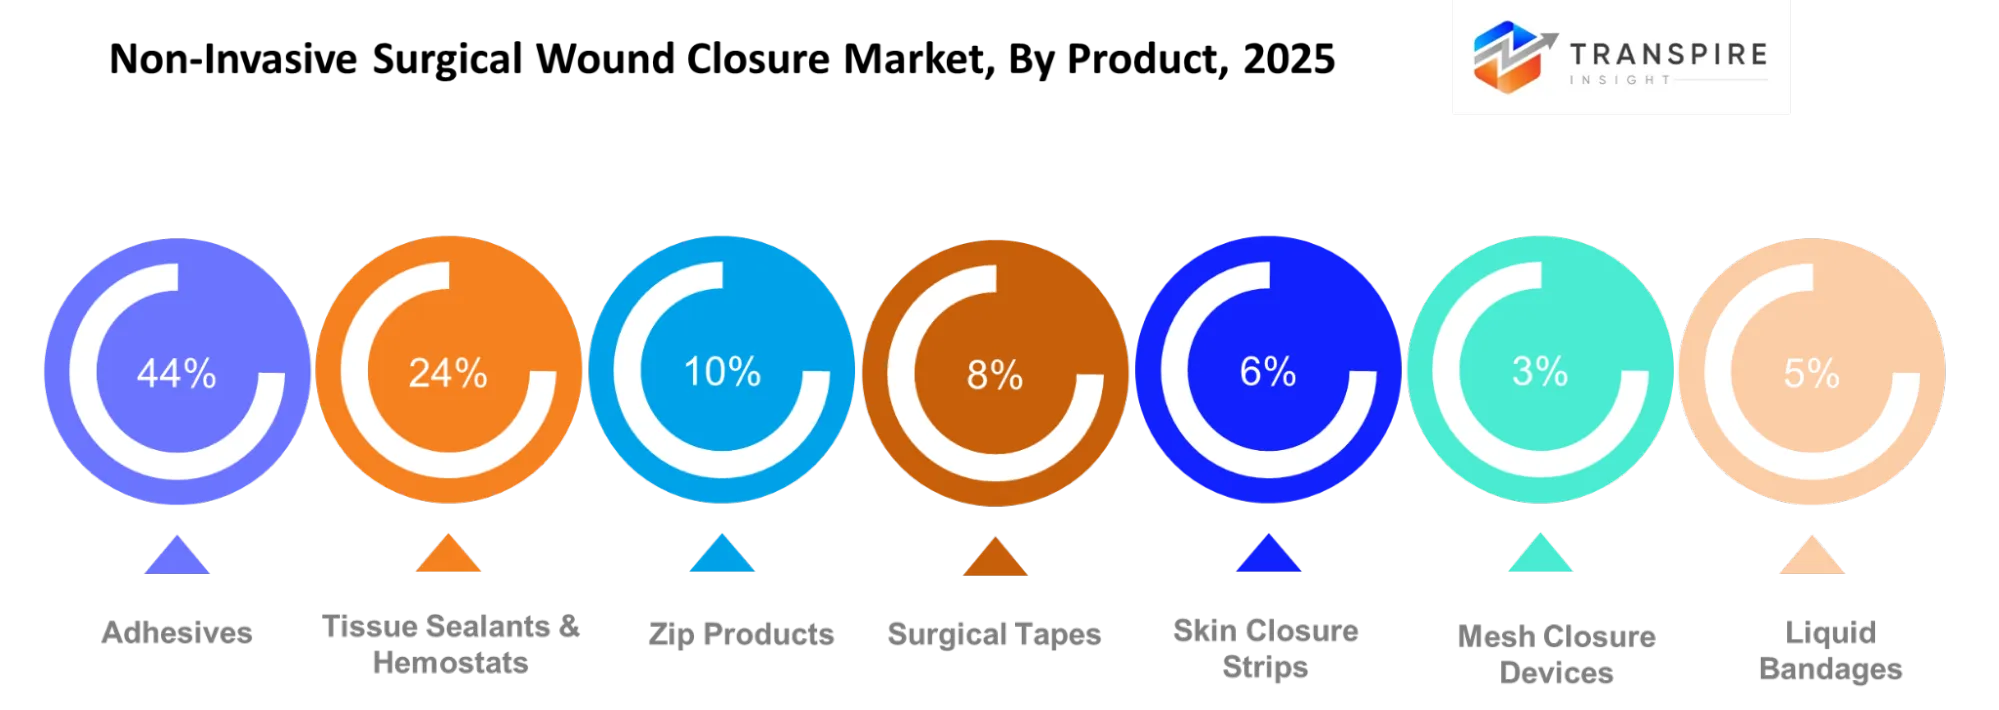
The Tissue Sealants & Hemostats dominated the market, accounting for nearly 45% in 2025 and is expected to rise at a significant CAGR during the forecast period.
The Non-Invasive Surgical Wound Closure Market is by product into adhesives, tissue sealants & hemostats, zip products, surgical tapes, skin closure strips, mesh closure devices, liquid bandages, others. Among these, the Tissue Sealants & Hemostats dominated the market, accounting for nearly 45% in 2025 and expected to increase at a significant CAGR during the forecast period. Tissue Sealants & Hemostats was the leading market segment and had a share of about 45% in 2025, due to increasing demands for efficient and minimally invasive wound closure.
The General Surgery dominated the market, accounting for close to 32% in 2025, and is expected to rise at a significant CAGR during the forecast period
The Non-Invasive Surgical Wound Closure Market is segmented by application into general surgery, orthopedic surgery, cardiovascular surgery, plastic surgery, gynecological surgery, urological surgery, ophthalmic surgery, others. Among these, the General Surgery dominated the market, accounting for close to 32% in 2025 and expected to increase at a significant CAGR during the forecast period. General Surgery was the leading market segment and was fueled by high number of procedures, increased use of minimally invasive procedures, and demand for efficient wound closure solutions.
The Chronic Wounds dominated the market, accounting for about 57% in 2025 and is expected to rise at a significant CAGR during the forecast period.
The Non-Invasive Surgical Wound Closure Market by wound type into surgical incisions, traumatic wounds, chronic wounds, lacerations, burns, post-operative wounds, cosmetic wounds, others. Among these, theMultinational Corporations dominated the market, accounting for about 57% in 2025 and expected to increase at a significant CAGR during the forecast period. Chronic Wounds was the leading market segment and was dominated by increased prevalence of wounds, rising incidences of diabetes, and increasing demands for wound closure solutions.
Regional Segment Analysis of the Non-Invasive Surgical Wound Closure Market
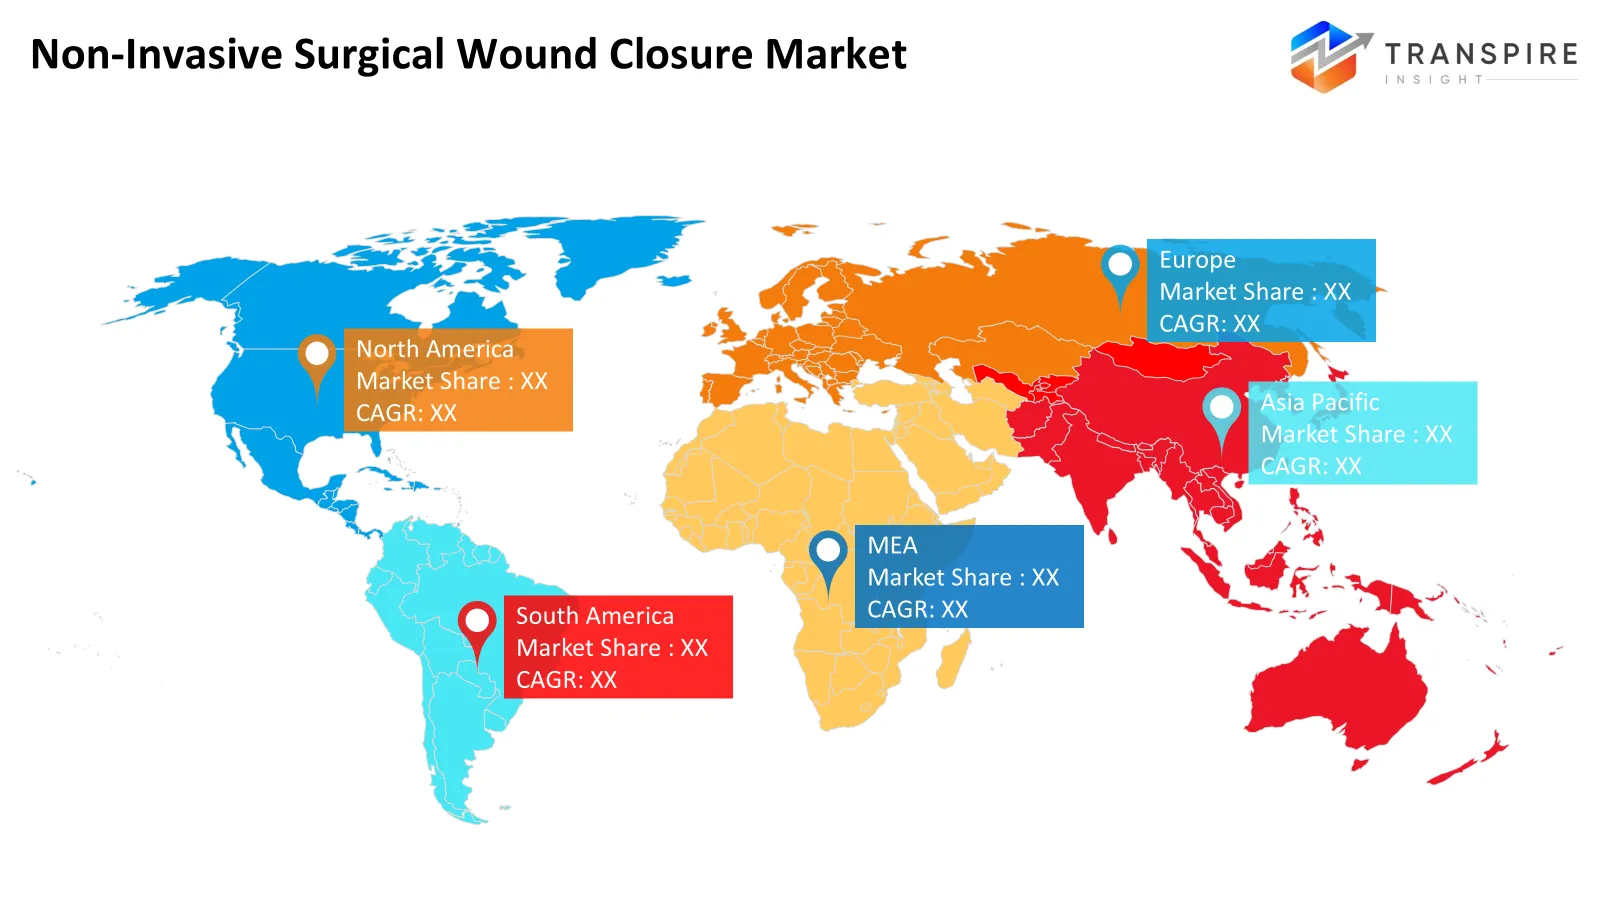
- Europe (Germany, France, U.K., Italy, Spain, Rest of Europe)
- North America (U.S., Canada, Mexico)
- Asia-Pacific (China, Japan, India, Rest of APAC)
- South America (Brazil and the Rest of South America)
- The Middle East and Africa (UAE, South Africa, Rest of MEA)
North America is expected to grow at a rapid CAGR in the Non-Invasive Surgical Wound Closure Market, holding around 45% of the share during the forecast period.
North America is likely to hold leadership in the Non-Invasive Surgical Wound Closure Market owing to advanced healthcare infrastructure, high volume of surgeries, and increased preference for minimally invasive techniques. High demand for tissue adhesives, adhesive strips, and advanced mechanical closure products is fueling regional market growth. Moreover, favorable reimbursement policies, established medical device manufacturers, rising number of ambulatory surgeries, and continuous innovations in wound closure technologies are providing a boost to market expansion in the region.
Europe is the high-growth region in the Non-Invasive Surgical Wound Closure Market during the period, holding roughly 23.90% share.
Europe is a high growth region in the Non-Invasive Surgical Wound Closure Market, driven by advanced healthcare infrastructure, increasing number of minimally invasive procedures, and rising demand for patient friendly closure techniques. Rising adoption of tissue adhesives, adhesive strips, and advanced mechanical closure products is driving regional market expansion. Furthermore, strict medical device regulations, rising numbers of ambulatory surgeries, established healthcare system, and continuous innovation in surgical technology are providing growth opportunities for the market in Europe.
Asia Pacific is the fastest-growing region in the Non-Invasive Surgical Wound Closure Market during the period, holding nearly 23% share.
The Asia-Pacific region is witnessing the fastest growth rate in the Non-Invasive Surgical Wound Closure market due to growing infrastructure in healthcare, increased surgeries, and use of minimally invasive surgery. Rising expenditure on healthcare, enhanced access to modern medical technology, and increasing demand for effective wound closure solutions are favoring regional expansion. In addition to this, increased hospital spending, rise in ambulatory surgical procedures, advances in tissue adhesives, and improved availability of medical devices are presenting many opportunities in this market in Asia-Pacific.
Strategies for Market Growth in Non-Leading Regions:
The development of non-leading areas through cost-effective non-invasive surgical wound closure manufacturing technology will help the small and medium-sized companies of medical devices. Production of the local tissue adhesives, closure strips, and mechanical closure devices, as well as setting up regional wound-closure manufacturing centers, can decrease the dependency on imports and procurement costs. Strategic partnership with regional hospitals, ASCs, health care providers, distributors, and medical device manufactures will enhance market penetration of non-invasive surgical wound closure products. Training programs for gaining knowledge about wound closure technologies, product application, quality control, and regulatory requirements will be necessary. Moreover, flexible financing, long-term supply agreement, and contract manufacturing will make non-invasive surgical wound closure products easily available and motivate their adoption by health care providers. Collaboration programs of governments, health care, and medical device organizations, as well as electronic commerce, will increase product availability and facilitate sustainable market development in developing countries.
Future Market Trends for the Non-Invasive Surgical Wound Closure Market: -
- Increasing Shift towards Outpatient & Minimally Invasive Surgery: Increased usage of ambulatory care surgery and minimally invasive techniques is creating a need for effective tissue adhesives, closures, and wound closure solutions without the use of needles.
- Innovations in Biocompatible Wound Closure Materials: Innovations in cyanoacrylate tissue adhesives, polymers, hydrogels, and antimicrobial products is helping to improve adhesion efficiency, flexibility, and applicability.
- Increasing Presence in Developing Nations: Higher volumes of surgeries, increasing investment in healthcare facilities, and higher availability of medical devices in emerging markets such as Asia Pacific is creating new opportunities.
Recent Development
- In June 2026: Advanced Medical Solutions launched LIQUIFIX Precision after FDA 510(k) clearance for cyanoacrylate tissue fixative.
- In September 2026: Freudenberg Performance Materials and Foshan United Medical Technologies launched advanced non-invasive wound closure products and chitosan-based haemostasis technology during the WUWHS.
- In April 2026: Developments in industry included advanced artificial adhesives and 2-octyl cyanoacrylate topical applications for wound closure.
Market Segment
This study forecasts revenue at global, regional and country levels from 2020 to 2033. Transpire Insight has segmented the Non-Invasive Surgical Wound Closure Market based on the below-mentioned segments:
Non-Invasive Surgical Wound Closure Market, By Product
- Adhesives
- Tissue Sealants & Hemostats
- Zip Products
- Surgical Tapes
- Skin Closure Strips
- Mesh Closure Devices
- Liquid Bandages
- Others
Non-Invasive Surgical Wound Closure Market, By Application
- General Surgery
- Orthopedic Surgery
- Cardiovascular Surgery
- Plastic Surgery
- Gynecological Surgery
- Urological Surgery
- Ophthalmic Surgery
- Others
Non-Invasive Surgical Wound Closure Market, By Wound Type
- Surgical Incisions
- Traumatic Wounds
- Chronic Wounds
- Lacerations
- Burns
- Post-operative Wounds
- Cosmetic Wounds
- Others
Non-Invasive Surgical Wound Closure Market, By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Emergency Centers
- Physician Offices
- Home Healthcare
- Research Institutions
- Others
Non-Invasive Surgical Wound Closure Market, By Material
- Cyanoacrylate
- Silicone
- Polyurethane
- Hydrogel
- Polyester
- Nylon
- Collagen
- Others
Non-Invasive Surgical Wound Closure Market, By Distribution
- Hospital Pharmacies
- Retail Pharmacies
- Direct Sales
- Distributors
- Online
- Specialty Stores
- Clinics
- Others
Non-Invasive Surgical Wound Closure Market, By Procedure
- Minimally Invasive Surgery
- Open Surgery
- Robotic Surgery
- Laparoscopic Surgery
- Cosmetic Procedures
- Trauma Procedures
- Outpatient Procedures
- Others
Non-Invasive Surgical Wound Closure Market, By Regional Analysis
North America
- US
- Canada
- Mexico
Europe
- Germany
- UK
- France
- Italy
- Spain
- Russia
- Rest of Europe
Asia Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia Pacific
South America
- Brazil
- Argentina
- Rest of South America
Middle East & Africa
- UAE
- Saudi Arabia
- Qatar
- South Africa
- Rest of the Middle East & Africa
Frequently Asked Questions
Find quick answers to common questions.
Rising minimally invasive surgeries, advanced tissue adhesives, outpatient procedures, and growing demand for efficient, patient-friendly wound closure technologies are driving market growth.
Tissue sealants and hemostats dominate, supported by increasing demand for efficient, reliable, and minimally invasive wound closure solutions across surgical procedures.
North America dominates due to advanced healthcare infrastructure, high surgical volumes, established manufacturers, ambulatory surgery expansion, and widespread technology adoption.
Key trends include outpatient surgery expansion, biocompatible materials, advanced tissue adhesives, antimicrobial formulations, mechanical closure devices, and emerging-market adoption.
High product costs, limited reimbursement, technical limitations for complex wounds, established conventional techniques, and adhesive-related skin reactions may constrain adoption.
- Johnson & Johnson/Ethicon
- 3M
- Baxter
- Medtronic
- Smith+Nephew
- B. Braun
- Integra LifeSciences
- Advanced Medical Solutions
- CryoLife
- Peters Surgical
- Derma Sciences
- ZipLine Medical
- Ethicon
- Chemence Medical
- Artivion
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
AI in Diabetic Retinopathy Market
AI in Diabetic Retinopathy Market Size, Share & Analysis Report By Type (Screening AI Systems, Diagnostic AI Systems, and Predictive AI Models), By Application Segment (Hospitals, Ophthalmology Clinics, Diagnostic Centers, and Research and Development), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Psychometric Tests Market
Psychometric Tests Market Size, Share & Analysis Report By Type (Personality Tests, Ability/Aptitude Tests, Skill/Knowledge Tests, and Others), By Application (Talent Acquisition and Talent Management), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Apr 2026
Rare Biological Sample Collection Market
Rare Biological Sample Collection Market Size, Share & Analysis Report By Type (Isolation Kits & Reagent, Blood Collection Tubes, and Others), By Application (Oncology, Transcriptomics, Pharmacogenomics, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
-
Jul 2026
Diabetic Retinopathy Market
Diabetic Retinopathy Market Size, Share & Analysis Report By Type (Proliferative Diabetic Retinopathy, and Diabetic Macular Edema (DME)), By Treatment Type (Anti VEGF Drug, Steroid Implants, Laser Surgeries, and Vitrectomy), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 – 2031
Our Clients







