
Germany Industrial Control & Factory Automation Market Summary
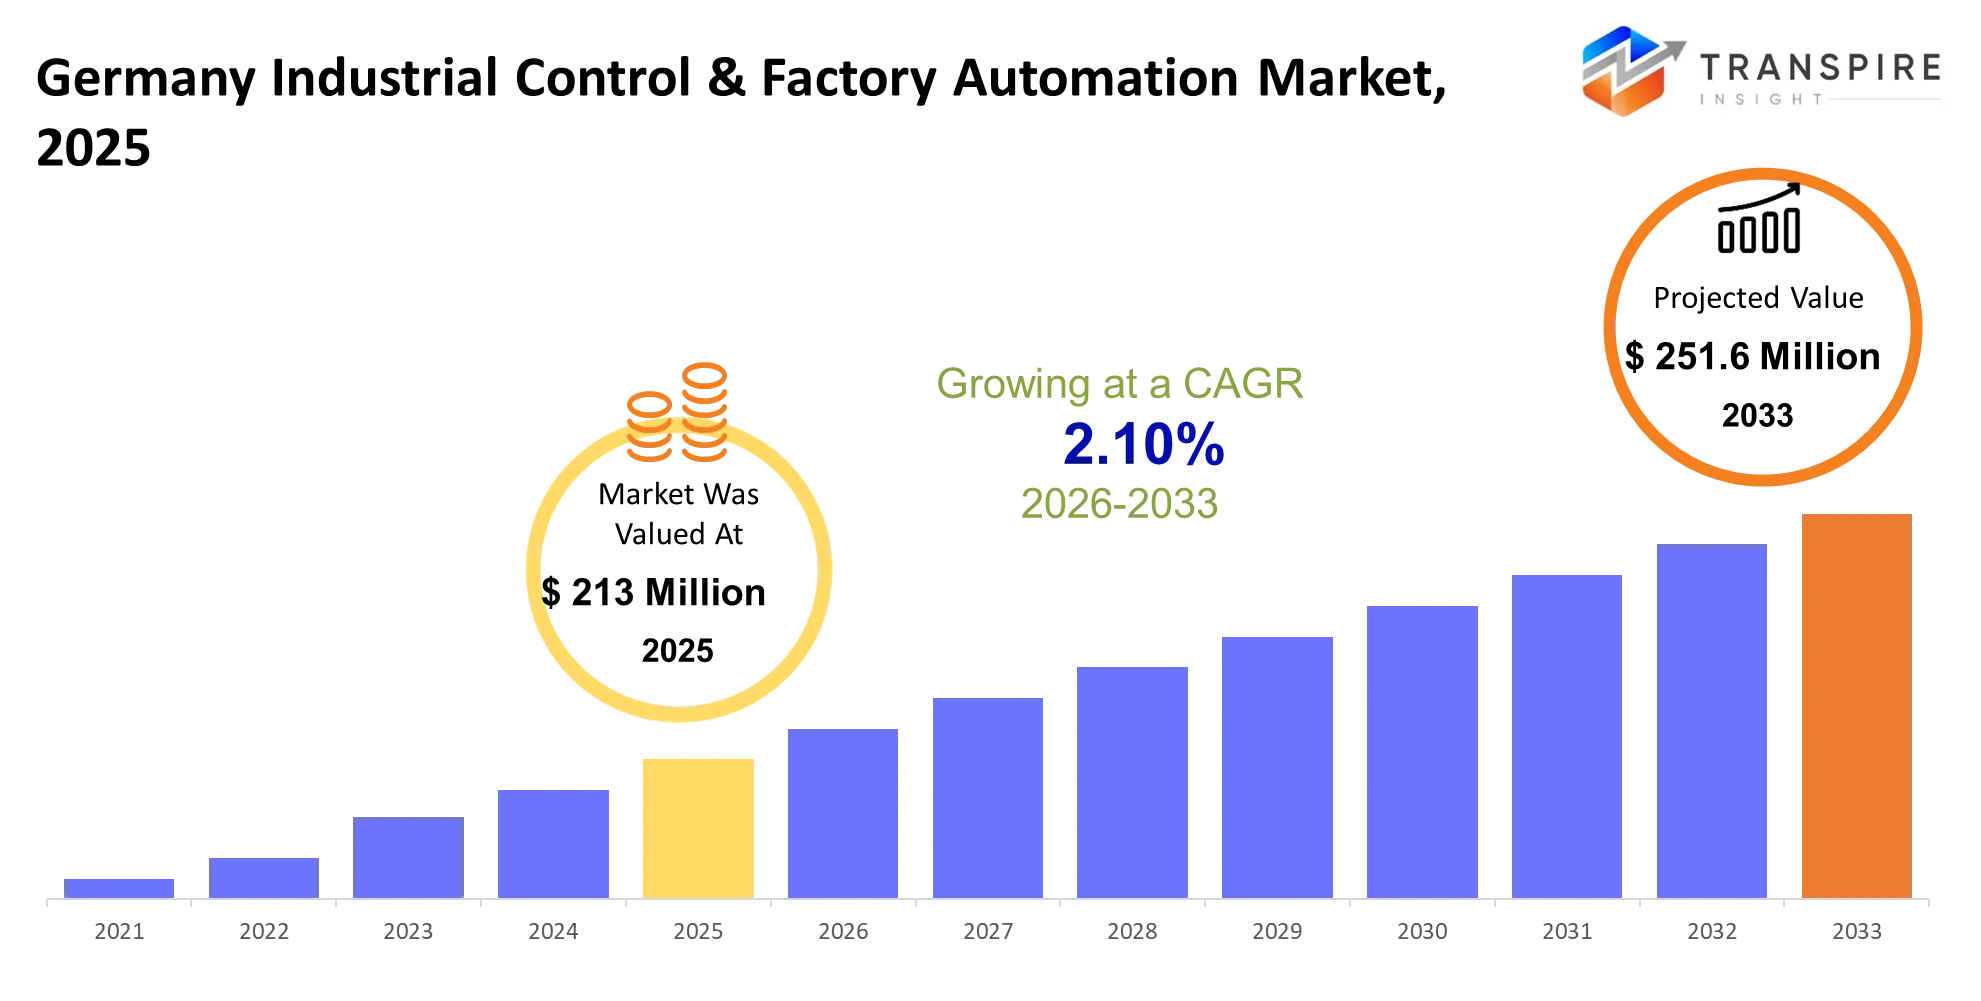
As per Transpire Insight Analysis The Germany Industrial Control & Factory Automation Market size is estimated at USD 213 Million in 2025 and is anticipated to reach USD 251.6 Million by 2033, growing at a CAGR of 2.10% from 2026 to 2033.
The Germany Industrial Control & Factory Automation Market helps makers run production lines with higher precision, speed, and reliable throughput, using automated control systems, robotics, sensors, and connected industrial software. In the same way, these options let plants dial down stoppages, raise product quality, tune energy consumption and handle more intricate manufacturing routines across automotive, machinery, electronics and also process industries.
In the last few years, German producers have moved away from classic automation toward software led plants, powered by Industrial IoT, digital replicas, artificial intelligence, and edge computing. Supply chain shocks, a shortage of skilled staff, and rising energy expenses pushed budgets toward automated production systems faster than before, because firms were after more resilience and smoother operations. This shift into smart manufacturing and flexible production methods keeps supporting take up, with many companies modernizing the existing sites, instead of only betting on brand new factory builds.
Germany Industrial Control & Factory Automation Market Size & Forecast:
- Germany Industrial Control & Factory Automation Market Size 2025: USD 213 Million
- Expected Market Value 2033: 251.6 Million
- Forecast CAGR: 2.10%
- Leading region in 2025: North Rhine-Westphalia
- Fastest Growing region: Siemens AG
- Key Profile: Siemens AG, ABB Ltd., Schneider Electric, Rockwell Automation, Emerson Electric, Mitsubishi Electric, Honeywell International, Omron Corporation, Yokogawa Electric, Bosch Rexroth, Beckhoff Automation, FANUC Corporation, Phoenix Contact, B&R Automation, WAGO GmbH
Key Market Insights
- Germany Industrial Control & Factory Automation Market adoption is sort of shifting toward AI based engineering, with Siemens rolling out industrial AI solutions in 2026 and yeah, it changes the vibe.
- Bavaria is really leading on automation investments through automotive and machinery clusters , taking a big chunk of Germany’s industrial manufacturing activity.
- North Rhine-Westphalia has the fastest growth momentum, because chemical, energy, and manufacturing companies push harder on digital transformation projects after 2025, so the schedule is speeding up.
- Industrial IoT adoption also expanded as manufacturers connected older, legacy equipment with sensors, edge platforms and cloud based monitoring systems, it feels like everything is getting stitched together.
- Automotive manufacturers increased automation spending after 2023 to support electric vehicle production, battery assembly and flexible manufacturing lines, it’s more like a steady climb.
- Siemens, ABB , and Schneider Electric improved their competitive positions by using integrated automation platforms , they blend hardware software and analytics in one go.
- Digital twin implementation increased among German manufacturers as they leaned into virtual production models , aiming to reduce commissioning time and smooth out start ups .
- Predictive maintenance solutions gained traction after 2024, since factories prioritized uptime improvement and equipment lifecycle optimization.
- Cybersecurity investment rose after new European digital regulations introduced stricter requirements for industrial network protection , so companies are taking security more seriously.
- Robotics adoption grew across electronics, automotive and logistics facilities, as companies respond to workforce shortages and production complexity, basically more hands are replaced with smarter systems.
What are the Key Drivers, Restraints, and Opportunities in The Germany Industrial Control & Factory Automation Market?
The main growth driver in the Germany Industrial Control & Factory Automation Market is that shift toward smart manufacturing and more Industry 4.0 type production models. German manufacturers are putting money into connected control systems, robotics, and industrial software, kind of to lift output per employee while also handling labor shortages and those rising operating costs. Automotive plus machinery players are upgrading their plants, with automated inspection, robotic assembly, and real-time production monitoring, and this helps when it comes to electric vehicle manufacturing as well as tailored production demands.
One big restraint is the high cost, also the overall complexity tied to modernizing existing industrial facilities. A lot of German factories still run older equipment that needs to be tied into newer automation platforms, and that brings problems around compatibility, cybersecurity, and the sheer timeline for implementation. For small and medium-sized manufacturers it’s easy to postpone investment, because automation upgrades demand serious capital, and specialized engineering skills that are not always readily available.
A notable opportunity sits in AI-powered industrial automation and digital twin technologies. Firms like Siemens and Beckhoff are working on more capable platforms that let manufacturers simulate production flows, fine tune operations, and shrink engineering lead times. At the same time, increased regional investments in Bavaria, and North Rhine-Westphalia offer extra openings for automation providers offering retrofit services, cloud-connected systems, and AI-enabled production management tools, which is basically where the demand is going.
What Has the Impact of Artificial Intelligence Been on The Germany Industrial Control & Factory Automation Market?
Artificial intelligence is slowly transforming industrial automation across Germany by helping machines make more “good” decisions, keep an eye on production, and basically raise day to day operational efficiency. Companies are starting to mix AI with PLC systems, sensors and industrial software not only to catch equipment abnormalities , but also to tune production parameters and make automated quality inspections a lot easier. Siemens , and its AI driven engineering solutions , show that the trend is moving toward platforms that kind of assist engineers, with programming configuration and troubleshooting chores, instead of making everything fully manual.
Machine learning models are now used more often for predictive maintenance, since they can read vibration signals , temperature readings, and recurring machine behavior patterns. With those approaches, manufacturers are able to spot potential failures before a breakdown happens, which boosts equipment availability and trims maintenance costs , at least in many real deployments. AI analytics are also used for energy optimization by adjusting production routines based on demand patterns and current operational conditions.
Meanwhile advanced digital technologies like digital twins and edge AI allow factories to try production changes “virtually” first, before anything physical is actually done. This supports faster commissioning, better production flexibility , and a more careful use of resources in automotive, electronics, and machinery. Still, AI adoption is held back , because integration costs are high , industrial data quality is often not strong enough, and it can be difficult to connect modern AI platforms with older factory infrastructure, especially when the legacy systems were not designed for anything like this.
Key Market Trends
- In 2026 Siemens expanded its industrial AI in a way that kind of matched what manufacturers were doing, like moving toward automated engineering, and self-optimizing production systems, without fully thinking about how fast it all has to happen.
- In Germany, factories took up digital twin use more, starting after 2024, mainly to cut the machine commissioning time, and also to make production planning way more accurate.
- After 2023, the whole automotive automation shift leaned more toward electric vehicle plus battery manufacturing uses, and it spread across many major production sites.
- Meanwhile, industrial cybersecurity investments rose after 2025 , because manufacturers tightened up how they protect connected production networks.
- At the same time edge computing adoption picked up speed , since factories needed quicker data processing and didn’t want to rely on centralized cloud systems all the time, you know.
- Beckhoff pushed PC based automation solutions pretty actively as well, with manufacturers asking for open architectures and flexible control platforms.
- Robotics demand actually expanded between 2024 and 2026, mostly because of workforce shortages across manufacturing and logistics operations, not just one area.
- Predictive maintenance systems also got more traction as companies aimed to reduce unplanned downtime, and to extend the equipment life cycles. For SMEs the story was similar but with modular solutions, they boosted automation investments, lowering the barriers to Industry 4.0 adoption.
- And then cloud based industrial platforms gained momentum, especially for multi-site manufacturers, they standardized monitoring plus analytics across production locations and that helped everything line up.
Germany Industrial Control & Factory Automation Market Segmentation
By Component:
Programmable Logic Controllers , or PLCs, are like a core piece in German factories, since they run automated production sequences, handle machine operations and those real-time control tasks day to day. Distributed Control Systems, DCS for short, tend to fit the big process industries such as chemicals, energy, and utilities, because they keep continuous operations in check. SCADA Systems then show up for centralized monitoring, data collecting, and overall operational visibility across an entire industrial site, kind of the “overview” layer. Human Machine Interface or HMI solutions help people work with automated equipment better, using real-time dashboards and control panels, even when things are moving fast.
Industrial robots, sensors, drives, and motion controllers support more advanced manufacturing uses across automotive, electronics, and machinery sectors. Machine vision systems are also getting more traction for automated inspection, defect recognition and quality assurance workflows. There are also other bits in the mix, like industrial communication modules, control accessories, and automation hardware, all of which make connected factory environments easier to manage and more responsive.
By Technology:
Industrial IoT adoption is expanding, as German manufacturers connect machines sensors, and production systems to improve monitoring, operational control, sort of. Artificial Intelligence and Machine Learning technologies help with automated decision making, quality checks, production optimization, and predictive analytics. Edge Computing brings faster data processing close to production equipment, which cuts down the response time for those critical manufacturing operations. Cloud Automation lets companies handle industrial applications, analytics platforms and even multi location production systems in a more efficient way.
Digital Twin technology is going to matter more, because manufacturers can simulate production environments before any physical implementation, you know. Robotics technology keeps supporting automated assembly, material handling and precision manufacturing tasks. Predictive Maintenance solutions aim to reduce equipment failures, using data driven analysis and such. 5G Connectivity together with Cybersecurity Solutions will back the next generation of smart factories, by boosting communication speed network reliability and protecting industrial infrastructure.
By Industry:
Automotive is still one of the major industry slices for industrial control, and factory automation in Germany, basically because of electric vehicle production, battery manufacturing, and the more demanding assembly processes. In a lot of general manufacturing environments, automation systems get used to push productivity up, cut down day to day operational expenses, and keep product quality stable and really repeatable. Food & Beverage businesses then roll out automated processing, packing, and monitoring setups, trying to make operations smoother , and still comply with tight production rules. For pharmaceuticals the use of automation tends to focus on precision production, compliance tracking, and controlled environments where everything stays on spec.
On the other side, Chemicals, Oil & Gas, and Energy & Utilities depend heavily on automation technologies for process regulation, safety stewardship, and overall operational dependability. Electronics manufacturers often combine robotics with machine vision and automated test procedures, so the output can stay high precision. Metals & Mining companies use automation to watch equipment, and then optimize the process steps. Meanwhile, the other industries lean on tailored automation systems, based on their own operating realities and particular requirements , which is more or less how most of them do it.
By End User:
Large enterprises still take up a major share of automation adoption, since big manufacturers spend a lot on smart factories, robotics,and advanced control platforms. Meanwhile smaller and medium sized firms are moving toward modular automation products that need less money and help a slower kind of digital transformation, kind of step by step. OEMs make heavy use of industrial automation know how to build new machinery with integrated controls, sensors, and also software based features. System Integrators, they often back businesses by designing carrying out and then keeping up customized automation setups.
In process industries automation is used for continuous production oversight, safety regulation, and overall operational efficiency. In discrete manufacturing, like automotive and electronics, the whole approach leans on robotics, PLC systems and machine vision to achieve high volume throughput. Government organizations and utilities adopt automation too, mostly for infrastructure administration and live operational monitoring. Contract manufacturers meanwhile are putting money into flexible automation systems so they can react to changing production needs and to customer specific manufacturing requirements, without losing time.
By Deployment:
On premise deployment is still pretty important for many German manufacturers, especially those who want direct control over their industrial systems, data protection and the actual production work. Cloud based solutions are getting more attention these days, since companies are looking for scalable analytics, remote monitoring and sort of centralized oversight across several facilities, all at once, you know. Hybrid deployment models mix local industrial control with cloud capabilities ,so manufacturers can juggle performance, security and flexibility without losing the plot. Smart Factories are also a growing deployment style, where automation, robotics, sensors and digital platforms kind of all work in the same rhythm, together.
Then there is Edge Deployment, which helps real time industrial use cases by handling data closer to the machines and the production lines. Private Cloud gives a secure environment for firms dealing with sensitive operational information, while Public Cloud platforms are more about scaling industrial applications when demand increases. Industrial Networks keep communications steady between machines, controllers and enterprise systems. Multi site Deployment should grow further, because global manufacturers are starting to standardize their automation platforms across different plants. Other options also exist, like more tailored industrial architectures based on company specific requirements.
What are the Key Use Cases Driving The Germany Industrial Control & Factory Automation Market?
Discrete manufacturing still feels like the big, dominant thing, especially through automotive, machinery, electronics, and the production of industrial equipment, overall. In these places PLCs , motion control , robotics , SCADA, and machine vision are everywhere, mostly to automate assembly, machining, material handling, and yeah the quality inspection part. The demand is staying strong too, because manufacturers are chasing higher throughput, steadier quality , and less dependence on scarce skilled labor.
Now, there is also a clear expansion into stuff like automated battery manufacturing and energy efficient production systems. Automotive and battery players are ramping up automation for cell assembly, powertrain production, testing, and traceability, and in process industries, connected control systems are being used to better energy management, plus predictive maintenance. Germany in particular helps, since the machinery and automotive base there is already very strong, and it kind of pulls these deployments along.
The more emerging use cases lean into AI assisted engineering, digital twins, and autonomous factory operations. Siemens’ April 2026 Eigen Engineering Agent is a good example, and it sort of shows how AI is starting to execute automation tasks, not only support engineers like before. During the forecast period, virtual commissioning, AI driven quality control, and adaptive robotics could become major additions on top of the usual factory automation, rather than just side projects.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 213 Million |
|
Market size value in 2026 |
USD 217.5 Million |
|
Revenue forecast in 2033 |
USD 251.6 Million |
|
Growth rate |
CAGR of 2.10% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Germany |
|
Key company profiled |
Siemens AG, ABB Ltd., Schneider Electric, Rockwell Automation, Emerson Electric, Mitsubishi Electric, Honeywell International, Omron Corporation, Yokogawa Electric, Bosch Rexroth, Beckhoff Automation, FANUC Corporation, Phoenix Contact, B&R Automation, WAGO GmbH |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Component (Programmable Logic Controllers (PLCs), Distributed Control Systems (DCS), SCADA Systems, Human Machine Interface (HMI), Industrial Robots, Sensors, Drives, Motion Controllers, Machine Vision Systems, Others); By Technology (Industrial IoT, Artificial Intelligence, Edge Computing, Cloud Automation, Digital Twin, Robotics, Machine Learning, Predictive Maintenance, 5G Connectivity, Cybersecurity Solutions, Others); By Industry (Automotive, Manufacturing, Food & Beverage, Pharmaceuticals, Chemicals, Oil & Gas, Energy & Utilities, Electronics, Metals & Mining, Others); By End User (Large Enterprises, SMEs, OEMs, System Integrators, Process Industries, Discrete Manufacturing, Government Industries, Utilities, Contract Manufacturers, Others); By Deployment (On-Premise, Cloud-Based, Hybrid, Smart Factories, Edge Deployment, Private Cloud, Public Cloud, Industrial Networks, Multi-Site Deployment, Others) |
Which Regions are Driving The Germany Industrial Control & Factory Automation Market Growth?
Bavaria is kind of positioned as that leading regional market, mostly because of its big industrial base, stretching across automotive, machinery electronics and advanced manufacturing , so it ends up being a lot more than just one niche. In 2025, the state showed €486.5 billion in industrial turnover and employed about 1.3 million people, through more than 8,000 industrial businesses. Its Industry 4.0 programs, plus a mechatronics ecosystem, engineering suppliers, and the fact that export oriented manufacturers are concentrated in the area, all of that together builds a pretty broad customer group for control systems, robotics, and factory software.
Baden-Württemberg is more like a highly specialized second market. Here, demand is tied tightly to precision engineering, automotive production, robotics, and industrial technology. The strong point is an unusually dense web of manufacturers, suppliers, research institutions, and technology companies. Still, the region is dealing with pressure from the automotive transition, and also weaker export conditions, so that plays a role. As a result, its automation needs feel more innovation driven than volume driven , especially around flexible production, robotics, digital twins, and AI enabled manufacturing.
North Rhine-Westphalia, though, has the strongest growth momentum, because industrial firms are pushing harder on digital and energy transformation across chemicals, metals, machinery, and process manufacturing. NRW.BANK provided €16.2 billion in funding in 2025, and not just in a generic way, but with clearly higher support for economic transformation, digitalization, innovation, and energy transition projects. The new 2026 investment support rules also reach production capacity, energy efficiency, digitalization, and strategic net-zero technologies like batteries and electrolyzers. That ends up making a widening opening for automation vendors, system integrators, and investors through 2026–2033.
Who are the Key Players in The Germany Industrial Control & Factory Automation Market and How Do They Compete?
Competition sort of feels consolidated at the control-platform level, but then it gets more fragmented across robotics, motion control, industrial software, sensing and machine-level automation. Siemens competes by going all-in on deep integration: PLCs, engineering software, digital twins, and even AI, you know, the whole stack. Schneider Electric instead leans into an open software-defined automation story, built to connect operational technology with IT and also hybrid environments, in a practical way. ABB competes pretty hard where robotics and intelligent machine automation overlap, it does this via wide robot portfolios, application cells, vision, and AI-enabled capabilities that actually land in the field.
Beckhoff takes a different route, kinda sideways, by emphasizing PC-based control, EtherCAT, TwinCAT, and modular software, not the usual PLC-centered architecture. Its 2026 portfolio adds AI-assisted engineering and physical-AI capabilities, on top of that openness. Bosch Rexroth is more focused on production machinery and motion-intensive jobs, combining controls with hydraulics, robotics, simulation, and operator guidance , for manufacturers who want integrated production systems that do not feel stitched together.
All of this means competition is increasingly about interoperability, engineering speed, lifecycle services, AI integration, and the ability to modernize existing factories without major disruption.
Company List
- Siemens AG
- ABB Ltd.
- Schneider Electric
- Rockwell Automation
- Emerson Electric
- Mitsubishi Electric
- Honeywell International
- Omron Corporation
- Yokogawa Electric
- Bosch Rexroth
- Beckhoff Automation
- FANUC Corporation
- Phoenix Contact
- B&R Automation
- WAGO GmbH
Recent Development News
- In April 2026, Siemens AG entered a strategic partnership with KION Group. The companies are combining AI, automation, simulation, and digital-twin technologies to digitalize complex intralogistics processes and create more predictable, flexible, and resilient warehouses across Europe. https://press.siemens.com
- In April 2026, OMRON Corporation entered a partnership with Dassault Systèmes. The collaboration combines virtual-twin technology with industrial automation to allow manufacturers to design and validate production systems virtually before deployment, supporting more flexible and software-driven factories. https://automation.omron.com
What Strategic Insights Define the Future of The Germany Industrial Control & Factory Automation Market?
Germany industrial control and factory automation market is sort of quietly shifting, you know, from equipment centered automation toward software-defined , AI assisted, and more and more autonomous output. The main pull isnt only “automation” as a word, but the push to recover manufacturing productivity while plants try to cope with worker shortages, energy price pressure , supply chain uncertainty, and frankly with ever-more complex product variations. There is also a less obvious danger, and it’s vendor concentration. When PLCs, engineering software, robotics, and industrial AI get tied in deeper, manufacturers can end up stuck in particular ecosystems. Then migration costs and cybersecurity exposure may end up mattering more than what the headline growth numbers usually imply.
At the same time, AI-native engineering and virtual commissioning are starting to look like a real chance, because they can cut machine development cycles down without immediately needing physical capacity expansion. So market players should lean into open architectures, interoperable data models, and retrofit ready AI solutions, instead of just pushing standalone automation hardware. This can help capture modernization budget across both new factories greenfield builds, and Germany huge installed base of older production assets.
Germany Industrial Control & Factory Automation Market Report Segmentation
By Component
- Programmable Logic Controllers (PLCs)
- Distributed Control Systems (DCS)
- SCADA Systems
- Human Machine Interface (HMI)
- Industrial Robots
- Sensors
- Drives
- Motion Controllers
- Machine Vision Systems
- Others
By Technology
- Industrial IoT
- Artificial Intelligence
- Edge Computing
- Cloud Automation
- Digital Twin
- Robotics
- Machine Learning
- Predictive Maintenance
- 5G Connectivity
- Cybersecurity Solutions
- Others
By Industry
- Automotive
- Manufacturing
- Food & Beverage
- Pharmaceuticals
- Chemicals
- Oil & Gas
- Energy & Utilities
- Electronics
- Metals & Mining
- Others
By End User
- Large Enterprises
- SMEs
- OEMs
- System Integrators
- Process Industries
- Discrete Manufacturing
- Government Industries
- Utilities
- Contract Manufacturers
- Others
By Deployment
- On-Premise
- Cloud-Based
- Hybrid
- Smart Factories
- Edge Deployment
- Private Cloud
- Public Cloud
- Industrial Networks
- Multi-Site Deployment
- Others
Frequently Asked Questions
Find quick answers to common questions.
The expected Germany Industrial Control & Factory Automation Market size for the market will be USD 251.6 Million in 2033.
Key segments for The Germany Industrial Control & Factory Automation Market are By Component (Programmable Logic Controllers (PLCs), Distributed Control Systems (DCS), SCADA Systems, Human Machine Interface (HMI), Industrial Robots, Sensors, Drives, Motion Controllers, Machine Vision Systems, Others); By Technology (Industrial IoT, Artificial Intelligence, Edge Computing, Cloud Automation, Digital Twin, Robotics, Machine Learning, Predictive Maintenance, 5G Connectivity, Cybersecurity Solutions, Others); By Industry (Automotive, Manufacturing, Food & Beverage, Pharmaceuticals, Chemicals, Oil & Gas, Energy & Utilities, Electronics, Metals & Mining, Others); By End User (Large Enterprises, SMEs, OEMs, System Integrators, Process Industries, Discrete Manufacturing, Government Industries, Utilities, Contract Manufacturers, Others); By Deployment (On-Premise, Cloud-Based, Hybrid, Smart Factories, Edge Deployment, Private Cloud, Public Cloud, Industrial Networks, Multi-Site Deployment, Others).
Major Germany Industrial Control & Factory Automation Market players are Siemens AG, ABB Ltd., Schneider Electric, Rockwell Automation, Emerson Electric, Mitsubishi Electric, Honeywell International, Omron Corporation, Yokogawa Electric, Bosch Rexroth, Beckhoff Automation, FANUC Corporation, Phoenix Contact, B&R Automation, WAGO GmbH.
The Germany Industrial Control & Factory Automation Market size is USD 213 Million in 2025.
The Germany Industrial Control & Factory Automation Market CAGR is 2.10% from 2026 to 2033.
- Siemens AG
- ABB Ltd.
- Schneider Electric
- Rockwell Automation
- Emerson Electric
- Mitsubishi Electric
- Honeywell International
- Omron Corporation
- Yokogawa Electric
- Bosch Rexroth
- Beckhoff Automation
- FANUC Corporation
- Phoenix Contact
- B&R Automation
- WAGO GmbH
About the Authors

Avinash Kumar
I’m Avinash Kumar, a Senior Research Analyst at Transpire Insight, with expertise in the Electronics and Semiconductor and Energy & Power industry. My work focuses on analyzing emerging technologies, market trends, industry developments, and innovation across these sectors. I specialize in transforming complex technical and market insights into clear, research-backed content that helps professionals, businesses, and decision-makers stay informed. Through continuous industry research and data-driven analysis, I strive to deliver accurate, reliable, and practical perspectives on the latest advancements shaping the semiconductor and energy landscape.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
Apr 2026
Fiber Optic Faceplates Market
Fiber Optic Faceplates Market Size, Share & Analysis Report By Type (< 300 mm2, 300-350 mm2, and > 350 mm2, By Application (Night Vision, Holographic Imaging, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
High Temperature Superconductors Market
High Temperature Superconductors Market Size, Share & Analysis Report By Type (1G HTS, and 2G HTS), By Application (Power Cable, Fault Current Limiter, and Transformer), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Industrial Plugs and Socket Market
Industrial Plugs and Socket Market Size, Share & Analysis Report By Type (Industrial Plugs, Industrial Sockets), By Current (Up to 32 A, 32 to 125 A, Above 125 A), By Protection (Dustproof and Splash Proof, Waterproof, Explosion Proof), By End User (Heavy Industries, Oil and Gas, Chemicals and Pharmaceuticals, Power Generation, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
InGaAs Avalanche Photodiodes Market
InGaAs Avalanche Photodiodes Market Size, Share & Analysis Report By Type (1100 - 1700 nm, and 1000 - 1600 nm), By Application (Missile Warning System, Muzzle Flash Detection, Wafer Defect Inspection, Laser Rangefinders, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031