
Asia Pacific Aluminosilicate Glass Market Summary
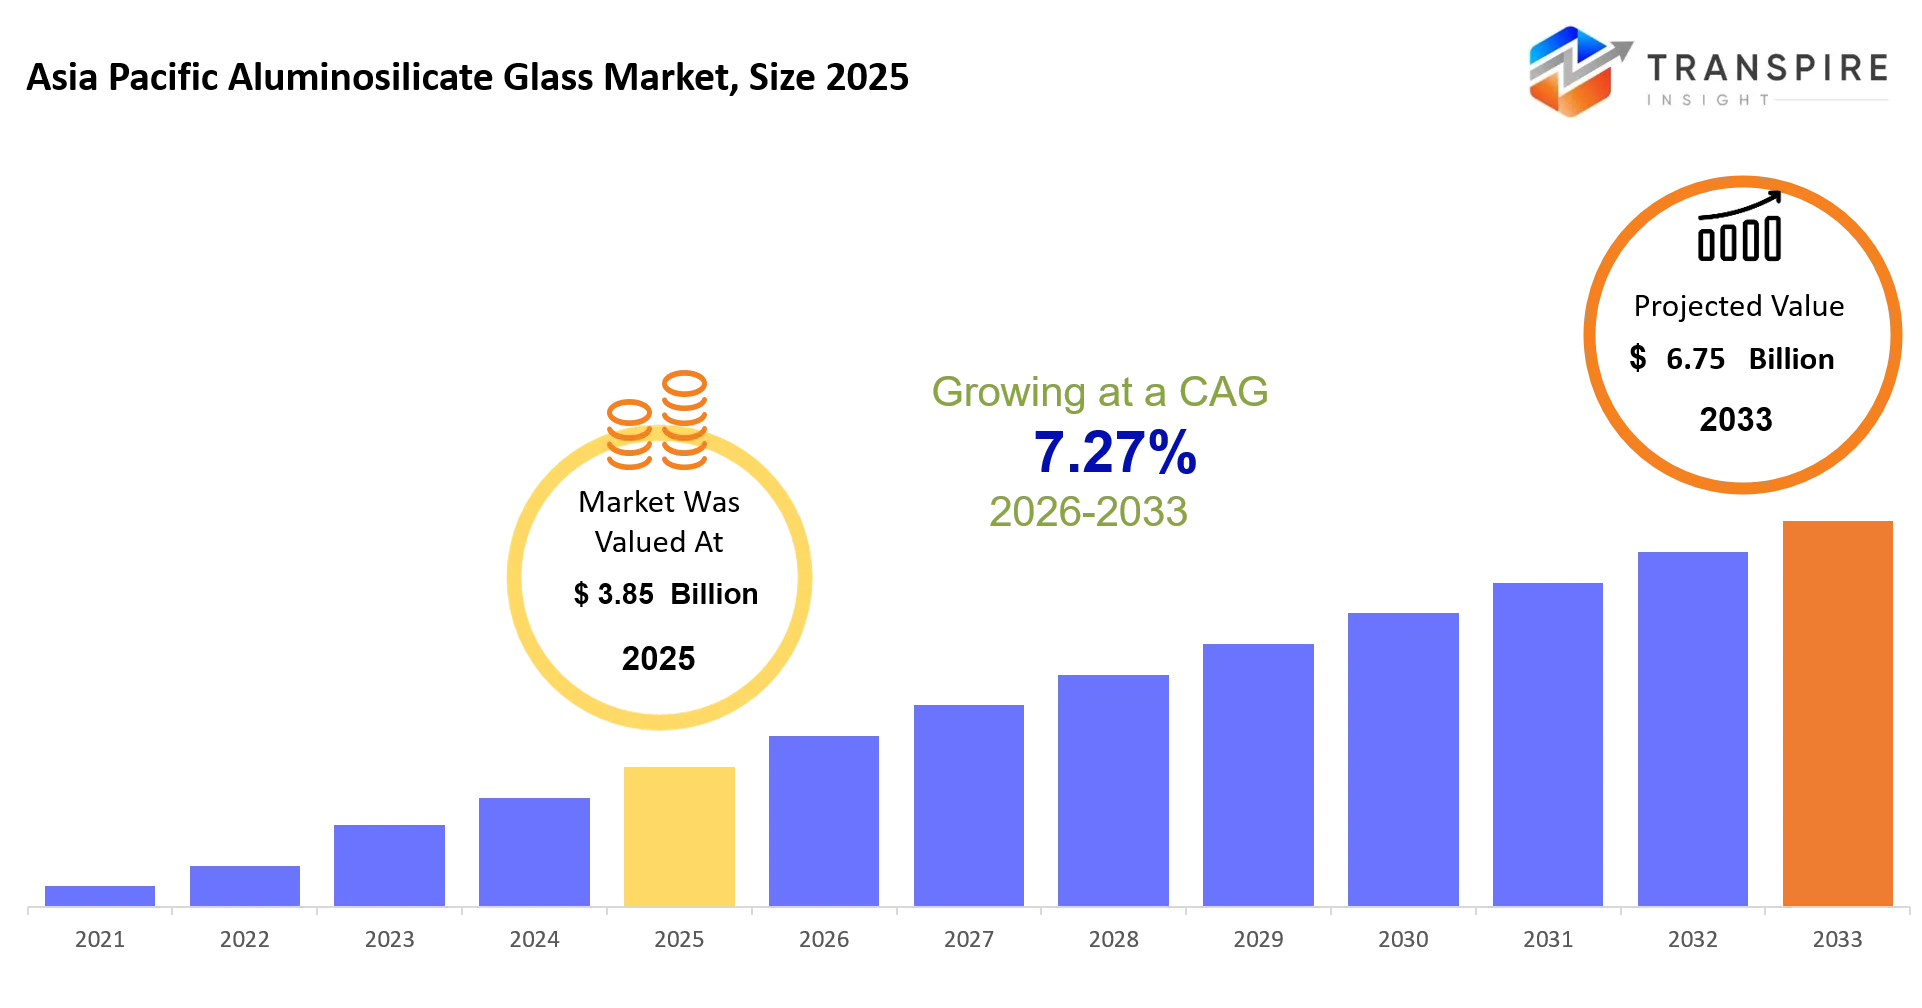
As per Transpire Insight Analysis, the Asia Pacific Aluminosilicate Glass Market size is estimated at USD 3.85 Billion in 2025 and is anticipated to reach USD 6.75 Billion by 2033, growing at a CAGR of 7.27% from 2026 to 2033.
The Asia Pacific Aluminosilicate Glass Market kind of supports a bunch of industries that need transparent materials that can handle extreme heat, mechanical stress,and chemical exposure without really losing performance. It matters a lot for consumer electronics , automotive displays, aerospace parts, industrial equipment, and even more advanced laboratory usage where typical glass just can’t keep up with durability expectations. Over the past 3 to 5 years, the market moved away from only niche, high-performance needs and it now backs large-scale production of premium electronic devices, electric vehicles, and smart display technologies. At the same time semiconductor supply chain disruptions and some trade uncertainties pushed manufacturers to rely more on regional production and to also diversify their sourcing, across Asia Pacific. That shift, honestly, sped up investment in local processing capacity and in advanced manufacturing technologies. As device makers and industrial producers chase thinner, lighter, and more resilient materials, aluminosilicate glass turned into a go to option, helping enable higher-value product designs, wider commercial use, and steadier long term revenue chances across multiple end use industries.
Asia Pacific Aluminosilicate Glass Market Size & Forecast:
- Asia Pacific Aluminosilicate Glass Market Size 2025: USD 3.85 Billion
- Expected Market Value 2033: USD 6.75 Billion
- Forecast CAGR: 7.27%
- Leading region in 2025: East Asia
- Fastest Growing region: South Asia
- Key Profile: Corning, AGC Inc., SCHOTT AG, Nippon Electric Glass, Guardian Glass, NSG Group, Xinyi Glass, Saint-Gobain, Tunghsu Optoelectronic, Central Glass, NEG, China Southern Glass, Fuyao Glass, Asahi India Glass, IRICO Group
Key Market Insights
- East Asia kind of dominated the Asia Pacific aluminosilicate glass industry around 62% market share in 2025, and this is supported by integrated electronics manufacturing, plus that specialty glass production angle too
- South Asia, however, is projected to stay the fastest-growing region during 2025–2033 , being fueled by electronics manufacturing investments, automotive expansion, and also strategic industrial policies in general
- For the product side, Thin aluminosilicate glass was basically leading with nearly 48% market share in 2025, mostly due to premium smartphones, tablets, and foldable display adoption that keeps getting bigger
- Chemically strengthened aluminosilicate glass is next as the second-largest segment, mainly because automotive displays and industrial equipment are needing higher impact resistance over time
- Ultra-thin flexible aluminosilicate glass is expected to see the quickest growth through 2033, and that’s tied to foldable devices , along with advanced wearable technologies that are becoming more common
- When looking at applications, consumer electronics still stayed dominant at about 45% market share in 2025, which mirrors ongoing product innovation and higher display performance requirements
- Automotive displays and smart cockpit systems are the fastest-growing application, especially as electric vehicle production keeps accelerating through the forecast period
- On the end-user demand side, consumer electronics manufacturers accounted for roughly 44% in 2025, helped by rapid premium device production across Asia Pacific
- And for the end-user category expected to surge fastest, Automotive OEMs are likely to take that spot by 2033, driven by digital dashboards, ADAS integration, and connected vehicle platforms that keep expanding
What are the Key Drivers, Restraints, and Opportunities in the Asia Pacific Aluminosilicate Glass Market?
The most powerful pull comes from that rapid shift toward premium consumer electronics, and yeah, digital vehicle cabin setups. Foldable displays, bigger infotainment screens, and lighter electronic devices basically need stronger, yet thinner, specialty glass than what you’d use in older conventional options. As output volumes went up, processing costs went down, and display tech kept leveling up. That mix then pushed broader usage across smartphones tablets, in-car screens, and even industrial gear. In response, companies widened their regional production footprint which then helps build steadier revenue streams across the specialty glass value chain, like from upstream inputs all the way through downstream supply.
Still, the main brake is the big capital demand tied to precision melting, chemical strengthening, and strict quality inspection facilities. Making the stuff also leans on very specialized raw materials, plus advanced manufacturing know-how, and those capabilities can’t be rebuilt quickly. From the Transpire Insight review of regional procurement updates, and launch timelines, the biggest operational concern is supply chain concentration. When capacity gets squeezed, it slows down commercial rollouts, stretches customer qualification timelines, and basically mutes revenue chances when demand outruns the production that’s actually available.
There is a big opportunity sitting in advanced display technologies, and localized manufacturing investment across India, and parts of Southeast Asia, too. Many governments keep backing semiconductor ecosystems, plus electronics manufacturing, via industrial incentive programs , that are meant to pull investment closer to home. Flexible displays, augmented reality devices and even more intelligent automotive cockpits are basically pushing the need for next generation aluminosilicate materials—materials with better optical clarity and more durability. Firms that start early on regional processing capability, along with advanced coating technologies, should end up with more solid supply agreements , and also stronger long term competitive standing.
What Has the Impact of Artificial Intelligence Been on the Asia Pacific Aluminosilicate Glass Market?
Artificial intelligence is quietly reshaping specialty glass manufacturing, not just in a clean straight line way, but more like several things happen at once. It improves production consistency, supports quality inspection, and helps with process optimization, all of which then feed back into yield. AI-based vision systems can spot microscopic surface defects that older inspection approaches sometimes miss, so less material gets thrown away and the manufacturing yield goes up a bit. Meanwhile, smart control platforms keep nudging furnace temperatures, chemical strengthening cycles, and polishing parameters, trying to keep the product quality steady even when you’re running big production batches.
Machine learning models also back predictive maintenance, meaning they can recognize abnormal equipment behavior earlier than you’d expect, before failures show up. That helps reduce surprise downtime and can extend asset life. There are also digital forecasting tools that look at electronics production schedules, automotive manufacturing trends, and procurement patterns, to make inventory planning and production allocation feel less chaotic. In the end these capabilities help manufacturers use equipment more efficiently, shorten production cycles, and lower operating costs, while also supporting faster customer deliveries.
AI-driven analytics can even reinforce compliance, especially with the more demanding quality specifications for display glass and industrial uses. Still, adoption is uneven, because advanced AI setups usually demand major investments in sensors, industrial connectivity, and high quality operational data. Smaller manufacturers often have trouble justifying the integration expenses, and if the production datasets are inconsistent, the prediction accuracy can wobble during the first phases of implementation, even if the technology looks promising on paper.
Key Market Trends
- Foldable phone production sort of expanded after 2022, which then sped up demand for ultra-thin chemically strengthened glass, with better bending ability and also more scratch resistance.
- Automotive makers started using bigger digital cockpit displays more often during 2023–2026, and that basically boosted demand for durable specialty glass with stronger optical performance, the kind that keeps the images clear.
- Meanwhile India and parts of Southeast Asia pulled in extra electronics manufacturing investments between 2023 and 2026, so dependency on a few very concentrated supply chains got reduced.
- AI driven optical inspection systems are now helping defect detection jump by over 20% inside advanced specialty glass factories, like the rates improved noticeably.
- Chemical strengthening methods also moved toward shorter processing cycles , which helps manufacturers raise throughput while still keeping those premium durability targets in place.
- At the same time display manufacturers are increasingly pairing up with specialty glass suppliers to co-develop materials that fit OLED, microLED and foldable device use cases more closely.
- Regional governments expanded semiconductor and electronics incentives after 2023, and this encouraged additional investments in higher value specialty material manufacturing too.
- On the factory side, companies increased automation across furnace control and finishing operations, aiming for steadier yield consistency, and less production variability overall.
- Finally after a few recent supply chain disruptions, companies diversified how they source raw materials, and that improved operational resilience across the Asia Pacific specialty glass ecosystem, pretty directly.
Asia Pacific Aluminosilicate Glass Market Segmentation
By Product Type :
Chemically strengthened glass keeps a kind of edge , mainly because it resists scratches, impact, and all that repeated mechanical stress you get day to day. The uptake is pretty widespread across smartphones, tablets, automotive screens, and even wearable devices , so factories can keep steady output. As companies keep investing in stronger but also lighter materials , that momentum should push it into even more premium electronics. Thermally strengthened glass still holds solid demand too, especially in industrial machinery, lab equipment, and those higher temperature uses where thermal resistance is kind of non negotiable
Specialty aluminosilicate glass is also climbing in value , notably in aerospace, medical devices , and advanced industrial systems that need high optical clarity as well as chemical steadiness. Ultra thin glass is moving fast, because foldable displays, compact electronics, and next gen touch panels want less weight but still great pliability. Ongoing product development keeps working on better strength while shaving down thickness, so newer display technologies benefit. And then other specialty grades fit those more niche industrial needs where tailored performance traits open up extra business chances
By Application :
Consumer electronics sit on top of the biggest share of market revenue, largely because smartphones, tablets , laptops, and wearable devices still need durable display protection with superior optical performance . Product launches that lean on premium displays are still widening material consumption across the manufacturing facilities. Then there’s automotive too, where applications keep broadening as digital instrument clusters, infotainment systems, and head-up displays become almost standard in modern vehicles. In general, display quality and impact resistance stay as major purchasing factors for vehicle manufacturers.
Aerospace applications lean on high strength glass for cockpit displays plus specialized equipment that has to deal with demanding operating conditions. Medical devices, in turn, call for reliable glass in diagnostic equipment and precision instruments where durability and clarity are basically non negotiable. Industrial equipment uses specialty glass in control panels, inspection systems, and other setups that face high temperature environments. Solar panels, and a few other emerging areas, are also opening new opportunities, because advanced glass technologies keep improving efficiency while extending product lifespan.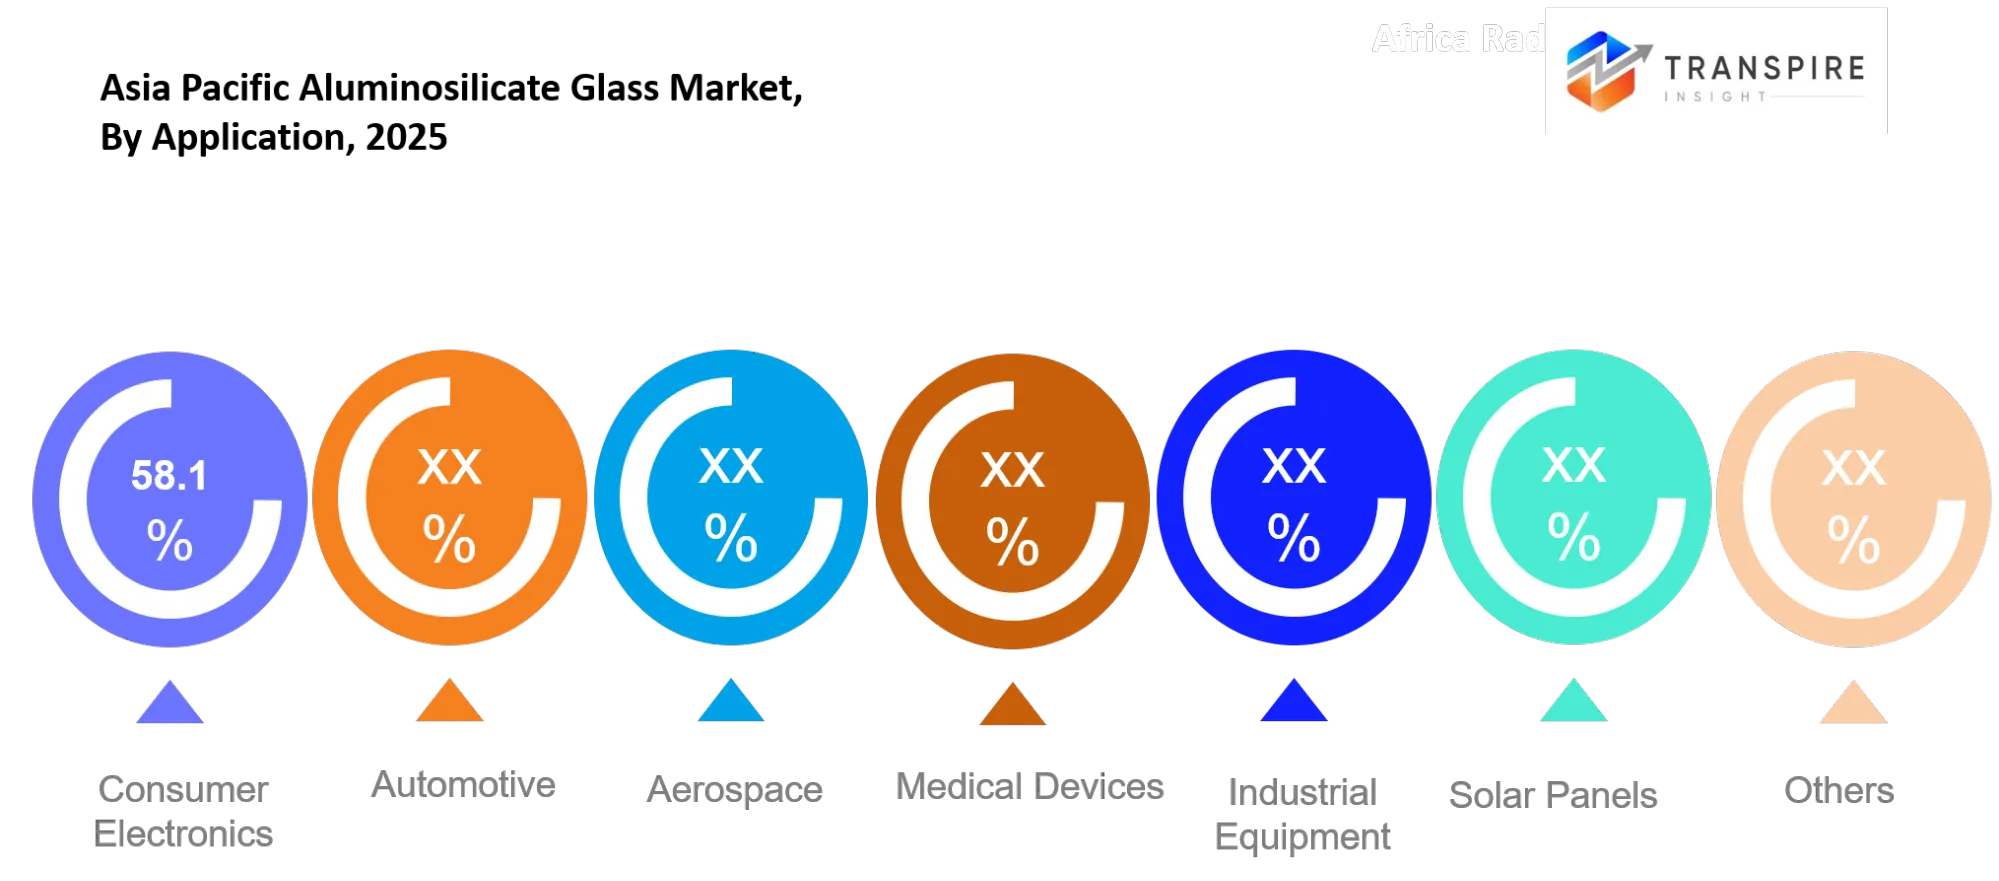
By End User :
Electronics manufacturers are taking the biggest share, because the mass, high-volume making of smart devices kind of forces durable and still lightweight display materials, you know. At the same time premium product positioning keeps pushing investment into advanced glass technologies, giving them better performance traits . Automotive OEMs are also steadily upping procurement since vehicle interiors are moving toward larger digital displays and, honestly, more connected driving systems. Over longer horizons, long-term supply agreements help lock in production schedules across the different manufacturing sites.
In healthcare, companies lean on specialty glass for imaging systems, lab instruments and medical diagnostic equipment, things that need stable operation even when conditions get demanding. In aerospace, industry players keep adopting advanced materials that blend strength with reduced weight for specialized applications. Meanwhile industrial manufacturers broaden their usage in automation equipment and precision machinery, where reliability pretty directly influences day-to-day operational efficiency. Beyond that, other end users add extra demand via tailored industrial and commercial applications.
By Thickness :
Below 1 mm glass keeps getting strong adoption, mostly because compact electronics and foldable devices really need thinner lighter materials, but they still can’t give up on durability, not even a little. In other words, makers keep pushing for better flexibility, while also trying to hold onto excellent scratch resistance, and a clear optical view which matters a lot. The 1–3 mm thickness zone covers a pretty wide mix of uses, like consumer electronics, automotive displays, and different industrial projects where the right mix of strength plus weight is still the priority. Steady production volumes then help keep demand fairly consistent across multiple sectors.
Once you move into the 3–5 mm segment it tends to show up in industrial equipment, architectural products, and certain commercial setups that want extra backbone. Past 5 mm, thick glass is used for tougher industrial and scientific tasks, where heavy-duty performance stays nonnegotiable. At the same time, continuous refinements keep improving how well the material handles thermal shock, and harsh working environments in general. And for some cases, customized thickness choices get used instead of “standard” products because those basics just can’t fully meet every single application demand.
By Distribution Channel :
Direct sales still matter quite a bit because the big manufacturers tend to favor long term agreements, plus ongoing technical help and steady quality control from those specialty glass producers. There is close coordination between suppliers and clients, and it really helps with more tailored product development , also with keeping production timetables relatively stable. OEM supply keeps a strong grip on the market because electronics and automotive manufacturers often build specialty glass right into their finished products, as part of the production run. When the supplier relationships are solid, it also boosts planning efficiency and makes delivery reliability a lot better.
Glass distributors add a layer of regional reach by feeding smaller manufacturers and also specialized industrial customers, who usually want flexible buying arrangements. The distribution networks also help product availability, especially across those developing manufacturing sites. Besides that, other sales routes usually target niche customers , people who have specialized technical needs and place smaller order quantities. As regional manufacturing activity grows, it will keep opening new doors for all of these distribution approaches.
What are the Key Use Cases Driving the Asia Pacific Aluminosilicate Glass Market?
The biggest chunk of material consumption is coming from consumer electronics, where high-end smartphones, tablets, and laptops depend on high-strength display glass not just for durability but also for optical clarity and that overall clean look. Electronics manufacturers end up buying very large production volumes because thinner yet sturdier glass makes it possible to build lightweight product designs. At the same time it helps reduce breakage during normal daily use, and also during transportation, which is kind of a constant issue.
Automotive manufacturers are getting more interested too, since digital instrument clusters, infotainment displays, and head-up displays are becoming more common across electric vehicles as well as premium models. Medical device companies then follow that trend using specialty glass inside diagnostic systems and lab equipment, where stable performance, chemical resistance, and precision still need to stay dependable for reliable operation every day.
On the newer side, emerging opportunities are showing up in augmented reality devices, foldable computing products, and advanced aerospace display systems, which sounds niche but is moving fast. Industrial automation equipment is another area, especially smart control panels and next-generation human machine interfaces, they will likely open additional commercial opportunities as manufacturers invest in digital production facilities and advanced monitoring technologies across Asia Pacific.
|
Report Metrics |
Details |
|
Market size value in 2025 |
USD 3.85 Billion |
|
Market size value in 2026 |
USD 4.13 Billion |
|
Revenue forecast in 2033 |
USD 6.75 Billion |
|
Growth rate |
CAGR of 7.27% from 2026 to 2033 |
|
Base year |
2025 |
|
Historical data |
2021 - 2024 |
|
Forecast period |
2026 - 2033 |
|
Report coverage |
Revenue forecast, competitive landscape, growth factors, and trends |
|
Regional scope |
Asia Pacific (India, China, Japan, Australia, South Korea, Rest of Asia Pacific) |
|
Key company profiled |
Corning, AGC Inc., SCHOTT AG, Nippon Electric Glass, Guardian Glass, NSG Group, Xinyi Glass, Saint-Gobain, Tunghsu Optoelectronic, Central Glass, NEG, China Southern Glass, Fuyao Glass, Asahi India Glass, IRICO Group . |
|
Customization scope |
Free report customization (country, regional & segment scope). Avail customized purchase options to meet your exact research needs. |
|
Report Segmentation |
By Product Type (Chemically Strengthened Glass, Thermally Strengthened Glass, Specialty Aluminosilicate Glass, Ultra-Thin Glass, Others); By Application (Consumer Electronics, Automotive, Aerospace, Medical Devices, Industrial Equipment, Solar Panels, Others); By End User (Electronics Manufacturers, Automotive OEMs, Healthcare Companies, Aerospace Industry, Industrial Manufacturers, Others); By Thickness (Below 1 mm, 1–3 mm, 3–5 mm, Above 5 mm, Others); By Distribution Channel (Direct Sales, OEM Supply, Glass Distributors, Others) |
Which Regions are Driving the Asia Pacific Aluminosilicate Glass Market Growth?
East Asia basically owns the lead, with around 62% of the regional market share. This is mostly backed by electronics manufacturing policies that are pretty strong, along with mature industrial infrastructure and steady, almost constant, spending in semiconductor production. There’s also a dense web of specialty glass producers, display makers, component suppliers, and research centers which somehow ends up making the supply chain more efficient. Add ongoing funding for high-end consumer electronics plus automotive display technologies, and the region should keep its leadership role for the whole forecast horizon.
Southeast Asia, meanwhile, brings in fairly steady revenue because manufacturing activity is diversified and industrial investment is happening consistently across several countries. Trade rules tend to stay stable, and electronics assembly operations keep expanding, so specialty material suppliers can plan purchases with more certainty. Industrial zones, export focused production sites and dependable logistics channels also help strengthen long term buying behavior. With balanced growth across consumer electronics, industrial machinery, and automotive manufacturing, the region expands steadily, without being dependent on just one single industry.
South Asia is the one growing quickest, mainly because electronics manufacturing incentives, and broader industrial development programs have pushed new production investments forward in recent years. More domestic manufacturing capacity, automotive upgrades, and deeper supply chain localization have generated fresh demand for advanced specialty glass. Public and private investment in electronics production keeps improving the region’s manufacturing ability, plus supplier confidence. From 2026 through 2033 , that growth should open attractive chances for new manufacturers, technology providers, and investors who are looking for long term expansion beyond the more mature production hubs.
Who are the Key Players in the Asia Pacific Aluminosilicate Glass Market and How Do They Compete?
Competition still looks pretty consolidated, mainly because advanced manufacturing technology, product quality, and production scale together make it hard for new entrants to join in. In a way, the competition is mostly driven by tech innovation and manufacturing capability, but then again regional production networks, plus customer relationships, quietly steer purchasing decisions. The older, established manufacturers keep widening their specialty product portfolios, whereas the newer participants tend to pick a few applications and put money into regional manufacturing investments, in order to firm up their position.
Corning stands out by continuously innovating chemically strengthened glass, aimed at premium consumer electronics and advanced display use cases. AGC Inc. boosts its competitiveness through investment in advanced glass processing technologies, these raise optical performance while also improving manufacturing efficiency. Nippon Electric Glass keeps strengthening its market position via specialty glass solutions for electronics, industrial equipment, and scientific applications, where high reliability is still not optional.
SCHOTT concentrates on technical glass products, with strong thermal resistance and precision manufacturing that fits medical and industrial sectors. Xinyi Glass expands its regional manufacturing capacity, to support more reliable supply, and to serve rising automotive and electronics production across Asia. Fuyao Glass builds its competitive edge through advanced automotive glass technologies, and it continues investing in digital manufacturing processes that help raise production quality, plus operational efficiency, even when conditions are changing.
Company List
- Corning
- AGC Inc.
- SCHOTT AG
- Nippon Electric Glass
- Guardian Glass
- NSG Group
- Xinyi Glass
- Saint-Gobain
- Tunghsu Optoelectronic
- Central Glass
- NEG
- China Southern Glass
- Fuyao Glass
- Asahi India Glass
- IRICO Group
Recent Development News
In March 2026, Corning Incorporated launched Corning® Gorilla® Glass Ceramic 3. The new glass ceramic offers substantially higher repeated-drop durability for premium mobile devices and will strengthen demand for advanced aluminosilicate glass across smartphone manufacturing in Asia Pacific. Source https://www.corning.com/
In December 2025, Corning Incorporated and Optiemus Infracom confirmed plans to begin Gorilla Glass cover-glass finishing in India during the first half of 2026. The investment will expand regional manufacturing capability, support smartphone supply chains, and strengthen India's position in specialty glass production. Source https://www.moneycontrol.com/
What Strategic Insights Define the Future of the Asia Pacific Aluminosilicate Glass Market?
The Asia Pacific Aluminosilicate Glass Market is likely to drift toward higher value, kind of application specific material kinds, instead of going all-in on pure volume led expansion during the next five to seven years. You know, advanced display technologies, electric vehicles, semiconductor manufacturing, and precision industrial equipment will push this shift because every one of them really needs stronger glass, but also lighter and more durable, with tighter performance requirements too.
There’s also a less obvious, more quiet risk, sort of supply chain concentration for high purity raw materials and for advanced processing capacity , which might constrain manufacturing agility even if customer demand stays strong. At the same time, localizing manufacturing in India and in Southeast Asia creates a meaningful window of opportunity since electronics production keeps moving beyond the older, traditional manufacturing centres.
If companies make early moves on regional processing facilities and build technical partnerships, it should improve long term competitiveness. In general, firms that diversify raw material sources while expanding research, plus manufacturing, near the growing production hubs will be better set to win steady contracts and also capture future revenue growth.
Asia Pacific Aluminosilicate Glass Market Report Segmentation
By Product Type
- Chemically Strengthened Glass
- Thermally Strengthened Glass
- Specialty Aluminosilicate Glass
- Ultra-Thin Glass
By Application
- Consumer Electronics
- Automotive
- Aerospace
- Medical Devices
- Industrial Equipment
- Solar Panels
By End User
- Electronics Manufacturers
- Automotive OEMs
- Healthcare Companies
- Aerospace Industry
- Industrial Manufacturers
By Thickness
- Below 1 mm
- 1–3 mm
- 3–5 mm
- Above 5 mm
By Distribution Channel
- Direct Sales
- OEM Supply
- Glass Distributors
Frequently Asked Questions
Find quick answers to common questions.
The Expected Asia Pacific Aluminosilicate Glass Market size for the Market will be USD 6.75 Billion in 2033.
Key Segments for the Asia Pacific Aluminosilicate Glass Market are By Product Type (Chemically Strengthened Glass, Thermally Strengthened Glass, Specialty Aluminosilicate Glass, Ultra-Thin Glass, Others); By Application (Consumer Electronics, Automotive, Aerospace, Medical Devices, Industrial Equipment, Solar Panels, Others); By End User (Electronics Manufacturers, Automotive OEMs, Healthcare Companies, Aerospace Industry, Industrial Manufacturers, Others); By Thickness (Below 1 mm, 1–3 mm, 3–5 mm, Above 5 mm, Others); By Distribution Channel (Direct Sales, OEM Supply, Glass Distributors, Others).
Major Asia Pacific Aluminosilicate Glass Market players are Corning, AGC Inc., SCHOTT AG, Nippon Electric Glass, Guardian Glass, NSG Group, Xinyi Glass, Saint-Gobain, Tunghsu Optoelectronic, Central Glass, NEG, China Southern Glass, Fuyao Glass, Asahi India Glass, IRICO Group.
The Current Asia Pacific Aluminosilicate Glass Market size is USD 3.85 Billion in 2025.
The Asia Pacific Aluminosilicate Glass Market CAGR is 7.27% from 2026 to 2033.
- Corning
- AGC Inc.
- SCHOTT AG
- Nippon Electric Glass
- Guardian Glass
- NSG Group
- Xinyi Glass
- Saint-Gobain
- Tunghsu Optoelectronic
- Central Glass
- NEG
- China Southern Glass
- Fuyao Glass
- Asahi India Glass
- IRICO Group
About the Authors

Pankaj Ghogare Patil
I am Pankaj Ghogare Patil, a Senior Research Analyst at Transpire Insight, specializing in the Pharmaceutical, Chemicals & Materials, Healthcare IT, and Biotechnology industry. My expertise lies in conducting comprehensive market research, analyzing industry trends, evaluating competitive landscapes, and translating complex data into actionable insights. At Transpire Insight, I closely follow emerging technologies, regulatory developments, and market innovations to create accurate, well-researched, and informative content that helps businesses and professionals make informed decisions. I am committed to producing credible, evidence-based articles that reflect industry best practices while making technical topics accessible and valuable for a broad audience.

Chakradhar Khansole
Chakradhar serves as the Research Director at Transpire Insight, bringing over 8 years of experience in technology, innovation, and strategic market intelligence. He specializes in transforming complex market data into actionable business insights that enable organizations to make informed, growth-oriented decisions. Recognized for his strategic vision and analytical expertise, Chakradhar leads high-impact research initiatives, delivering comprehensive market assessments, competitive intelligence, and forward-looking industry analysis.
Recently Published Reports
-
May 2026
Healthcare Polymer Packaging Market
Healthcare Polymer Packaging Market Size, Share & Analysis Report By Packaging Type (Syringes, IV Bottles and Pouches, Clamshells, Blisters, Bottles & Jars, Containers, Tubes, IV Parental Packaging, Others), By Type (Regulated, Non-regulated), By Polymer Type (LDPE (Low-Density Polyethylene), HDPE (High-Density Polyethylene), Homo-polymer (Homo), Random Copolymer (Random), Block Copolymer (Block), PET, Polystyrene, Polyvinyl Chloride, Polyamide/EVOH, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Hydrophilic Tape (Waterstop) Market
Hydrophilic Tape (Waterstop) Market Size, Share & Analysis Report By Type (Bentonite-Based Hydrophilic Tape, Rubber-Based Hydrophilic Tape), By Application (Residential Buildings, Commercial Buildings, Infrastructure Projects), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
Metalens Market
Metalens Market Size, Share & Analysis Report By Type (Visible Light Metalens, and Infrared Metalens), By Application (Consumer Electronics, Automotive Electronics, Industrial, Medical, and Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031
-
Apr 2026
PBT Resin Market
PBT Resin Market Size, Share & Analysis Report By Type (Reinforced PBT Resin, Unreinforced PBT Resin), By Processing Method (Injection Molding, Extrusion, Blow Molding, Others), By End-User (Automotive, Electrical & Electronics, Consumer Appliances, Industrial Machinery, Medical Devices, Packaging, Others), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South and Central America), 2021 - 2031