
Nov 05, 2026
Market Forecast
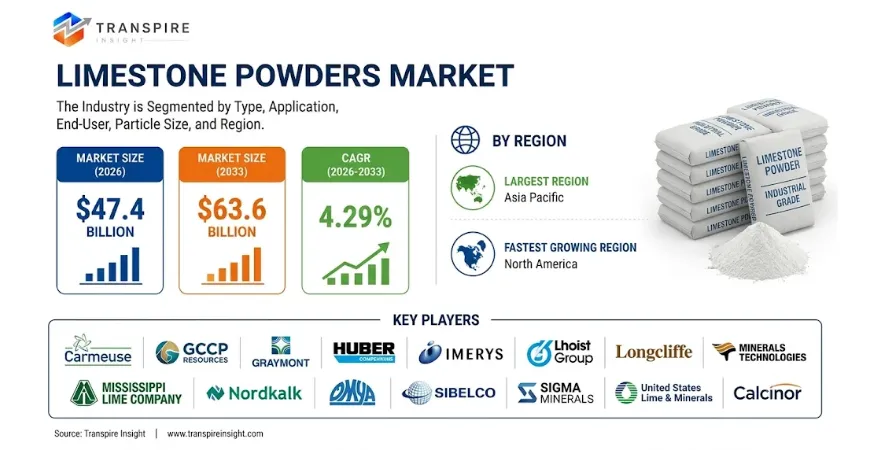
The global limestone powders market was valued at USD 45.2 billion in 2025 and is projected to grow from USD 47.4 billion in 2026 to USD 63.6 billion by 2033, at a CAGR of 4.29% over the forecast period, according to a new report by Transpire Insights.
Limestone powder demand tracks closely with construction activity, agricultural lime application, and industrial manufacturing output. As infrastructure investment accelerates across Asia Pacific and the Middle East, and as agricultural producers lean more heavily on calcium carbonate for soil pH management, the market continues to grow at a steady pace through 2033.
Limestone Powders Market Growth & Trends
Global construction activity is the primary volume driver for limestone powders. Cement production, concrete aggregate, and ready-mix formulations all consume limestone powder in large quantities, and each new infrastructure cycle — roads, housing, commercial real estate — feeds directly into powder demand. Countries running national urbanisation programmes across South and Southeast Asia are generating consistent procurement volumes for limestone suppliers across the region.
Agricultural applications add a separate but substantial demand layer. Arable land acidification is a recognised problem across large farming regions in Latin America, North America, and parts of Europe, and ground calcium carbonate remains the most cost-effective liming agent available at scale. Environmental regulations that limit industrial emissions are also creating demand for limestone powder in flue gas desulfurisation systems, adding another growing use case beyond construction.
Emerging Economies & Technology
India and Southeast Asian markets are the fastest-expanding destinations for limestone powder producers outside of China. National housing programmes, road construction mandates, and rapid commercial development across tier-two and tier-three cities are drawing consistent demand that domestic quarrying operations are struggling to fully service. Import flows from established limestone exporters are filling the gap in several markets.
Ultra-fine and nano-grade powder production is the technology front where investment is concentrating. Paper manufacturers and paint producers are specifying finer and more consistent particle distributions, pushing limestone processors to invest in advanced milling and classification equipment. Precision particle sizing capability is becoming a meaningful competitive differentiator for suppliers serving industrial end-users.
Construction Materials Segment
Construction materials account for 55% of the global limestone powders market — the dominant application by a wide margin. Limestone powder is embedded across the construction supply chain as a filler, aggregate, and reactive component in cement and concrete formulations. The segment's dominance reflects the sheer volume of construction activity globally and the fact that limestone is often the lowest-cost mineral filler available at scale for building material manufacturers.
Continued urbanisation in Asia and Africa, combined with large-scale infrastructure programmes in the Middle East, keeps construction materials at the top of the demand hierarchy through the forecast period. Replacement or displacement of limestone by alternative fillers is unlikely at current price differentials.
Ultra-fine Powders: Fastest-Growing Segment
Ultra-fine limestone powders are growing at a CAGR of 9.5% — the fastest rate across all particle size categories. Their use in high-performance paints and coatings, premium paper grades, and pharmaceutical excipients creates a premium revenue stream that outpaces the base construction market. Manufacturers who have invested in high-energy milling and air classification technology are capturing this growth, while those limited to conventional crushing and grinding face margin pressure from commoditised coarse product competition.
The plastics and rubber industries are also adopting ultra-fine calcium carbonate as a functional filler, both for cost reduction and for improvements in mechanical properties. That adoption is expanding the addressable market for fine-grade producers beyond their traditional paper and coatings customer base.
Asia Pacific — Largest Regional Market
Asia Pacific holds 41% of the global limestone powders market. China is the single largest producer and consumer of limestone powder globally, driven by its domestic cement industry and ongoing construction activity. India is growing rapidly as a market, with limestone powder demand rising in tandem with government-backed housing and road construction targets. Japan and South Korea contribute through their advanced industrial manufacturing sectors, which require high-purity calcium carbonate for electronic material and specialty chemical applications.
Domestic limestone reserves across the region are extensive, giving producers cost advantages over importers. However, quality consistency and particle size control remain areas where Western and established Asian suppliers hold an edge in premium industrial segments.
North America — Fastest-Growing Region
North America is advancing at a CAGR of 8.8% — the highest regional growth rate in this market. The United States construction rebound, combined with growing agricultural lime demand across the Midwest and Southeast, is pushing consumption volumes upward. The Inflation Reduction Act and associated infrastructure investment programmes are generating multi-year demand visibility for construction materials including limestone powder.
North American demand for high-purity pharmaceutical and food-grade calcium carbonate is also growing, driven by dietary supplement manufacturing and food fortification applications. These premium segments carry significantly higher margins than construction-grade powder and are attracting targeted investment from major producers including Minerals Technologies and Huber Engineered Materials.
Recent Developments
Q4 2024 – Imerys: Expanded its ultra-fine calcium carbonate production capacity in France and the United States, targeting high-growth demand from paper coating and paint formulation customers requiring tighter particle size specifications.
Q4 2024 – Omya AG: Announced a long-term supply agreement with a major European cement group to provide micronized limestone powder for low-carbon concrete formulations, supporting the industry's shift toward reduced clinker content.
Q1 2025 – Carmeuse: Commissioned a new high-capacity lime and limestone powder production facility in India to serve growing domestic demand from the construction and steel manufacturing sectors.
Q2 2025 – Minerals Technologies: Launched a new line of precipitated calcium carbonate products optimised for lithium-ion battery separator coatings, targeting the fast-growing electric vehicle supply chain.
Q2 2025 – Lhoist Group: Completed the acquisition of a regional limestone quarrying and processing operation in Southeast Asia to strengthen its supply footprint across the ASEAN construction market.
Q3 2025 – Nordkalk: Invested in advanced air classification technology at its Finnish processing facilities to expand ultra-fine powder production capacity for Scandinavian paper and paint industry customers.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: inquiry@transpireinsight.com
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


