
Aug 10, 2026
Market Forecast
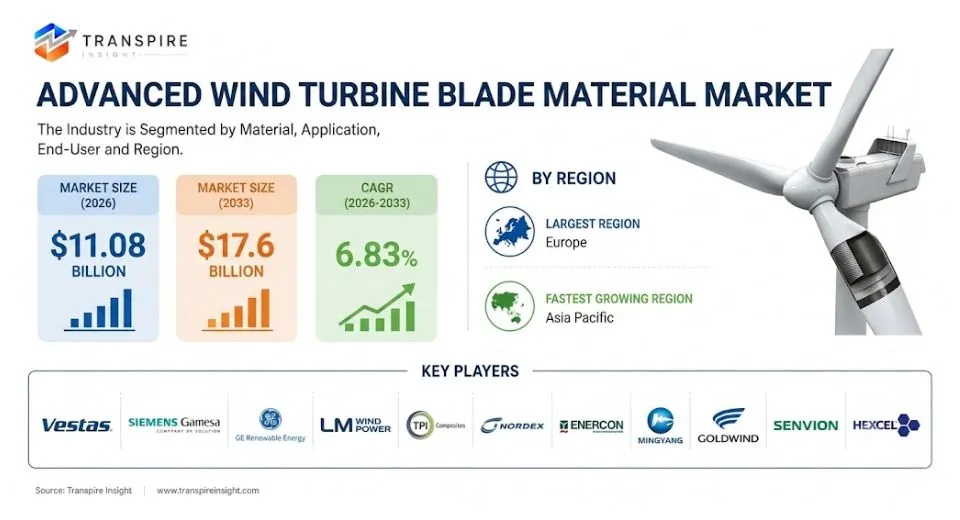
The advanced wind turbine blade material market was valued at USD 10.43 billion in 2025 and is projected to grow from USD 11.08 billion in 2026 to USD 17.6 billion by 2033, at a CAGR of 6.83% through the forecast period, according to a new report by Transpire Insights.
Accelerating wind energy capacity additions onshore and offshore are the structural driver behind this market. As turbines grow larger to capture more energy at lower cost per kilowatt-hour, blades must extend in length while maintaining structural integrity and minimising weight. That engineering constraint creates consistent demand for high-performance composite materials, with carbon fibre and advanced glass fibre systems displacing older material specifications on every new turbine generation entering production.
Advanced Wind Turbine Blade Material Market Growth & Trends
Wind turbine platforms are scaling at a pace that would have seemed ambitious a decade ago. Offshore turbines with rotor diameters exceeding 220 metres and rated outputs of 15 MW or more are moving from prototype to series production, with blade lengths now routinely exceeding 100 metres on the largest platforms. At these dimensions, the structural and aerodynamic requirements cannot be met with conventional glass fibre composites alone; carbon fibre reinforcement in spar caps is now standard on blades above approximately 70 metres, and the longest offshore blades use carbon fibre extensively throughout their structural architecture.
National renewable energy targets in the EU, US, China, India, and the UK are creating committed installation pipelines that give turbine OEMs and their blade material suppliers multi-year demand visibility. The EU's REPowerEU plan, the US Inflation Reduction Act production tax credits, and China's 14th Five-Year Plan for energy all contain specific wind capacity targets that translate directly into turbine orders and, downstream, into blade material procurement. This policy-backed demand certainty is encouraging material manufacturers to invest in production capacity expansion ahead of the demand peak.
Emerging Economies & Technology
Asia Pacific and China in particular is the fastest-growing region in this market by a substantial margin, driven by the world's largest wind installation programme running alongside a domestic turbine manufacturing industry that is itself the largest on earth. Chinese OEMs including Mingyang and Goldwind are deploying increasingly large turbine platforms domestically and competing internationally, which creates blade material demand at scale and is also spurring domestic carbon fibre and composite supply chain development to reduce dependence on imported materials.
Recyclability is emerging as a critical technical and commercial requirement that is reshaping material development priorities across the industry. Conventional thermoset resin systems used in wind blade manufacturing are not practically recyclable at end of life, creating a growing environmental liability as first-generation utility-scale wind farms approach decommissioning. Thermoplastic resin systems that enable blade disassembly and material recovery are attracting significant R&D investment from both material suppliers and turbine OEMs. Manufacturers that can offer recyclable blade material systems will hold an increasingly clear advantage as sustainability requirements become written into procurement specifications and regulatory frameworks across the EU and elsewhere.
Carbon Fibre Segment
Carbon fibre holds 49% of the advanced wind turbine blade material market, the dominant material by revenue. Its adoption is driven by physics: at the blade lengths required for today's utility-scale and offshore turbines, glass fibre spar cap designs become too heavy and too flexible to deliver the structural performance and fatigue life that turbine OEMs need. Carbon fibre enables longer, lighter, stiffer blades that capture more energy, withstand higher loads, and reduce drivetrain fatigue compared to equivalent glass-only designs.
Wind energy is now one of the largest single industrial consumers of carbon fibre globally, and that concentration gives the blade industry meaningful influence over carbon fibre supply chain development. Toray Industries, Hexcel, Teijin, and Mitsubishi Chemical the major carbon fibre producers have all made wind energy a priority market, with dedicated supply agreements, product development partnerships with blade manufacturers, and capacity investments aligned to the long-term wind installation pipeline.
Glass Fibre: Fastest-Growing Segment
Glass fibre is growing at a CAGR of 16.7% the fastest rate across all blade material categories. While carbon fibre dominates structural spar cap applications on the largest platforms, glass fibre remains the primary reinforcement material for blade shells, trailing edges, and smaller turbine platforms where its lower cost and easier processing characteristics give it a significant total cost of ownership advantage. The sheer volume of wind capacity being installed globally including a large number of onshore turbines in the 4-6 MW range where glass fibre is fully viable sustains enormous glass fibre demand alongside carbon fibre growth.
Advanced glass fibre compositions including high-strength and high-modulus variants that close some of the stiffness gap with standard carbon fibre at lower cost are expanding the performance envelope of glass-based designs and enabling glass fibre to compete on some blade sections where carbon would otherwise be specified. Owens Corning and other glass fibre manufacturers are actively developing wind-specific product grades, supported by their material science expertise and established relationships with blade manufacturers.
Europe – Largest Regional Market
Europe holds 40% of the advanced wind turbine blade material market, the largest regional share. The continent has the world's largest installed offshore wind capacity and an ambitious pipeline that is substantially expanding that position through the 2030s. The North Sea, Baltic Sea, and Atlantic offshore zones are all host to major development programmes by operators including Ørsted, Vattenfall, RWE, and Equinor, each deploying the largest available turbine platforms. The blade material intensity of offshore turbines where platform size and durability requirements maximize advanced composite specification makes European offshore wind a disproportionately high-value blade material market.
LM Wind Power's manufacturing operations across Denmark, Poland, Spain, and India sit within the European supply chain and produce blades for multiple OEMs. Siemens Gamesa and Vestas, both European-headquartered OEMs, operate blade manufacturing networks but maintain significant European production for domestic project supply, sustaining European blade material demand even as production footprints diversify.
Asia Pacific – Fastest-Growing Region
Asia Pacific is expanding at a CAGR of 18.1% by far the highest regional rate in this market. China's wind installation programme is the world's largest by a significant margin, with annual onshore and offshore additions consistently exceeding 60 GW. The sheer scale of Chinese turbine production creates blade material demand that dwarfs any other single geography, and domestic material supply chains for glass fibre are well established with Chinese glass fibre manufacturers Jushi, CPIC, and Taishan Fiberglass among the world's largest producers.
India is an increasingly important secondary growth market within Asia Pacific, with its National Wind-Solar Hybrid Energy Policy and ambitious renewable targets driving turbine installation at a scale that is pulling blade material demand upward. Suzlon and other domestic Indian OEMs are expanding production, while international OEMs are establishing local manufacturing to access the Indian market, bringing their advanced material specifications and supply chain relationships with them.
What Are the Recent Developments in the Advanced Wind Turbine Blade Material Market?
Q4 2024 – Vestas: Launched a recyclable wind turbine blade programme using thermoplastic resin systems across a new blade platform, partnering with chemical suppliers to establish the closed-loop end-of-life material recovery process at commercial scale for the first time.
Q4 2024 – Toray Industries: Expanded carbon fibre production capacity at its South Carolina facility specifically targeting the North American wind energy market, with the expansion underpinned by multi-year supply agreements with blade manufacturers serving the US offshore wind pipeline.
Q1 2025 – LM Wind Power: Completed manufacturing trials for a 123-metre offshore wind blade incorporating carbon fibre spar caps and a hybrid composite trailing edge, targeting deployment on next-generation 18 MW-class offshore platforms entering serial production.
Q2 2025 – Hexcel: Signed a long-term carbon fibre supply agreement with a major European blade manufacturer covering material supply for the EU offshore wind expansion programme through 2032, one of the largest single wind-sector carbon fibre contracts announced in the period.
Q2 2025 – TPI Composites: Commissioned a new blade manufacturing facility in India in partnership with a domestic wind OEM, incorporating advanced glass and carbon hybrid composite processes targeting both the Indian domestic market and potential export supply to Southeast Asia.
Q3 2025 – Owens Corning: Introduced a new high-modulus glass fibre product grade specifically optimised for wind blade shell applications on turbines in the 6-10 MW range, targeting the performance gap between standard glass and carbon fibre with a cost-competitive alternative.
About Transpire Insight
Turning Complex Data into Clear, Actionable Market Intelligence
In today’s hyper-competitive and fast-moving economy, guessing isn’t a business strategy. To lead your industry, launch game-changing products, or scale into new geographies, you need precise, reliable market intelligence, not just high-level noise.
At Transpire Insight, we are a full-service market research, data analytics, and strategic consulting firm. We help corporate leaders, innovators, and investors navigate complex market shifts with absolute confidence.
By combining rigorous primary research, deep statistical modeling, and hands-on domain expertise, we convert raw data into high-impact strategic roadmaps that drive measurable growth.
What Drives Us
Markets don’t stand still, and neither do we. Our core mission is simple: to empower organizations with verified, technology-enabled insights that remove guesswork from strategic planning.
Whether you are evaluating a niche technological shift, assessing supply chain dynamics, or looking for high-growth target segments, our intelligence gives you a decisive competitive edge.
Why Leading Enterprises Trust Transpire Insight
We don't offer one-size-fits-all research. Our analysts specialize in dedicated verticals—from Biotechnology and Semiconductors to Advanced Automotive, Clean Energy, and Industrial Manufacturing. We speak your industry's language and understand the specific nuances, regulatory shifts, and economic drivers shaping your market.
Syndicated Market Reports: In-depth, turn-key research studies covering market size, share, competitive benchmarking, and multi-year forecasts.
Customized Market Intelligence: Tailored research engagements built around your exact business questions, specific product lines, or targeted regional dynamics.
Strategic Consulting: On-demand analytical support, entry-strategy planning, and direct consultation to help you act on data with speed and accuracy.
Reliable forecasts demand ground-truth data. Our research process combines comprehensive desk research with extensive primary interviews across key industry stakeholders including C-suite executives, supply chain leaders, procurement heads, and subject matter experts. Every report undergoes strict validation to ensure maximum precision and relevance.
Our Core Sectors
We provide continuous tracking and deep-dive analytical coverage across high-impact industries:
Manufacturing and Construction
Let’s Shape Your Growth Strategy Together
Whether you are preparing for your next fiscal cycle, analyzing market entry barriers, or looking for deep-dive quantitative data, Transpire Insight is your trusted intelligence partner.
Ready to gain a clearer view of your market?
Email Us: [email protected]
Speak to Our Analyst: +91 7666513636
Want to dive deeper? Head over to www.transpireinsight.com or join our community on Twitter, LinkedIn, and Facebook for the latest updates
 [email protected]
 APAC:+91 7666513636
 Address


