Top 25 Companies in the Stretch and Shrink Films Market: Company Profile by Transpire Insight
By Transpire Insight
Description
According to a research report published by Transpire Insight, the stretch and shrink films market size is projected to grow from USD 22.23 billion in 2026 to USD 39.28 billion by 2035, at a CAGR of 7.21% during the forecast period 2027-2035. The rapid growth of e-commerce, logistics automation, the growing demand for packaged food protection, and strict regulations for transitioning to sustainable, recyclable, and ultra-thin downgauged polymer wrapping solutions are responsible for the market growth.
Introduction
The stretch and shrink films market is a critical vertical of the flexible packaging market. These films are mostly used for secondary and tertiary packaging materials and serve as load stabilizers and protectors against tampering and weather conditions for food and beverage, pharmaceutical, retail, and industrial supply chains. The industry evolves with the evolution of resin formulation, post-consumer recycled (PCR) integration, and automated application machinery that meet high-performance logistics requirements while complying with circular economy requirements around the world.
Recent Development News
- February 2026: Next-generation ultra-thin nano-layer stretch films with 30% post-consumer recycled (PCR) resin were introduced by leading manufacturers, allowing them to meet rigorous European packaging sustainability regulations without compromising on puncture resistance.
- May 2026: Key packaging manufacturers invested in new high-speed automated stretch hood production lines for North America and Asia-Pacific, meeting the increased demand from automated logistics and palletized distribution centers.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Stretch and Shrink Films Market sample report today to explore expert insights, key trends, and emerging opportunities shaping the future of the industry.
Stretch and Shrink Films Market Size & Statistics
- The Market Size for Stretch and Shrink Films Was Estimated to be Worth USD 22.23 Billion in 2026.
- The Market Size is Going to Expand at a CAGR of 7.21% between 2026 and 2035.
- The Stretch and Shrink Films Market Size is anticipated to reach USD 39.28 Billion by 2035.
- North America is projected to drive the highest demand during the forecast period, accounting for 30.2% of the stretch and shrink films market.
- Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 7.3% in the stretch and shrink films market.
Regional Growth and Demand Analysis by Transpire Insight
North America's dominance is anchored in a mature fulfillment and food-processing base that keeps upgrading rather than expanding from scratch. The U.S. market alone crossed the $5 billion mark, driven by fulfillment centers, food processors, and industrial shippers modernizing their packaging lines. Warehouse automation is a major pull factor here — high-speed palletizers require machine-grade films engineered for consistent tension, which is steering converters toward specialized formulations rather than commodity-grade rolls. On top of this, regulatory pressure in the region is pushing manufacturers toward recycled and bio-based resins, reshaping product portfolios even as overall volume growth stays comparatively steady versus emerging markets.
Asia Pacific's rapid growth stems from expanding downstream demand rather than automation upgrades. India's food processing industry, among the largest in the world by output, is scaling fast enough to pull in significant secondary packaging volumes, while the region's expanding personal care and cosmetics sector is adding further layers of demand. China continues to anchor the region through its scale in food and beverage, pharmaceutical, and consumer goods manufacturing, and rising e-commerce penetration across India, China, and Indonesia is compounding the need for secure, cost-effective wrapping. This combination of food-sector expansion and e-commerce buildout is what keeps the region ahead of North America and Europe in growth rate, even without matching their per-unit revenue base yet.
Top 15 Trends in the Stretch and Shrink Films Market
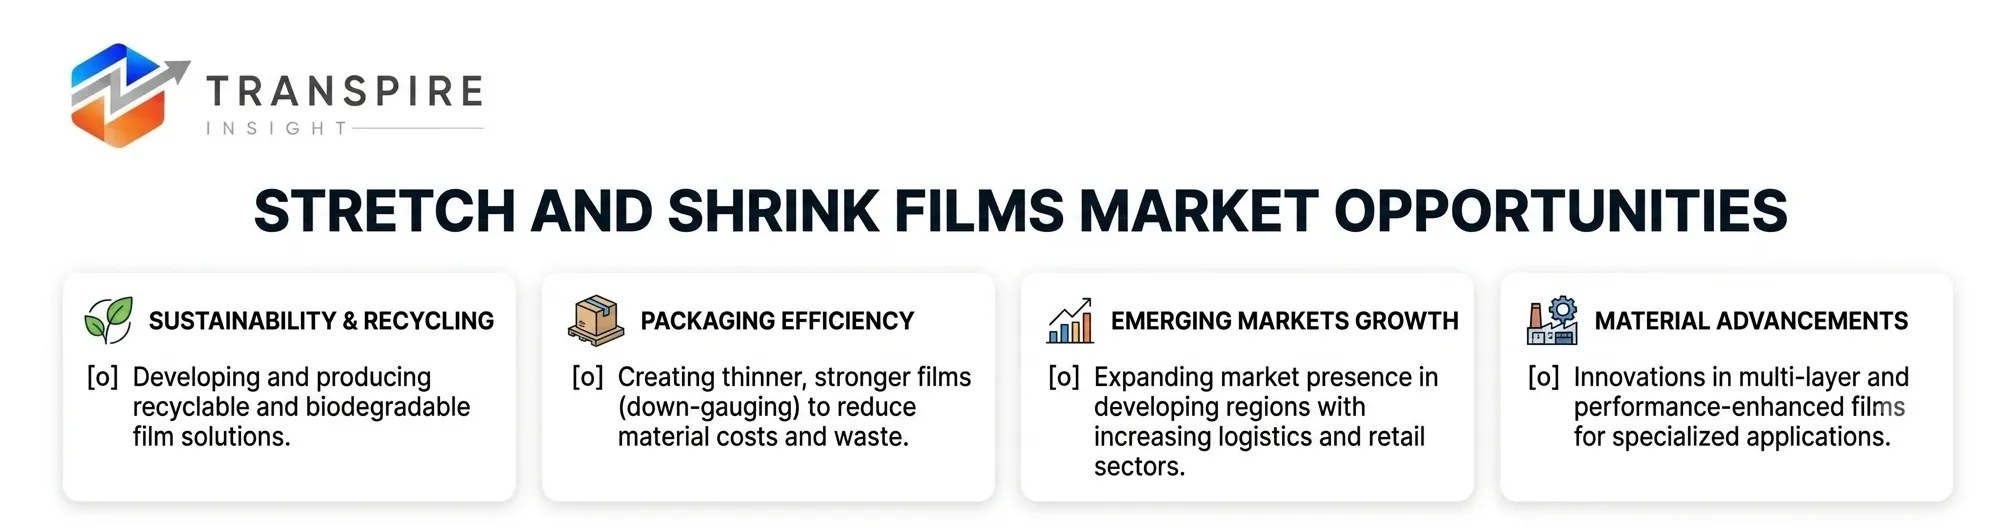
- Rising demand for post-consumer recycled content films.
- Growth of downgauged, lightweight film formulations.
- Expansion of e-commerce driving secondary packaging demand.
- Adoption of biodegradable and compostable film alternatives.
- Warehouse automation favoring machine-grade high-speed films.
- Smart packaging with embedded sensors emerging.
- Rising demand from frozen and processed foods.
- Shift toward LLDPE for pallet-holding strength.
- Growth of multi-layer nanocomposite film structures.
- Increased use in pharmaceutical secondary packaging.
- Regulatory push toward recycled and bio-based resins.
- Retail-ready multipack demand rising steadily.
- Growth in industrial load stabilization applications.
- Rising personal care and cosmetics packaging demand.
- Expanding food processing industry fueling Asia demand.
Proceed to checkout to purchase the exclusive Stretch and Shrink Films Market report and get instant access to detailed market insights, strategic analysis, and future growth opportunities.
Rising demand for post-consumer recycled content films
Brand owners are shifting toward films with higher post-consumer recycled content to meet sustainability targets, following Amcor's PCR-based shrink film certified for direct food contact.
Expansion of e-commerce driving secondary packaging demand
Rapid growth of online retail across economies is increasing demand for secure, cost-effective stretch and shrink films that protect products against damage during last-mile delivery.
Warehouse automation favoring machine-grade high-speed films
Fulfillment centers are modernizing packaging lines with high-speed palletizers, driving demand for machine-grade stretch films engineered for consistent tension and performance across automated warehouse operations.
Rising demand from frozen and processed foods
Growing consumption of frozen meat, seafood, and poultry products is boosting demand for stretch and shrink films as secondary packaging that preserves extended shelf life.
Regulatory push toward recycled and bio-based resins
Regulatory shifts across major markets are pushing converters toward recycled and bio-based resins, with sustainability compliance now shaping resin selection, film design, and procurement decisions.
Expanding food processing industry fueling Asia demand
India's expanding food processing sector, alongside China's manufacturing scale, is driving robust stretch and shrink film demand across Asia Pacific's food and packaging supply chains.
Top 25 Companies Leading the Stretch and Shrink Films Market
- Berry Inc.
- Amcor plc
- Sealed Air Corporation
- Sigma Plastics Group
- Dow Inc.
- Klöckner Pentaplast
- Paragon Films
- Coveris Holdings
- Barbier Group
- Bolloré Group
- Interpack Group
- Manuli Stretch
- DUO PLAST AG
- Eurofilms Extrusion Ltd
- Bonset America Corporation
- Hipac S.p.A.
- Atlantic Packaging
- Mima Film (ITW)
- Thong Guan Industries Berhad
- Allen Plastic Industries Co., Ltd.
- Shaktiman Packaging Pvt. Ltd.
- Millennium Packaging
- Balcan Plastics
- A-Z Packaging
- FilmSource Packaging
Customize the exclusive Stretch and Shrink Films Market report to receive insights tailored to your needs, including country-specific analysis and business-focused market intelligence.
- Berry Inc.
packaging giant delivering comprehensive flexible films across diverse industrial markets.Founded: 1967 | HQ: Evansville, Indiana, USA.Why It Ranks: Massive manufacturing scale and extensive circular polymer technology portfolio across markets.Regional Dominance: Strong leadership across North America, Europe, and expanding Asia-Pacific operations.Product Line: Polyolefin shrink films, high-performance machine stretch wraps, and custom packaging.
- Amcor plc
Pioneer in developing eco-friendly and fully recyclable barrier packaging solutions globally.Founded: 1860 | HQ: Zurich, Switzerland.Why It Ranks: Worldwide distribution network combined with cutting-edge sustainable film research and development.Regional Dominance: Dominant market presence across Western Europe, North America, and Australasia.Product Line: Recyclable shrink covers, high-clarity plastic stretch films, and specialty barriers.
- Sealed Air Corporation
Creator of iconic packaging solutions focusing on automation and product protection.Founded: 1960 | HQ: Charlotte, North Carolina, USA.Why It Ranks: Industry benchmark for automated shrink packaging machinery and protective film integration.Regional Dominance: Primary footprint in North America, with heavy penetration in European markets.Product Line: Cryovac shrink films, automated stretch wrapping materials, and protective sleeves.
- Sigma Plastics Group
Largest privately owned flexible film converter operating throughout North America.Founded: 1978 | HQ: Pompano Beach, Florida, USA.Why It Ranks: Substantial North American manufacturing capacity producing diverse industrial polyolefin packaging products.Regional Dominance: Major market control across North American industrial and commercial supply chains.Product Line: Hand stretch films, machine stretch wraps, and heavy-duty shrink hoods.
- Dow Inc.
Premier chemical materials provider offering key polyethylene resins for stretch films.Founded: 1897 | HQ: Midland, Michigan, USA.Why It Ranks: Upstream market dominance providing foundational resin technology driving film performance advancements.Regional Dominance: industrial presence spanning Americas, EMEA, and Asia-Pacific regional sectors.Product Line: LLDPE resins, bio-based polymers, and specialty materials for shrink packaging.
- Klöckner Pentaplast
Renowned leader in rigid and flexible plastic film solutions for pharmaceuticals.Founded: 1965 | HQ: Montabaur, Germany.Why It Ranks: High-precision engineering capability specializing in barrier shrink films and pharmaceutical applications.Regional Dominance: Solid operational dominance across Europe, backed by key North American sites.Product Line: PVC shrink sleeves, specialty barrier films, and rigid-flexible hybrid wraps.
- Paragon Films
Specialized manufacturer focusing exclusively on engineering extreme-performance stretch film products.Founded: 1988 | HQ: Broken Arrow, Oklahoma, USA.Why It Ranks: Renowned pioneer in downgauged stretch films that maximize load containment safety.Regional Dominance: Robust market coverage throughout North American industrial logistics and distribution hubs.Product Line: Machine stretch film, hand wrap, and ultra-thin high-containment pallet wraps.
- Coveris Holdings
European packaging powerhouse prioritizing zero-waste circular plastic packaging production solutions.Founded: 2013 | HQ: Vienna, Austria.Why It Ranks: Strong technical innovations in circular economy packaging and post-consumer recycled films.Regional Dominance: Leading strategic presence throughout Western, Central, and Eastern European regions.Product Line: Agricultural stretch wraps, collation shrink films, and industrial pallet hoods.
- Barbier Group
Major French leader manufacturing eco-designed agricultural and industrial polyethylene packaging films.Founded: 1955 | HQ: Sainte-Sigolène, France.Why It Ranks: Exceptional expertise in bio-based materials and post-consumer recycled stretch hood manufacturing.Regional Dominance: Core market leadership in France and strong distribution across Western Europe.Product Line: Stretch hoods, agricultural silage films, and recycled shrink wrap solutions.
- Bolloré Group
Key pioneer in ultra-thin, high-grade polyolefin shrink film packaging manufacturing.Founded: 1822 | HQ: Puteaux, France.Why It Ranks: World-renowned technical reputation for producing premium, thin-gauge shrink packaging materials.Regional Dominance: Widespread market authority across Europe, North America, and Asian export markets.Product Line: Bolphane polyolefin shrink films, recyclable shrink wraps, and display packaging.
Schedule a meeting with our market experts to discuss the exclusive Stretch and Shrink Films Market report and find the right research solution for your business.
Conclusion
However, the market is changing structurally due to the growth of e-commerce, automated logistics, and tougher sustainability requirements for the stretch and shrink films. Bulk materials with nano-layer extrusion, downgauging and post-consumer resin, as well as other new materials, are now being prioritized by industry leaders to offset lower environmental impacts against load stability. New regional regulations are becoming stricter, and such companies that are able to integrate high-performance material durability with the concept of the circular economy will keep enjoying a competitive advantage in packaging networks for the long term.



 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


