
Oct 26, 2026
By Transpire Insight
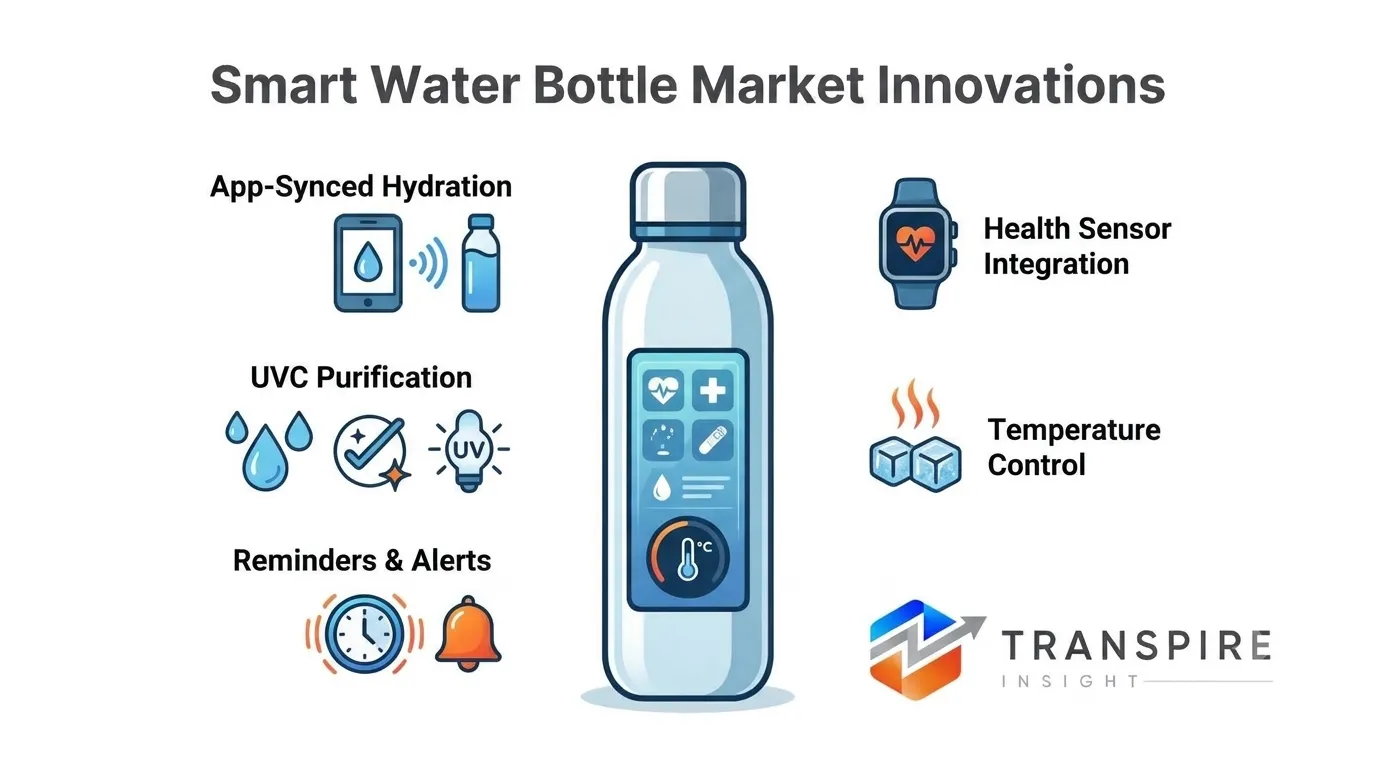
Description
According to a research report published by Transpire Insight, the global smart water bottle market size is projected to grow from USD 3.60 billion in 2026 to USD 8.44 billion by 2035, at a CAGR of 20.17% during the forecast period 2026-2035. This is due to increasing health awareness around the world, the growing importance of consumers being aware of their optimal daily water intake, and the increasing integration with fitness ecosystems. Moreover, as the demand for sustainable and reusable alternatives to single-use plastic surges, the adoption of smart bottles across the globe is being significantly driven by their rapid consumer uptake.
Introduction
The smart water bottle market is growing at a rapid pace, driven by consumers' concern with personalized wellness and smart hydration. The forward-thinking designs include built-in sensors, Bluetooth capabilities, and LED-lit reminders to monitor daily water consumption and seamlessly connect to fitness apps. Smart bottles have evolved from being a niche product to a mainstream necessity due to the growing consumer desire for health and wellness and the proliferation of wearable technology. These eco-friendly devices not only help you to avoid dehydration but also promote overall sustainability by optimizing hydration levels as you go.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic global market.
Download the exclusive Smart Water Bottle Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Smart Water Bottle Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
North America is expected to remain the dominant region during the forecast period in the smart water bottle market. The dominant position of North America in the smart water bottle market is owing to high smartphone penetration and the presence of well-established smart bottle brands, which support premium and mid-range product adoption and technology integration. The United States is currently the largest contributor to the smart water bottle market, considering factors such as strong consumer awareness of health and hydration, early adoption of connected fitness technologies and wearable devices, and a well-established digital health ecosystem with widespread use of apps such as Fitbit and Apple Health. As of 2026, several U.S.-based smart bottle brands have expanded integration with smartwatches and fitness platforms, with around 70 percent of bottles sold in the U.S. including app connectivity and 28 percent integrating directly with smartwatches, reflecting continued convergence between hydration tracking and broader digital health ecosystems.
Asia-Pacific is anticipated to witness the fastest growth during the forecast period in the smart water bottle market. This accelerated growth is expected due to rapid urbanization, rising disposable income, and increasing smartphone penetration, along with government initiatives promoting digitalization and health awareness. China, India, Japan, and South Korea are among the fastest-growing countries in the region, with rising urban populations and growing health awareness driving demand for mid-range Bluetooth-enabled, app-connected, and sensor-based hydration tracking bottles. In 2026, regional manufacturers will continue to expand affordable, mid-range product lines through local e-commerce channels, aimed at capturing the growing base of fitness-conscious urban consumers across the region.
Top 15 Trends in the Smart Water Bottle Market
Proceed to Checkout to purchase the exclusive Smart Water Bottle Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
AI-driven Personalized Hydration Insights and Coaching
Integration with health apps and AI-driven hydration tracking is replacing basic portability technology, offering consumers personalized hydration insights tailored to their needs.
UV-C Self-Cleaning and Sterilization Technology Adoption
AQUA VAULT's PureX self-cleaning bottle demonstrated strong six-month market success, underlining rising consumer interest in advanced purification and hygiene-centric hydration innovations.
Wearable and Fitness Tracker Ecosystem Integration
Growing adoption of wearable technology among millennials and Gen Z is prompting companies to launch bottles integrated with platforms like Fitbit and Apple Health.
Stainless Steel Bottles Dominating Premium Value Growth
In 2026, stainless steel and smart hydration products are expected to dominate value growth rather than low-cost plastic bottles, especially in North America and Europe.
Corporate Gifting Emerging as High-Margin Channel
Corporate gifting has expanded this market channel, with businesses using smart water bottles as premium employee and client gifts that boost engagement with wellness-focused audiences.
Digital Health Ecosystem and Apple Health Integration: Rising integration of smart hydration with digital health ecosystems is an emerging trend, as consumers increasingly rely on mobile apps and devices to track wellness metrics.
Top 25 Companies Leading the Smart Water Bottle Market
Customize the exclusive Smart Water Bottle Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
Top 10 Companies Leading the Clinical Trials Management System Market
1. Medidata Solutions
This enterprise simplifies complex clinical trial workflows for global life sciences developers.
Founded: 1999 | HQ: New York, USA.
Why It Ranks: Superior cloud infrastructure elevates its standing among elite digital healthcare systems providers.
Regional Dominance: Broad commercial operations maintain massive market capitalization across lucrative North American territories.
Product Line: Specialized database modules optimize critical patient randomization alongside electronic data capture procedures.
2. Oracle Corporation
The technology titan provides robust enterprise databases protecting vital healthcare development information.
Founded: 1977 | HQ: Austin, Texas, USA.
Why It Ranks: Scalable computing capabilities allow this organization to anchor critical global research initiatives.
Regional Dominance: Deep technical integration establishes unmatched corporate influence throughout major worldwide commercial hubs.
Product Line: Comprehensive database suites deliver integrated environments handling vast pharmaceutical validation streams effortlessly.
3. Veeva Systems
This cloud provider designs dedicated content management solutions for modern life sciences.
Founded: 2007 | HQ: Pleasanton, California, USA.
Why It Ranks: Unifying operations within single cloud architectures provides unparalleled collaborative research environments.
Regional Dominance: Expanding software deployment captures considerable market revenue throughout advanced Western European economies.
Product Line: Modern operational applications streamline regulatory compliance files alongside active investigator site communications.
4. IQVIA Inc.
Advanced analytics and human data science expertise accelerate global clinical deployment strategies.
Founded: 1982 | HQ: Durham, North Carolina, USA.
Why It Ranks: Massive real-world data assets yield unparalleled insights for complex medical investigations.
Regional Dominance: Global operational footprints command significant market share within established and emerging markets.
Product Line: Intelligent tracking platforms optimize patient recruitment metrics across connected clinical research networks.
5. Dassault Systèmes
Virtual twin experiences model human biology to revolutionize modern therapeutic development frameworks.
Founded: 1981 | HQ: Vélizy-Villacoublay, France.
Why It Ranks: Pioneering scientific simulation software introduces advanced digital execution capabilities to laboratory environments.
Regional Dominance: Core industrial software partnerships secure undisputed market leadership across major European nations.
Product Line: Advanced biosimulation applications model compound reactions alongside detailed patient virtual twin simulations.
6. Parexel International
This premier contract organization guides pharmaceutical compounds from conceptualization through commercialization.
Founded: 1982 | HQ: Newton, Massachusetts, USA.
Why It Ranks: Decades of functional regulatory experience ensure efficient execution across highly challenging trials.
Regional Dominance: Widespread multinational clinical sites maintain comprehensive therapeutic oversight across multiple geographic zones.
Product Line: Full lifecycle management services integrate specialized medical writing with clinical monitoring solutions.
7. IBM Watson Health
Cognitive computing models apply artificial intelligence paradigms to optimize massive patient datasets.
Founded: 2015 | HQ: Cambridge, Massachusetts, USA.
Why It Ranks: Revolutionary automated data processing frameworks accelerate deep analytical discoveries within healthcare.
Regional Dominance: Established technology footprints anchor data modernization initiatives inside major American hospital chains.
Product Line: Analytical health platforms synthesize unstructured clinical records alongside active patient monitoring statistics.
8. Clario
The enterprise merges scientific expertise with absolute endpoint collection accuracy across trials.
Founded: 1972 | HQ: Philadelphia, Pennsylvania, USA.
Why It Ranks: Rich historical expertise guarantees reliable digital outcome generation during complex pharmaceutical evaluations.
Regional Dominance: Trusted operational excellence commands high utilization ratios throughout prominent international research centers.
Product Line: Specialized medical devices capture accurate cardiac metrics alongside detailed respiratory patient data.
9. Revvity
Innovative diagnostic technologies empower global researchers to unlock deep translational medical insights.
Founded: 1947 | HQ: Waltham, Massachusetts, USA.
Why It Ranks: Cutting-edge biological analysis instruments secure its position among vital laboratory developers.
Regional Dominance: Expansive corporate logistics pipelines satisfy growing scientific infrastructure requirements throughout Asia Pacific.
Product Line: Advanced genomic sequencing assays isolate critical disease markers alongside automated cellular imaging.
10. WCG Clinical
The organization specializes in institutional review services, ensuring absolute ethical trial compliance.
Founded: 1968 | HQ: Princeton, New Jersey, USA.
Why It Ranks: Unmatched oversight quality dramatically accelerates initial startup timelines for complex operations.
Regional Dominance: Extensive institutional networks dominate regulatory safety compliance across major North American research.
Product Line: Comprehensive oversight solutions optimize human subject protections alongside institutional review board administration.
Schedule a meeting with our market experts to discuss the exclusive Smart Water Bottle Market report and identify the best research solution for your organization.
Conclusion
The smart water bottle market is a significant step towards personalised well-being, seamlessly merging active lifestyle with IoT innovation. The cost-effectiveness and battery life of these sensors will continue to improve throughout 2026, integrating them into health and fitness environments. Looking forward, continued advancements in fluid analysis, as well as advanced features for applications, will keep driving consumer adoption and support long-term growth in automated hydration monitoring, which will become a key health benchmark.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


