
Aug 14, 2026
By Transpire Insight
Description
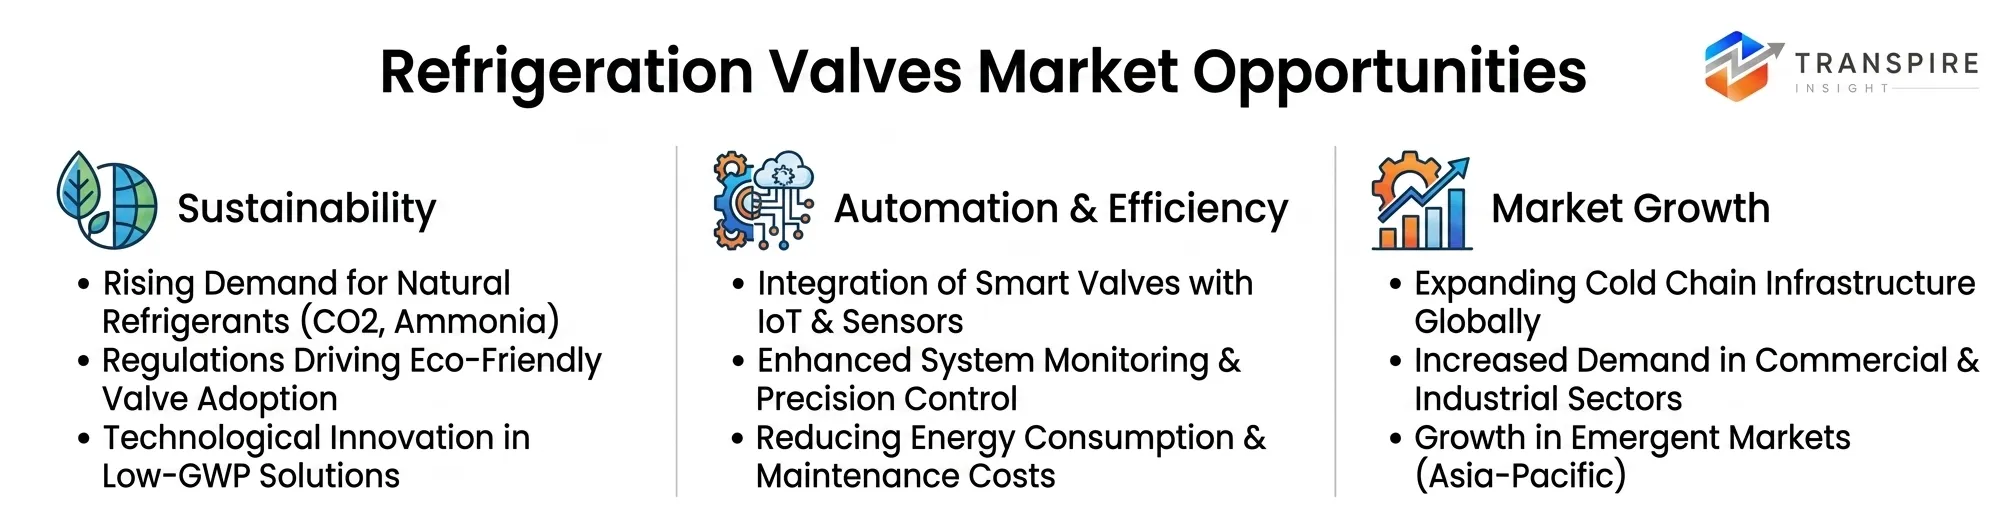
According to a research report published by Transpire Insight, the refrigeration valve market size is projected to grow from USD 8350.4 million in 2026 to USD 12,876.7 million by 2035, at a CAGR of 6.3% during the forecast period 2026-2035. The growing demand for cold chain infrastructure for food and medicine in the market is a key driver. Furthermore, there will be a shift to low Warming Potential (GWP) natural refrigerants as a result of compliance with strict environmental regulations, which will necessitate a switch to high-pressure, corrosion-resistant valve retrofits.
Introduction
The refrigeration valve market serves as a vital part of fluid flow control, refrigeration temperature control, and system efficiency management within cooling systems used for various commercial, industrial, and transport applications. High-precision electronic and mechanical valves are increasingly essential components in the context of accelerating urbanisation, changing food supply chains, and new regulations for low GWP refrigerants. The introduction of key technologies, like electronic expansion valves, solenoid shut-off systems, and high-pressure check valves, is improving the energy efficiency and operational safety of this market, making it one of the most important enablers of modern sustainable cooling ecosystems around the world.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Refrigeration Valves Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Refrigeration Valves Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight:
Asia-Pacific leads refrigeration valve demand and is also the fastest-growing region, anchored by China, Japan, South Korea, and India, where urbanization, rising middle-class spending on packaged and processed foods, and intensifying pharmaceutical cold-chain investment are accelerating adoption. Chemical and petrochemical sectors alone account for 54% of regional valve demand, reflecting the region's dual role as both a manufacturing base and end-use market. Government initiatives promoting food-waste reduction and energy-efficiency standards across China, Japan, and South Korea are reinforcing demand for next-generation valve technologies, while Asian component foundries are shifting capacity toward brass and stainless-steel valve bodies for transcritical CO2 systems, positioning the region as the center of both production and innovation. Distribution is increasingly shaped by Kigali Amendment retrofit deadlines, which are pushing domestic OEMs and international suppliers to compete for retrofit contracts across the industrial refrigeration corridor.
North America ranks as the second-largest regional market, holding an estimated 27.4% share of the refrigeration valve market, supported by the United States' highly developed food retail sector, extensive cold storage warehouse network, and world-leading pharmaceutical cold-chain requirements. The U.S. grocery retail industry, valued at over $900 billion annually, relies on advanced multi-evaporator commercial refrigeration systems that demand high volumes of solenoid and expansion valves. Growth in the region is steadier than in Asia-Pacific, with demand concentrated on replacement and upgrade cycles as mature markets like North America focus on upgrading current systems with energy-efficient valves to meet stringent regulations and corporate sustainability goals rather than new capacity additions. The mandatory transition to low-GWP refrigerants under the Kigali Amendment and EU F-Gas-style regulations is steering U.S. manufacturers and installers toward next-generation valve specifications, keeping regional growth durable even as the market matures.
Top 15 Trends in the Refrigeration Valves Market
Proceed to Checkout to purchase the exclusive Refrigeration Valves Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
List of Top 25 Companies Leading the Refrigeration Valves Market
Customize the exclusive Refrigeration Valves Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Danfoss A/S
Danfoss sets standards in high-efficiency expansion and solenoid valve technology.
Founded: 1933 | HQ: Nordborg, Denmark.
Why It Ranks: Unrivaled market share in green natural refrigerant valve innovations worldwide.
Regional Dominance: Strong presence across Europe, North America, and Asia-Pacific market sectors.
Product Line: Electric expansion valves, solenoid valves, check valves, pressure regulators.
2. Emerson Electric Co.
Emerson excels in integrating digital intelligence and control into HVACR valve systems.
Founded: 1890 | HQ: St. Louis, Missouri, USA.
Why It Ranks: Dominates modern enterprise cooling through comprehensive digital control systems integration.
Regional Dominance: Enormous market penetration throughout North American and European industrial hubs.
Product Line: Thermal expansion valves, solenoid valves, system protectors, ball valves.
3. Parker Hannifin Corporation
Parker delivers ultra-reliable motion and control valve products across extreme environments.
Founded: 1917 | HQ: Cleveland, Ohio, USA.
Why It Ranks: Industry-leading engineering capability in rugged industrial pressure and flow solutions.
Regional Dominance: Deep footprint in North America with extensive distribution networks.
Product Line: Refrigerant shut-off valves, pressure regulators, solenoid valves, check valves.
4. Sporlan (Division of Parker Hannifin)
Sporlan manufactures gold-standard HVACR flow controls trusted by technicians globally.
Founded: 1947 | HQ: Washington, Missouri, USA
Why It Ranks: Benchmark reputation for precision thermal expansion and fluid filter-drier technologies.
Regional Dominance: Primary market stronghold across North American commercial refrigeration maintenance networks.
Product Line: Catch-All filter-driers, thermostatic expansion valves, electronic valves, solenoid valves.
5. CAREL INDUSTRIES S.p.A.
CAREL drives advanced electronic control systems for sustainable commercial cooling applications.
Founded: 1973 | HQ: Brugine, Italy.
Why It Ranks: Pioneering developer of high-efficiency electronic expansion valves for $\text{CO}_2$ systems.
Regional Dominance: Heavy operational focus and leadership position across Western European markets.
Product Line: ExV electronic expansion valves, drivers, programmable controllers, water treatment.
6. Sanhua Holding Group Co., Ltd.
Sanhua dominates high-volume production of cost-effective HVACR components and controls globally.
Founded: 1984 | HQ: Xinchang, China.
Why It Ranks: World’s largest volume manufacturer of residential and commercial micro-channel components.
Regional Dominance: Unmatched manufacturing scale and distribution coverage across the Asia-Pacific region.
Product Line: Four-way reversing valves, service valves, expansion valves, solenoid valves.
7. Castel S.r.l.
Castel delivers specialized Italian precision engineering for commercial refrigeration fluid networks.
Founded: 1961 | HQ: Pessano con Bornago, Italy.
Why It Ranks: Renowned quality for safety components rated for high-pressure natural refrigerants.
Regional Dominance: Well-established distribution and service channels across European and South American markets.
Product Line: Hermetic solenoid valves, safety valves, ball valves, indicator sight glasses.
8. Hansen Technologies (A&D Company)
Hansen specializes in heavy-duty industrial refrigeration control and safety valve solutions.
Founded: 1920 | HQ: Burr Ridge, Illinois, USA.
Why It Ranks: Preferred brand for large-scale industrial ammonia system safety components.
Regional Dominance: Widespread footprint across North America, Australia, and European industrial facilities.
Product Line: Auto-purgers, pressure regulators, shut-off valves, liquid level controls.
9. Henry Technologies Inc.
Henry designs high-integrity flow control and safety valves for industrial systems.
Founded: 1914 | HQ: Chatham, Illinois, USA.
Why It Ranks: Centuries-old legacy in pressure vessel accessories and safety relief products.
Regional Dominance: Sustained commercial strength across North America and the United Kingdom regions.
Product Line: Relief valves, globe valves, check valves, oil management systems.
10. SAGINOMIYA SEISAKUSHO, INC.
Saginomiya produces ultra-precise automatic control valves for severe industrial operating conditions.
Founded: 1948 | HQ: Tokyo, Japan.
Why It Ranks: Gold standard Japanese precision engineering for pressure switches and expansion devices.
Regional Dominance: Strong market leadership across Asian markets and growing European presence.
Product Line: Temperature controls, pressure controls, automatic expansion valves, motor valves.
Schedule a meeting with our market experts to discuss the exclusive Refrigeration Valves Market report and identify the best research solution for your organization.
Conclusion
With technological progress and sustainability requirements converging, the refrigeration valves market is at a pivotal moment. Market leaders are quickly moving away from mechanical, non-smart valve designs and developing smart, sensor-based, high-pressure-compatible valve architectures. With a growing international cold chain, pharmaceutical logistics industry, and the strict eco-friendly refrigerant change, these market leaders are poised for sustainable growth. At the end of the day, it's the manufacturers who can create and integrate digital processes, make eco-friendly components, and design them to last who will shape the future of the industry.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


