
Sep 08, 2026
By Transpire Insight
Description
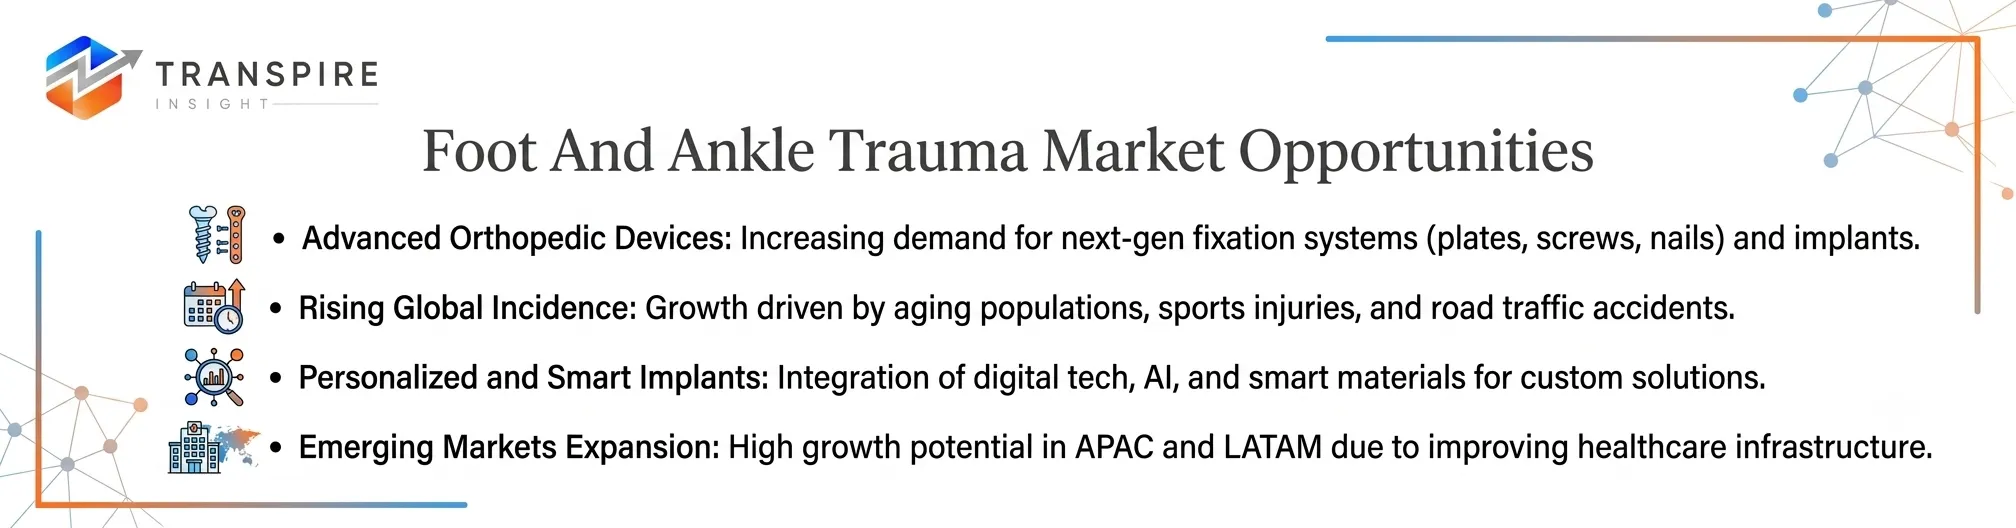
According to a research report published by Transpire Insight, the foot and ankle trauma market size is projected to grow from USD 5.60 billion in 2026 to USD 9.40 billion by 2035, at a CAGR of 8.12% during the forecast period 2027-2035. Foot and ankle trauma rises with age, sport injuries, and road traffic collisions. Growth in the use of minimally invasive procedures and the use of advanced titanium/bioabsorbable implants help drive demand for efficient fracture fixation tools.
Introduction
The foot and ankle trauma market includes specialized surgical hardware, such as plating systems, screws, intramedullary nails, and bioabsorbable implants used to treat complicated fractures of the lower limb. This is due to an increase in high-impact trauma, diabetic complications, and active lifestyles. The leading medical technology manufacturers keep breaking ground with patient-specific 3D printing and minimally invasive instrumentation.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Foot And Ankle Trauma Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
North America continues to lead the foot and ankle trauma market, underpinned by high fracture incidence, extensive sports participation, and early adoption of minimally invasive fixation techniques across leading U.S. and Canadian orthopedic centers. Strong reimbursement frameworks and dense trauma-center networks have made the region a proving ground for next-generation devices; DePuy Synthes' rollout of its TriLEAP Lower Extremity Anatomic Plating System, featuring low-profile titanium plates for forefoot and midfoot procedures, illustrates how device makers keep refining trauma-specific portfolios for this market. Growing consolidation, exemplified by Zimmer Biomet folding lower-extremity specialist Paragon 28 into its ankle trauma business, further signals confidence in sustained regional demand as hospitals expand outpatient and specialty orthopedic capacity.
Asia Pacific is emerging as the fastest-growing regional market, propelled by expanding healthcare infrastructure, rising road-traffic and sports-related injuries, and growing disposable incomes across China, India, and Southeast Asia. Device makers are actively building a foothold in the region, as seen in Zimmer Biomet's acquisition of OSSIS, a specialist in customized 3D-printed implants, extending its reach into complex trauma reconstruction beyond its established Western markets. Rising surgeon training programs, distributor partnerships, and gradual regulatory harmonization are helping close the adoption gap with North America and Europe, while urbanization and an aging population continue to widen the region's long-term demand base for advanced fixation and regenerative trauma solutions.
Top 15 Trends in the Foot And Ankle Trauma Market
Minimally Invasive Fixation
Surgeons increasingly favor minimally invasive fixation for ankle fractures, offering smaller incisions, reduced pain, faster recovery, and lower complication rates than traditional open surgery techniques.
Bioinductive Scaffolds
Bioinductive scaffolds and regenerative adjuncts are gaining traction, significantly speeding bone and soft-tissue healing after trauma, reducing hardware removal needs, and improving patient surgical outcomes.
3D-Printed Implants
Additive manufacturing enables patient-specific, anatomically contoured trauma implants, improving fit accuracy and surgical precision for complex fracture cases, especially in talus and calcaneus reconstruction surgeries.
Orthopedic M&A
Leading orthopedic firms acquire specialized trauma device makers to broaden portfolios, exemplified by Zimmer Biomet's purchase of Paragon 28, strengthening ankle trauma and reconstructive capabilities.
AI in Trauma Care
Artificial intelligence increasingly supports trauma care through automated fracture detection on imaging, predictive rehabilitation modeling, and surgical planning tools guiding implant selection and screw trajectories.
Asia-Pacific Expansion
Rising healthcare investment, sports participation, and disposable income are accelerating Asia-Pacific trauma device adoption, as China and India expand surgical infrastructure and minimally invasive access.
Top 25 Companies Leading the Foot And Ankle Trauma Market
1. Stryker Corporation
leader holding over 16.5% of foot/ankle device market share.
Founded: 1941 | HQ: Kalamazoo, Michigan, USA.
Why It Ranks: Dominates trauma hardware sales through extensive orthopedic distribution channels.
Regional Dominance: North America with substantial market share across Europe and Asia-Pacific.
Product Line: AxSOS plating systems, T2 intramedullary nails, ankle fracture implants.
2. DePuy Synthes (Johnson & Johnson)
Pioneer in standardized AO Foundation internal fixation trauma implants globally.
Founded: 1898 | HQ: Raynham, Massachusetts, USA.
Why It Ranks: Expansive trauma portfolio backed by immense surgeon training network infrastructure.
Regional Dominance: North America and Europe with deep market penetration everywhere.
Product Line: VA-LCP ankle plates, cannulated screws, external fixation systems.
3. Arthrex, Inc.
Privately held innovator specializing heavily in minimally invasive orthobiologics systems.
Founded: 1981 | HQ: Naples, Florida, USA.
Why It Ranks: Recognized market driver for joint preservation and soft-tissue reconstruction.
Regional Dominance: North America leading, expanding swiftly across European surgical centers.
Product Line: TightRope syndesmosis systems, mini-compression screws, bioabsorbable suture anchors.
4. Zimmer Biomet
Major musculoskeletal powerhouse serving comprehensive extremity reconstructive trauma needs.
Founded: 1927 | HQ: Warsaw, Indiana, USA.
Why It Ranks: Unmatched portfolio breadth combining total joint replacement with fracture fixation.
Regional Dominance: North America primary, followed closely by established European markets.
Product Line: ALPS foot plates, Trabecular Metal technology, ankle trauma hardware.
5. Enovis (DJO / Paragon 28 integration)
Fast-growing orthopedic pure-play focusing heavily on foot and ankle solutions.
Founded: 2006 | HQ: Wilmington, Delaware, USA.
Why It Ranks: Key top-5 player with dedicated foot and ankle focus.
Regional Dominance: North America dominating through targeted specialized surgical sales forces.
Product Line: Gorilla plating system, Baby Gorilla mini plates, Silverback ankle plating.
6. Smith & Nephew plc
British multinational renowned for advanced wound management and trauma fixations.
Founded: 1856 | HQ: Watford, United Kingdom.
Why It Ranks: Strong international presence with specialized external and internal trauma fixators.
Regional Dominance: Europe and North America with solid growth in Asia-Pacific.
Product Line: EVOS SMALL plating, Taylor Spatial Frame, TRIGEN intramedullary systems.
7. Acumed LLC
Dedicated exclusively to developing targeted extremity reconstructive and trauma products.
Founded: 1988 | HQ: Hillsboro, Oregon, USA.
Why It Ranks: Respected for anatomical design precision in foot and ankle fixations.
Regional Dominance: North America dominant with expanding footprint in Western European nations.
Product Line: Ankle fracture plating, Acutrak headless compression screws, calcaneal plates.
8. Medartis AG
Swiss precision engineering firm specialized in small bone fracture fixation systems.
Founded: 1997 | HQ: Basel, Switzerland.
Why It Ranks: High reputation for low-profile titanium plating quality in delicate surgeries.
Regional Dominance: Europe primary driver with rising market presence in North America.
Product Line: APTUS foot plating system, cannulated screws, midfoot trauma hardware.
9. CONMED Corporation
Key provider of surgical tools, arthroscopy devices, and orthopedic implants.
Founded: 1970 | HQ: Largo, Florida, USA.
Why It Ranks: Strong footprint in outpatient and ambulatory surgery center trauma procedures.
Regional Dominance: North America leading, supported by international healthcare export networks.
Product Line: Bioabsorbable screws, soft tissue anchors, lower extremity fixations.
10. Orthofix Medical Inc.
Specialized leader in spine and extremity orthopedics, bone growth therapies.
Founded: 1980 | HQ: Lewisville, Texas, USA.
Why It Ranks: Unique integration of external fixation systems with biological bone stimulation.
Regional Dominance: North America primary, followed by key European and Latin markets.
Product Line: FITBONE intramedullary nails, Galaxy external fixation systems, mini fixators.
Conclusion
The foot and ankle trauma market is seeing moderate growth as these injuries continue to increase, technology advances, and treatment approaches focus on minimally invasive surgery. Both established industry leaders and innovators who specialize in their field are driving change in patient recovery by creating 3D-printed custom implants, bioabsorbable devices, and rigid fixation devices. With healthcare infrastructure improving worldwide, the key manufacturers will keep on making strategic acquisitions and adopting research-based clinical protocols to enhance mobility, reduce postoperative complications, and cater to increasingly growing market needs.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


