
Aug 13, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the diabetic retinopathy market size is projected to grow from USD 15654 million in 2026 to USD 28471 million by 2035, at a CAGR of 9.5% during the forecast period 2026-2035. The diabetic retinopathy market is expected to grow owing to the growing prevalence of diabetes, aging population, rising diagnostic screening, and significant improvement in anti-VEGF biologic drugs. Disease detection programs and strong clinical development also help market penetration grow.
Introduction
Today, DR is the biggest preventable cause of vision loss and blindness in working-age adults worldwide. As a microvascular complication of diabetes, it will slowly cause damage to retinal blood vessels, and if not treated, can cause vision problems. Targeted anti-VEGF drugs, corticosteroid implants, laser photocoagulation, and advanced diagnostic imaging platforms are all included in the market. The market plays a significant role in preventing permanent eye damage and maintaining vision function, driven by the development of drugs at a rapid pace, AI-driven diagnostic screening, and extended-durability therapeutics.
Recent Development News
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. In-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Download the exclusive Diabetic Retinopathy Market sample report today to uncover expert insights, emerging trends, and the opportunities defining the future of the industry.
Diabetic Retinopathy Market Size & Statistics
Regional Growth and Demand Analysis by Transpire Insight
The diabetic retinopathy market is expected to see the highest demand growth in North America during the forecast period. Advanced health care facilities, prevalence of diabetes, extensive health care reimbursement coverage, and the speed of the adoption of AI-based retinal screening technology further underscore the region's dominant role. The United States is the leading player in the region, fueled by a high prevalence of diabetes, broad adoption of anti-VEGF drugs, and strong reimbursement for the treatment of retinal disease; Canada and Mexico play a supporting role by increasing access to ophthalmology services in a variety of patient populations. This scale is bolstered by high demand for intravitreal injection therapy, higher health expenditure, and broad networks of retinal specialty clinics, as well as the region's early adoption of AI-backed diagnostic imaging and integrated care coordination platforms ahead of other markets.
The Asia-Pacific diabetic retinopathy market is expected to grow at the highest rate during the forecast period. Increasingly, the rate of diabetes and the widespread roll-out of health insurance coverage, combined with increased investment in screening infrastructure in the region, are contributing to this acceleration, particularly in China and India. High underlying demand for diagnostic and treatment services is anticipated to drive the steady growth of the total demand in the Asia-Pacific region, with the screening and treatment segment expected to perform well. While the number of traditional therapies for diabetes continues to grow, the trend of more widespread utilization of anti-VEGF agents and AI tools for retinal grading is rapidly transforming care pathways as healthcare spending increases and government-led diabetes screening programs expand. Overall, this makes Asia-Pacific the growth leader of the moment, while North America holds on to the higher absolute market share.
Top 15 Trends in the Diabetic Retinopathy Market
Proceed to Checkout to purchase the exclusive Diabetic Retinopathy Market report and gain instant access to in-depth market intelligence, strategic analysis, and future growth opportunities.
AI-Assisted Retinal Imaging
Hoffmann-La Roche improved AI-supported retinal imaging integration by 31% across partnered ophthalmology diagnostic centers globally, boosting early detection accuracy and reducing screening backlogs significantly.
Anti-VEGF Intravitreal Injections
IVT therapy dominated the market with a 63% share due to growing anti-VEGF and corticosteroid injection adoption, remaining the primary treatment approach for managing diabetic retinopathy progression worldwide.
Sustained-Release Ocular Implants
Novartis expanded sustained-release ocular implant development programs, reducing projected injection frequency by 26% in retinal therapy studies, improving patient convenience and long-term treatment adherence.
Minimally Invasive Vitrectomy Advances
ThromboGenics increased investment in retinal microsurgery technologies by 19% to improve diabetic vitrectomy procedure precision and recovery outcomes, benefiting advanced-stage patients requiring surgical intervention.
Regional Distribution Capacity Expansion
Bayer increased retinal therapy distribution capacity by 24% to support growing ophthalmology clinic demand across North America and Europe, strengthening supply chains and treatment accessibility for patients.
AI-Assisted Screening Infrastructure Growth
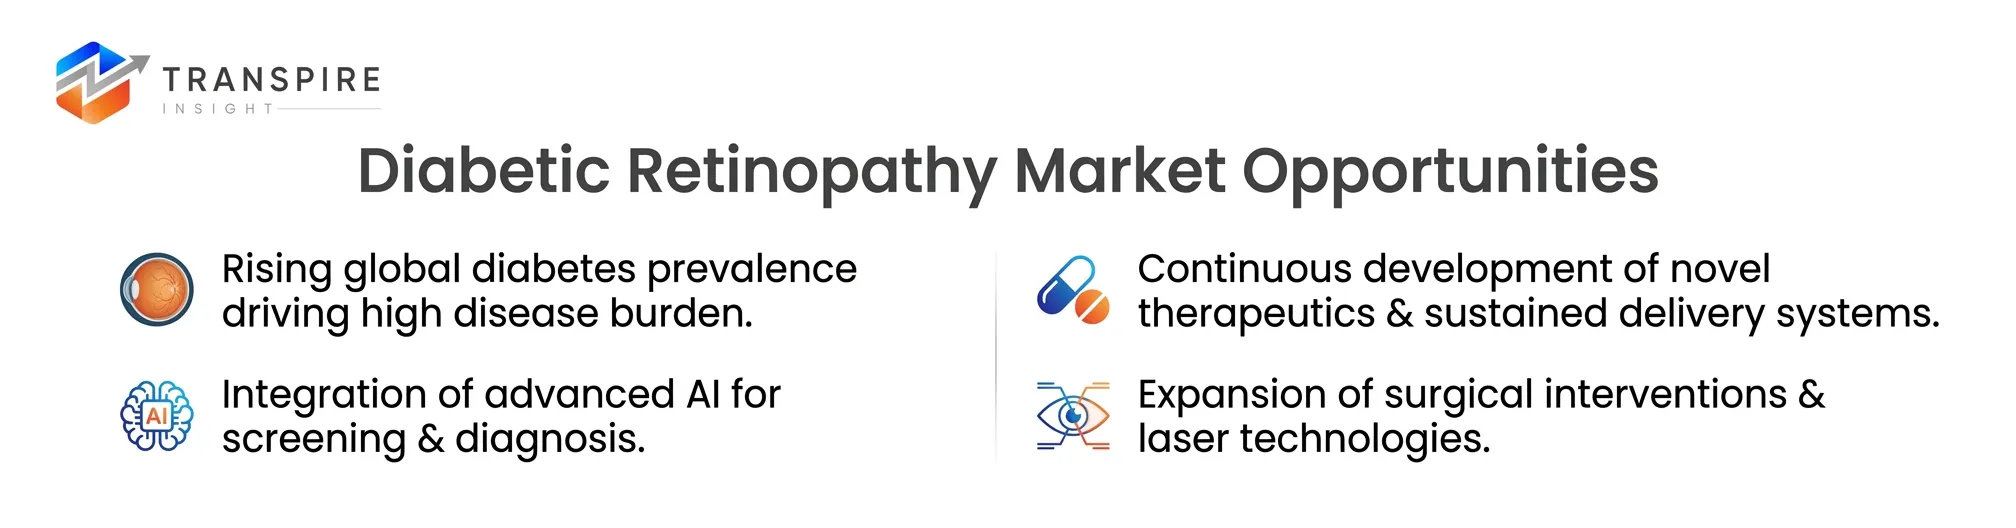
Lucrative opportunities exist in upgrading screening infrastructure with AI-assisted grading to reduce manual workload, integrating imaging and referral workflows across regional health systems, easing clinician burden and improving diagnostic throughput.
List of Top 25 Companies Leading the Diabetic Retinopathy Market
Customize the exclusive Diabetic Retinopathy Market report today to receive tailored insights, country-specific analysis, and business-focused market intelligence.
1. Regeneron Pharmaceuticals
Leading developer of gold-standard biologic therapies for retinal vascular diseases.
Founded: 1988 | HQ: Tarrytown, New York, USA.
Why It Ranks: Dominates anti-VEGF market share through flagship retinal drugs EYLEA and EYLEA HD.
Regional Dominance: Strong leadership in North America with expansive commercial presence.
Product Line: EYLEA (aflibercept injection) and EYLEA HD (high-dose aflibercept 8 mg).
2. F. Hoffmann-La Roche Ltd
healthcare leader pioneering bispecific antibodies and extended-release retinal therapeutics.
Founded: 1896 | HQ: Basel, Switzerland.
Why It Ranks: Drives innovation with dual-pathway angiopoietin-2 and VEGF-A targeted therapies.
Regional Dominance: Widespread dominance across Europe, North America, and major Asian markets.
Product Line: Vabysmo (faricimab-svoa), Lucentis (ranibizumab), and Susvimo port delivery system.
3. Novartis AG
Multinational pharmaceutical leader specializing in targeted ophthalmic solutions and advanced biologics.
Founded: 1996 | HQ: Basel, Switzerland.
Why It Ranks: Retains massive market presence through established anti-VEGF and next-generation portfolios.
Regional Dominance: Extensive market reach across the European Union and key international territories.
Product Line: Beovu (brolucizumab) and Lucentis (ranibizumab outside the United States).
4. AbbVie Inc. (Allergan)
Bio-pharmaceutical giant advancing sustained-release intravitreal implants for long-term retinal care.
Founded: 2013 | HQ: North Chicago, Illinois, USA.
Why It Ranks: Top provider of anti-inflammatory intravitreal corticosteroid implants for macular edema.
Regional Dominance: Holds leading shares across North American and Latin American markets.
Product Line: Ozurdex (dexamethasone intravitreal implant) and specialized ophthalmic solutions.
5. Bayer AG
life sciences firm co-developing and commercializing key anti-VEGF therapies worldwide.
Founded: 1863 | HQ: Leverkusen, Germany.
Why It Ranks: Commands vast international distribution of blockbuster retinal disease treatments.
Regional Dominance: Strong market leadership across Europe, Asia-Pacific, and Latin America.
Product Line: EYLEA (aflibercept, commercialized ex-US) and EYLEA HD (high-dose formulation).
6. Alimera Sciences (Part of ANI Pharmaceuticals)
Specialized pharmaceutical firm focused on long-term sustained drug delivery for retinas.
Founded: 2003 | HQ: Alpharetta, Georgia, USA.
Why It Ranks: Offers unique continuous micro-dosing corticosteroid implants lasting up to 36 months.
Regional Dominance: High penetration in the United States and strategic European clinical markets.
Product Line: ILUVIEN (fluocinolone acetonide intravitreal implant 0.19 mg).
7. Oxurion NV
Clinical-stage biopharmaceutical developer pioneering innovative non-VEGF ophthalmic therapeutic candidates.
Founded: 2006 | HQ: Leuven, Belgium.
Why It Ranks: Innovates alternative novel pathways for patients non-responsive to anti-VEGF injections.
Regional Dominance: Focuses clinical operations and research partnerships primarily in Western Europe.
Product Line: Novel therapeutic pipeline including THR-149 and THR-687 clinical programs.
8. Bausch Health Companies Inc.
Major eye health organization producing diverse surgical, diagnostic, and therapeutic solutions.
Founded: 1960 | HQ: Laval, Quebec, Canada.
Why It Ranks: Provides comprehensive eye care ranging from retinal surgery tools to therapeutics.
Regional Dominance: Strong established commercial market presence across North America and Asia.
Product Line: Macugen (pegaptanib sodium) and specialized vitreoretinal surgical instrument platforms.
9. Topcon Corporation
World leader in diagnostic imaging technology and optical instrumentation for ophthalmology.
Founded: 1932 | HQ: Tokyo, Japan.
Why It Ranks: Dominates diagnostic imaging essential for early diabetic retinopathy screening and monitoring.
Regional Dominance: Unmatched operational dominance across Asia-Pacific and expanding clinical networks.
Product Line: 3D OCT-1 Maestro, DRI OCT Triton, and automated fundus cameras.
10. Kodiak Sciences Inc.
Innovator developing novel biopolymer-conjugated therapeutics for long-acting retinal disease care.
Founded: 2009 | HQ: Palo Alto, California, USA.
Why It Ranks: Rapidly rising developer of high-durability anti-VEGF biopolymer conjugates.
Regional Dominance: Emerging presence with widespread clinical trials focused across North America.
Product Line: Zenkuda (tarcocimab tedromer) and specialized ABC platform therapeutic pipeline.
Schedule a meeting with our market experts to discuss the exclusive Diabetic Retinopathy Market report and identify the best research solution for your organization.
Conclusion
The diabetic retinopathy market is expected to grow substantially, owing to the growing prevalence of diabetes in the world and the growing importance of early intervention in the disease. The advent of long-acting anti-VEGF drugs, novel delivery methods, and AI-driven screening systems is transforming the landscape of clinical care. Despite the barriers of therapeutic pricing and inequities in healthcare access, the industry is developing new treatment strategies and medications, and some key players are offering long-term treatment plans. In conclusion, as these technologies continue to grow, along with the growing diagnostic capabilities and a growing pharmaceutical pipeline, the outcome for each patient will be enhanced, and vision loss caused by diabetes will be significantly reduced worldwide.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


