
Oct 29, 2026
By Transpire Insight
Description
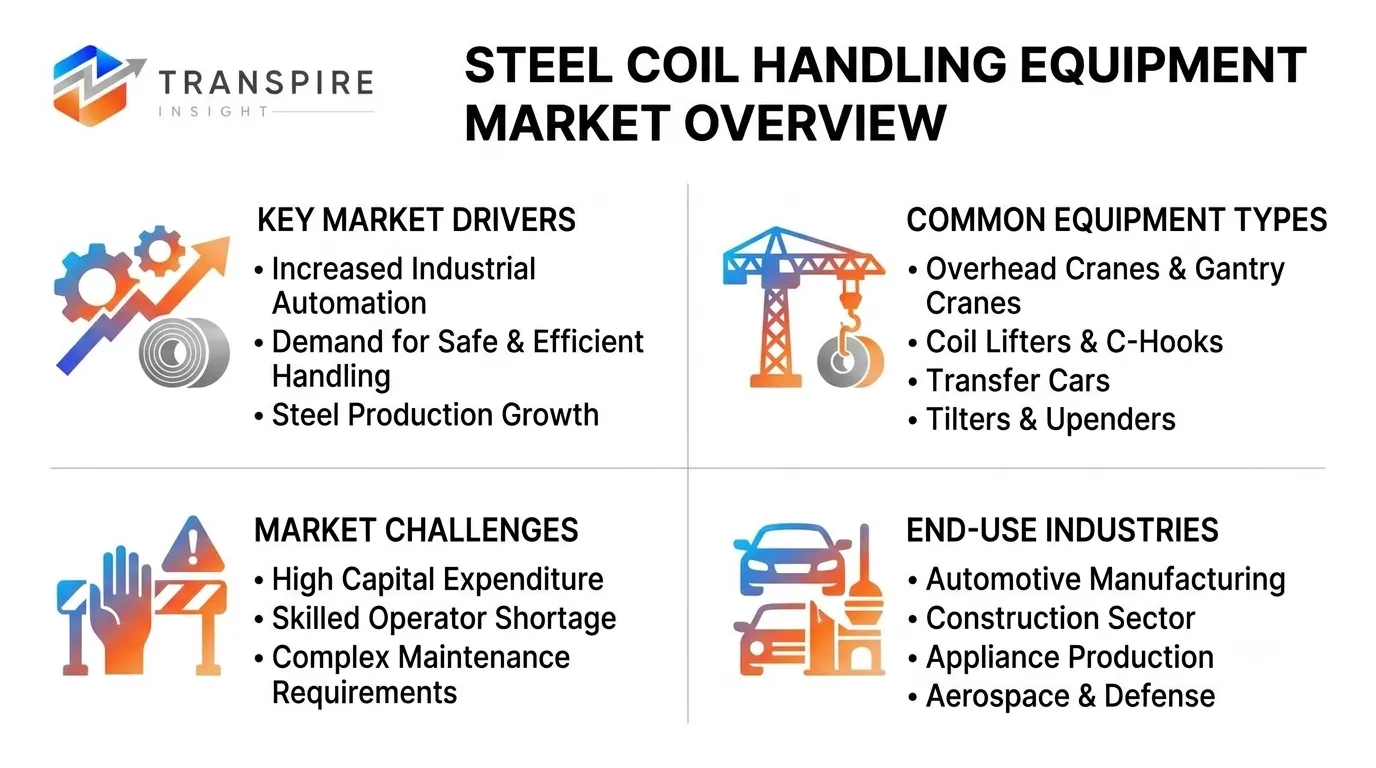
According to a research report published by Transpire Insight, the steel coil handling equipment market size is projected to grow from USD 2.32 billion in 2026 to USD 3.42 billion by 2035, at a 5.25% CAGR during the 2027-2035 forecast period. The steel coil handling equipment market is driven by expanding automated steel processing facilities, urgent workplace safety compliance, demand for damage-free coil transfer, and modernizing steel service center infrastructure globally.
Introduction
The steel coil handling equipment market plays a vital role in heavy manufacturing, logistics, and metals processing sectors. As steel output increases across automotive, construction, and infrastructure industries, heavy mills require reliable systems like specialized cranes, transfer cars, upenders, and high-bay automated storage solutions. Modern coil handling equipment minimizes material damage while enhancing workplace safety and operational throughput. Rapid industrial automation and retrofitting of legacy facilities further drive market expansion worldwide.
Recent Development News
May 2026: Steel Storage Systems was named a Top Service Center Equipment Brand for its chain-driven coil and structural metal transport solutions integrated into modern logistics operations.
June 2026: ELME Spreader launched the Coil Grabber 719G, expanding its heavy-duty attachment product line designed for efficient steel coil handling using industrial reach stackers.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, empowering companies to uncover new avenues for growth, bolster strategic decision-making, and stay ahead in a dynamic market.
Steel Coil Handling Equipment Market Size & Statistics
The Market Size for Steel Coil Handling Equipment Was Estimated to be Worth USD 2.32 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 5.25% between 2026 and 2035.
The Steel Coil Handling Equipment Market Size is anticipated to reach USD 3.42 Billion by 2035.
Asia Pacific is projected to drive the highest demand during the forecast period, accounting for 43% of the steel coil handling equipment market.
Asia Pacific is projected to grow the fastest during the forecast period at a CAGR of 6.4% in the steel coil handling equipment market.
Regional Growth and Demand Analysis by Transpire Insight
Asia Pacific leads because China, India, Japan and South Korea operate the world’s densest cluster of rolling mills, where coils must be moved, stored, and loaded continuously. Rolling mills account for about 66% of equipment demand, so regional steel output directly shapes orders for coil cars, C-hooks, lifters and upenders. Modernization projects reinforce this pull, such as SMS group’s upgrade at Tata Steel’s CSP plant in India, which optimized coil handling and throughput for coils down to 1 mm thickness. Automotive, construction, and metal processing clusters across the region further widen the installed base and keep replacement and expansion orders flowing.
Top 15 Trends in the Steel Coil Handling Equipment Market
Plants are replacing manual stacking with automated storage and retrieval systems that cut handling time, reduce coil damage, and improve floor-space use across busy mills.
Real-time sensors on cranes and coil cars track load, vibration, and wear, letting operators schedule repairs early, avoid unplanned downtime, and extend equipment service life.
Steel producers increasingly specify drives and hoists that consume less power, helping 3. plants meet sustainability targets while lowering operating costs over the long equipment lifecycle.
Rising liability costs and stricter workplace rules push mills to retire outdated manual equipment and install safer lifters and transfer systems protecting operators and coils.
Upgrades at existing rolling mills for higher throughput and thinner-gauge output require compatible coil cars and cranes, sustaining steady orders from the largest application segment.
Smaller and mid-sized plants favor semi-automatic systems because lower upfront cost, simpler installation, and operational flexibility outweigh full automation, keeping manual and semi-automatic equipment dominant.
List of Top 25 Companies Leading the Steel Coil Handling Equipment Market
List of Top 10 Companies Leading the Steel Coil Handling Equipment Market
1. Konecranes
leader in heavy-duty industrial cranes and automated coil handling systems.
Founded: 1994 | HQ: Hyvinkaa, Finland.
Why It Ranks: Market leadership in high-capacity smart lifting solutions and safety-centric software integrations.
Regional Dominance: Strong market leadership across Europe, North America, and Asia-Pacific industrial sectors.
Product Line: Overhead coil cranes, grab lifters, automated transfer cars, and hoists.
2. SMS group (AMOVA)
Industry pioneer delivering fully automated high-bay warehouses and integrated coil transport systems.
Founded: 1871 | HQ: Düsseldorf, Germany.
Why It Ranks: Unrivaled engineering expertise in end-to-end heavy metals logistics and mill automation.
Regional Dominance: Dominates European steel mills and expanding modern metal facilities globally.
Product Line: High-bay coil storage, automatic coil transfer vehicles, and warehouse software.
3. Primetals Technologies
World-class provider of full-lifecycle metallurgical plant automation and handling infrastructure.
Founded: 2015 | HQ: London, United Kingdom.
Why It Ranks: Advanced integration of digital plant software with robust coil transport solutions.
Regional Dominance: footprint with massive presence across Asian and European steelmakers.
Product Line: Coil tilters, automated guided vehicles, coil conveyors, and strapping lines.
4. ANDRITZ AG
Major technology vendor offering heavy metal processing and automated coil management.
Founded: 1852 | HQ: Graz, Austria.
Why It Ranks: engineering presence with complete line integration capabilities for coil handling.
Regional Dominance: Europe and North America heavy industrial and steel processing facility market.
Product Line: Coil handling systems, slitting lines, cut-to-length equipment, and upenders.
5. Fives Group
International engineering group designing high-precision industrial handling and processing machinery.
Founded: 1812 | HQ: Paris, France.
Why It Ranks: Centuries of innovation offering customized, high-throughput heavy equipment for steel processing.
Regional Dominance: Strong presence across Western Europe, the Americas, and Asia-Pacific.
Product Line: Heavy coil logistics systems, coil cars, high-speed slitting lines, and stackers.
6. Red Bud Industries
Top manufacturer of coil processing equipment and heavy-duty coil handling machinery.
Founded: 1959 | HQ: Red Bud, Illinois, USA.
Why It Ranks: Industry-standard processing lines paired with reliable automated heavy coil staging systems.
Regional Dominance: Dominates North American steel service centers and metal fabrication facilities.
Product Line: Heavy coil staging tables, upenders, coil cars, and turnstiles.
7. ARKU Maschinenbau GmbH
Market specialist in high-precision coil processing, leveling, and automated material handling.
Founded: 1928 | HQ: Baden-Baden, Germany.
Why It Ranks: Recognized leader in high-precision levelling technology combined with automated coil handling.
Regional Dominance: Deep market penetration across Germany, broader Europe, and North America.
Product Line: Precision levelers, coil feeding lines, decoilers, and material handling systems.
8. Heinrich Georg GmbH
Premier manufacturer of advanced finishing lines and customized heavy coil equipment.
Founded: 1948 | HQ: Kreuztal, Germany.
Why It Ranks: High reputation for engineering customized, ultra-precise continuous coil handling solutions.
Regional Dominance: Strong international footprint, particularly in European and Asian steel mills.
Product Line: Slitting lines, coil handling cars, cut-to-length lines, and decoiling units.
9. Bradbury Group
manufacturer of roll forming systems and automated coil handling lines.
Founded: 1959 | HQ: Moundridge, Kansas, USA.
Why It Ranks: Comprehensive portfolio covering complete coil processing and material movement integration.
Regional Dominance: Strong leader in the Americas with widespread worldwide export operations.
Product Line: Uncoilers, coil cars, upenders, turnstiles, and automated coil storage.
10. Hubbell Industrial Controls
Specializes in heavy-duty magnetics and electrical controls for steel coil handling.
Founded: 1888 | HQ: Shelton, Connecticut, USA.
Why It Ranks: Essential hardware supplier of high-capacity magnetic lifting systems for steel coils.
Regional Dominance: North American industrial lifting market with heavy-industry exports.
Product Line: Coil lifting magnets, lifting tongs, controllers, and safety brake systems.
Conclusion
The steel coil handling equipment market is undergoing steady growth, driven by plant automation, strict workplace safety regulations, and modernized metal logistics. Top manufacturers are increasingly blending heavy-duty mechanical lifters with intelligent software, automated transport vehicles, and high-bay storage to optimize mill throughput. As steel consumption rises, suppliers focusing on damage prevention, smart integration, and custom handling systems will maintain strong competitive edges.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


