
Oct 13, 2026
By Transpire Insight
Description
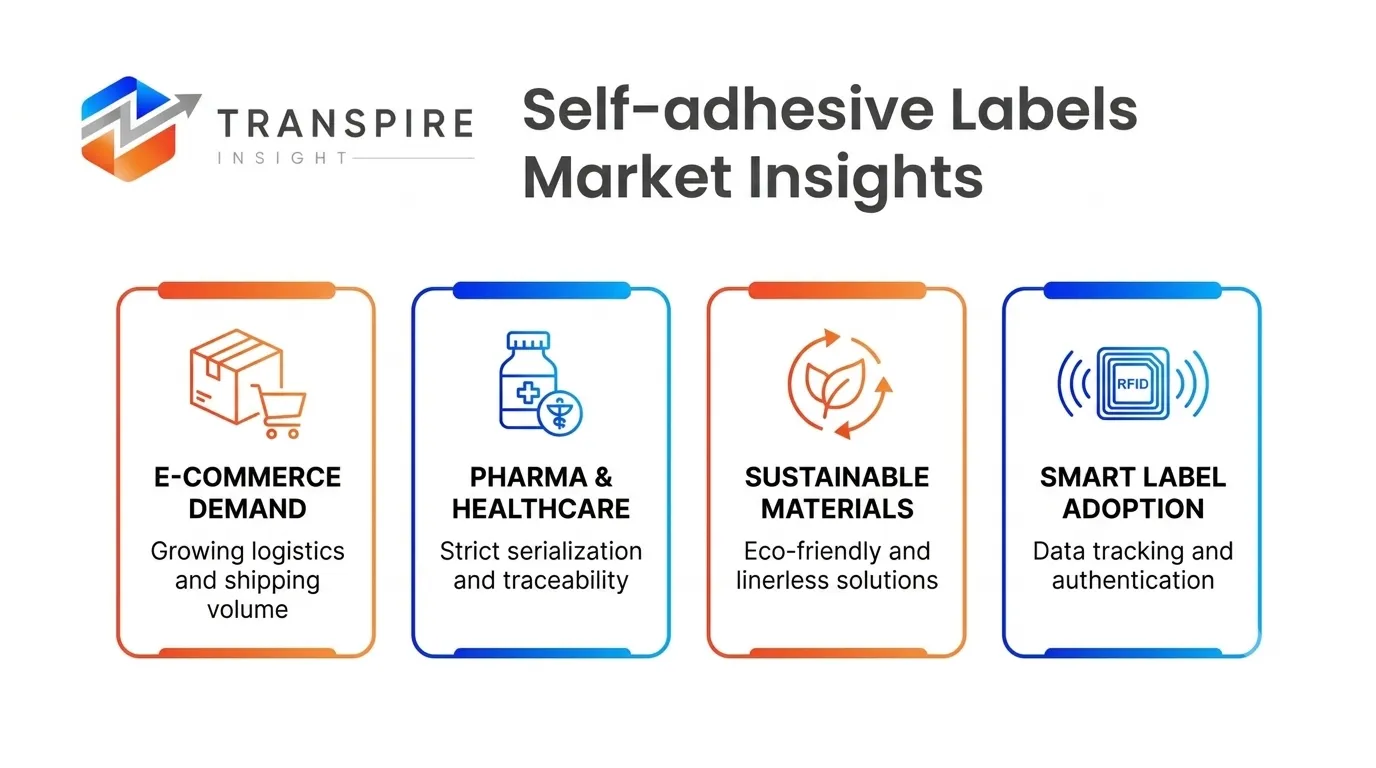
According to a research report published by Transpire Insight, the Self-adhesive Labels Market size is projected to grow from USD 57440.5 million in 2026 to USD 85818.4 million by 2035, at a CAGR of 6.12% during the forecast period 2027-2035. Rapid e-commerce growth, expanding pharmaceutical packaging needs, rising demand for logistics tracking, and increasing consumer preference for sustainable, eco-friendly, and linerless pressure-sensitive label formats drive market expansion.
Introduction
The self-adhesive labels market is experiencing robust growth driven by advancements in food, beverage, pharmaceutical, and retail packaging. These pressure-sensitive labels eliminate the need for heat or water activation, streamlining high-speed automated application lines. As brand security, variable data tracking, and sustainable materials become essential for supply chains, leading manufacturers are adopting innovative adhesives, linerless options, and digital printing technologies to meet strict environmental and regulatory standards.
Recent Development News
May 2026: Leading label material innovators expanded production lines dedicated to recyclable, bio-based facestocks and wash-off pressure-sensitive adhesives to support circular plastic recycling initiatives across Europe and North America.
August 2026: Major converting machinery manufacturers introduced next-generation, high-speed automated applicators specifically designed to process linerless self-adhesive labels, addressing previous operational bottlenecks in logistics hubs.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Self-adhesive Labels Market Size & Statistics
The Market Size for Self-adhesive Labels Was Estimated to be Worth USD 57440.5 Million in 2026.
The Market Size is Going to Expand at a CAGR of 6.12% between 2026 and 2035.
The Self-adhesive Labels Size is anticipated to reach USD 85818.4 Million by 2035.
Asia-Pacific is projected to drive the highest demand during the forecast period, accounting for 39% of the self-adhesive labels market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 6.17% in the self-adhesive labels market.
Regional Growth and Demand Analysis by Transpire Insight
Asia-Pacific anchors demand because China and India combine large manufacturing bases with fast-growing packaged food, personal care and pharmaceutical consumption. Urbanization and rising disposable incomes are pushing more products through modern retail and online channels, and each of them needs information, pricing, and regulatory labels. In China, the surge in microwave meals has lifted demand for SIS hot-melt labels built to survive reheating, while booming e-commerce parcel flows are raising uptake of durable, variable-data shipping labels. Tightening product safety and labeling standards across the region are also nudging converters toward higher-specification facestocks and adhesives.
Beyond Asia-Pacific, North America and Europe are mature, innovation-led markets where demand is shaped more by sustainability and compliance than by raw volume growth. Avery Dennison has introduced recycled-content and linerless pressure-sensitive materials, and its rbDIRECT platform removes silicone release liners to cut waste and freight costs for grocery weigh-scale and parcel-sortation lines. UPM Raflatac has expanded recyclable materials and carbon-reduction initiatives, while CCL Industries has invested in digital printing and smart labeling for customized and regulated packaging. Latin America and the Middle East and Africa are expected to grow steadily as consumer goods, pharmaceutical production and retail networks expand.
Top 15 Trends in the Self-Adhesive Labels Market
Linerless labels remove the silicone release liner, cutting waste and freight while fitting more labels per roll, though applicator retrofits and recycling guidance remain hurdles.
Brands now face pressure to prove recyclability, so converters are launching recycled-content facestocks and recyclable adhesives that align with circular-packaging goals and stricter lifecycle scrutiny.
RFID, NFC, and connected labels give brands real-time traceability and consumer engagement, opening data-driven revenue streams beyond simple product identification across retail and logistics networks.
Rising parcel volumes in Asia-Pacific and beyond are boosting demand for durable, variable-data shipping labels that support sortation, tracking and faster fulfilment in online retail.
Digital printing lets converters run short batches, personalize designs and change artwork, helping brands respond to customization demand while reducing inventory, setup waste and time-to-shelf.
Growing microwave and ready-meal consumption drives heat-resistant hot-melt labels engineered to withstand reheating temperatures without peeling, discoloration, or adhesive failure on packaging.
List of Top 25 Companies Leading the Self-adhesive Labels Market
1. Avery Dennison Corporation
World leader in pressure-sensitive adhesive materials and functional labeling technologies.
Founded: 1935 | HQ: Mentor, Ohio, USA.
Why It Ranks: Unmatched market share, extensive patents, and a pioneer in labeling science.
Regional Dominance: Strongest market presence across North America, Europe, and Asia-Pacific regions.
Product Line: Pressure-sensitive facestocks, RFID labels, graphic materials, and industrial tapes.
2. UPM Raflatac
A major supplier specializing in sustainable self-adhesive labeling materials.
Founded: 1970 | HQ: Helsinki, Finland.
Why It Ranks: Recognized leader in sustainable label facestocks and circular packaging solutions.
Regional Dominance: Strong dominant market position across Europe, North America, and Asia.
Product Line: Paper and film label stocks, linerless labels, and adhesives.
3. CCL Industries Inc.
World’s largest converter of pressure-sensitive and specialty labels for corporations.
Founded: 1951 | HQ: Toronto, Ontario, Canada.
Why It Ranks: Unrivaled footprint in label converting for healthcare and consumer packaging.
Regional Dominance: Strong market operations throughout North America, Europe, and Latin America.
Product Line: Expanded-content labels, pressure-sensitive labels, sleeve labels, and aluminum cans.
4. 3M Company
innovator known for ultra-durable, high-performance technical self-adhesive solutions.
Founded: 1902 | HQ: St. Paul, Minnesota, USA.
Why It Ranks: Industry benchmark for harsh-environment, chemical-resistant, and high-tack adhesive technology.
Regional Dominance: leadership presence spanning North America, Europe, and Asia-Pacific.
Product Line: Industrial labels, tamper-evident tapes, graphic films, and specialty adhesives.
5. Multi-Color Corporation (MCC)
One of the largest label solution providers serving packaging brands.
Founded: 1916 | HQ: Batavia, Ohio, USA.
Why It Ranks: Exceptional breadth in premium label printing techniques across diverse markets.
Regional Dominance: Extensive converting manufacturing network across North America, Europe, and Australasia.
Product Line: Pressure-sensitive, in-mold, shrink sleeve, and cut-and-stack label products.
6. Lintec Corporation
Premier developer of specialized adhesive materials and pressure-sensitive label stocks.
Founded: 1934 | HQ: Tokyo, Japan.
Why It Ranks: High reputation for precision engineering and advanced specialty adhesive chemistry.
Regional Dominance: Dominant market leadership across Japan and the Asia-Pacific region.
Product Line: Adhesive paper and film, barcode labels, and electronic materials.
7. H.B. Fuller Company
Premier provider of specialized adhesives used across packaging converters.
Founded: 1887 | HQ: St. Paul, Minnesota, USA.
Why It Ranks: Key adhesive formulation partner for major label manufacturers worldwide.
Regional Dominance: Robust distribution presence across the Americas, Europe, and Asia.
Product Line: Hot-melt adhesives, water-based adhesives, and pressure-sensitive labeling polymers.
8. Mondi Group
Major international packaging and paper supplier delivering sustainable release liners.
Founded: 1967 | HQ: Weybridge, United Kingdom.
Why It Ranks: Crucial supplier of high-quality release liners essential for adhesive labels.
Regional Dominance: Dominant manufacturing and distribution network across Europe and Africa.
Product Line: Siliconized release liners, functional films, and sustainable paper packaging.
9. Coveris Holdings S.A.
Flexible packaging manufacturer producing advanced pressure-sensitive and linerless labels.
Founded: 2013 | HQ: Vienna, Austria.
Why It Ranks: European pioneer in waste-reducing linerless label systems and packaging.
Regional Dominance: Strong manufacturing operational presence throughout Western and Central Europe.
Product Line: Linerless labels, pressure-sensitive labels, high-barrier films, and flexible bags.
10. Fedrigoni Group (RITRAMA)
Italian specialty paper producer that expanded capabilities by acquiring Ritrama.
Founded: 1888 | HQ: Verona, Italy.
Why It Ranks: World leader in luxury self-adhesive labels for wines and cosmetics.
Regional Dominance: Leading market share in Europe, expanding into North and South America.
Product Line: Premium self-adhesive papers, roll label materials, and visual communications graphics.
Conclusion
The self-adhesive labels market remains a critical pillar of packaging, driven by e-commerce expansion, stringent traceability regulations, and sustainability demands. Industry leaders are continually advancing material science through recyclable facestocks, linerless formats, and high-performance adhesives. As automation accelerates across supply chains, key market players positioned in sustainable materials and digital variable-data printing will maintain a strong competitive edge in the evolving market.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


