
Oct 01, 2026
By Transpire Insight
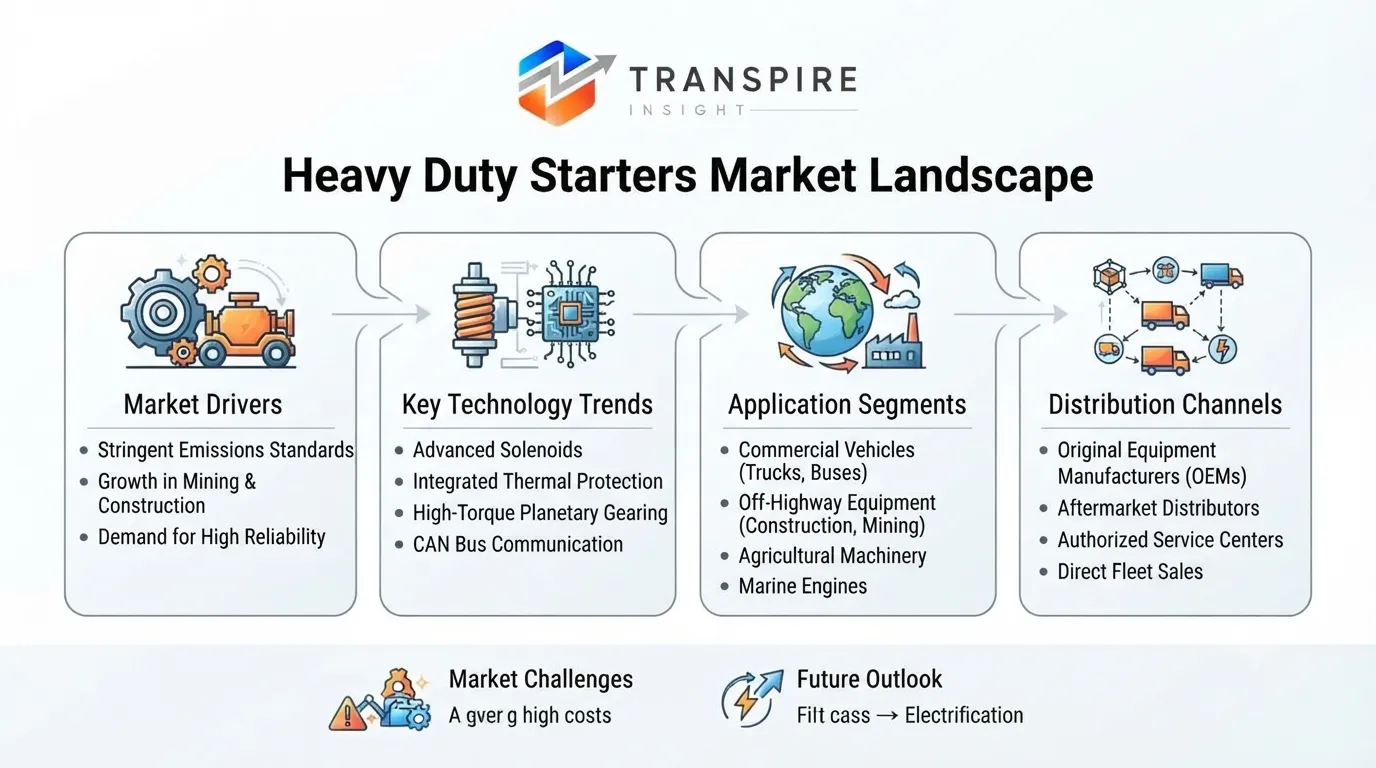
Description
According to a research report published by Transpire Insight, the heavy-duty starters market size is projected to grow from USD 5.4 billion in 2026 to USD 6.68 billion by 2035, at a CAGR of 6.22% during the forecast period 2027-2035. The need to meet the increasing demand for expansion in heavy construction, commercial logistics, mining operations, and stringent emission regulations further requires high-torque, long-lasting heavy-duty starters designed to reliably start heavy-duty equipment in harsh, cold, and demanding applications.
Introduction
Heavy-duty starters are of vital importance to various commercial transportation, agricultural, construction, and marine applications. Rugged starter motors are built to provide high cranking torque in large-displacement diesel and gas engines while operating in harsh environments with high vibrations and extreme temperatures. As the world's infrastructure expands, stringent vehicle emission regulations and fleet modernizations drive ongoing innovation for key industry manufacturers with lightweight, high-efficiency starters to enable heavy commercial vehicles and off-highway equipment around the world.
Recent Development News
February 2026: BorgWarner expanded its commercial vehicle lineup by launching the 150MT heavy-duty starter, offering enhanced high-torque cranking performance, extended durability, and over-crank protection for large diesel engines.
February 2026: Valeo expanded its production of next-generation heavy-duty starter-generators and micro-hybrid energy management units to meet rising demand for reduced commercial emissions.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Heavy Duty Starters Market Size & Statistics
The Market Size for Heavy Duty Starters Was Estimated to be Worth USD 5.4 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 6.22% between 2026 and 2035.
The Heavy Duty Starters Market Size is anticipated to reach USD 6.68 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 38% of the heavy-duty starters market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 6.2% in the heavy-duty starters market.
Regional Growth and Demand Analysis by Transpire Insight
North America continues to lead demand for heavy-duty starters, supported less by mass production and more by fleet modernization and equipment replacement cycles. Rising investment in electric commercial fleets has pushed operators toward electronic starter systems that integrate cleanly with newer vehicle electronics, while demand for premium starters, predictive maintenance services, and fleet management solutions remains distinct from other regions. Stringent emission norms across the U.S. and Canada are also steering manufacturers toward more efficient, energy-saving starter designs, reinforcing the region's position as the largest revenue contributor even as unit growth slows relative to emerging markets.
Asia-Pacific is expanding faster than any other region, propelled by accelerating industrialization, construction and mining activity, and rising commercial vehicle manufacturing in China and India. A wave of infrastructure development projects across Asian countries has directly boosted procurement of heavy equipment and, by extension, starter systems. Extensive automotive supply chains, cost-effective manufacturing bases, and growing investment in mining, logistics, and industrial projects give the region a structural growth advantage. As manufacturers expand local production capacity to serve this demand, Asia-Pacific is set to narrow the gap with North America over the coming years.
Top 15 Trends in the Heavy Duty Starters Market
Shift toward electronic and gear-reduction starter systems
Manufacturers are replacing traditional starters with electronic and gear-reduction variants, since these designs deliver stronger torque, lighter weight, and better fuel efficiency across demanding applications.
Growing adoption of IIoT-enabled predictive maintenance features
Connected starters now feed real-time performance data into IIoT platforms, letting fleet operators predict failures early and schedule preventive servicing, cutting costly unplanned downtime significantly.
Expansion of aftermarket replacement and refurbishment services
Periodic replacement needs keep the aftermarket segment growing fast, as fleet operators favor refurbished and remanufactured starters over costly new units for routine fleet maintenance.
Stricter emission norms driving efficient starter technology
Tightening emission regulations across major markets are pushing manufacturers toward more efficient starter technologies, reducing idle energy loss and supporting compliance with stricter fuel mandates.
Rising commercial vehicle production boosting starter demand
Rising output of trucks, buses, and construction machinery worldwide is directly increasing starter installations, since every new heavy vehicle requires a reliable, high-torque engine-starting system.
Fleet modernization programs replacing aging starter units
Aging commercial fleets across developed markets are being upgraded with modern starter units, as operators prioritize reliability, lower maintenance costs, and reduced vehicle downtime overall.
List of Top 25 Companies Leading the Heavy Duty Starters Market
Primary supplier of heavy-duty starters for commercial and industrial vehicles.
Founded: 1928 | HQ: Auburn Hills, Michigan, USA.
Why It Ranks: Market leadership via the iconic, reliable Delco Remy heavy-duty line.
Regional Dominance: Strong leadership across North America, Europe, and Asia-Pacific fleet sectors.
Product Line: 39MT, 44MT, and 150MT heavy-duty starter motors for commercial trucks.
Engineering pioneer producing durable automotive and heavy-duty starter solutions globally.
Founded: 1886 | HQ: Gerlingen, Germany.
Why It Ranks: Unmatched engineering scale, OEM presence, and advanced technological reliability.
Regional Dominance: Dominates European automotive and industrial heavy-equipment starter motor markets.
Product Line: HEF109, KB, and QB series heavy-duty starters for trucks.
Leading innovator in compact, high-output starter motors for heavy machinery.
Founded: 1949 | HQ: Kariya, Aichi, Japan.
Why It Ranks: Superior manufacturing efficiency and massive supply share among Asian OEMs.
Regional Dominance: Extremely strong market footprint across Asia-Pacific and North American markets.
Product Line: P series heavy-duty gear-reduction starter motors for commercial vehicles.
Renowned for rugged high-torque starters designed for mining and construction equipment.
Founded: 1921 | HQ: Tokyo, Japan.
Why It Ranks: Strong OEM relationships and elite thermal durability in industrial starters.
Regional Dominance: Major dominance across Asia-Pacific industrial and heavy equipment segments.
Product Line: High-torque direct-drive and reduction-type starters for commercial applications.
leader in start-stop technologies and advanced starter-generator units.
Founded: 1923 | HQ: Paris, France.
Why It Ranks: Technological leadership in high-efficiency electrification and reduced emissions technology.
Regional Dominance: Dominates European light-to-heavy commercial vehicle starter motor distribution channels.
Product Line: Heavy-duty reinforced starter motors and integrated starter-generators for commercial fleets.
Formed from Bosch’s starter motor division, specializing in starter manufacturing excellence.
Founded: 2018 | HQ: Stuttgart, Germany.
Why It Ranks: Inherited decades of specialized German engineering knowledge for commercial vehicle starters.
Regional Dominance: Strong presence across European and Latin American commercial vehicle sectors.
Product Line: Heavy-duty starters for commercial trucks, buses, and agricultural machinery.
Powers heavy-duty industrial machinery and commercial fleets with integrated power systems.
Founded: 1919 | HQ: Columbus, Indiana, USA.
Why It Ranks: Massive brand synergy with world-leading diesel engine manufacturing operations globally.
Regional Dominance: Deep market penetration across North American and international heavy-truck industries.
Product Line: Integrated electrical starters for industrial diesel engines and heavy equipment.
Specialized manufacturer of heavy-duty electrical components for military and commercial transport.
Founded: 1911 | HQ: Novi, Michigan, USA.
Why It Ranks: Preferred supplier for high-spec military and extreme-duty commercial applications worldwide.
Regional Dominance: Highly dominant in North American defense and heavy transportation sectors.
Product Line: M100D, M110J, and MS1 heavy-duty starter motor product lines.
Key Japanese manufacturer focusing on heavy industrial machinery and diesel starters.
Founded: 1933 | HQ: Kanagawa, Japan.
Why It Ranks: Trusted reputation for high reliability in off-highway and construction applications.
Regional Dominance: Strong market hold in Asia-Pacific construction and marine starter sectors.
Product Line: Waterproof, high-torque reduction starters for heavy industrial construction equipment.
One of China’s largest domestic manufacturers of automotive and commercial starters.
Founded: 1994 | HQ: Beijing, China.
Why It Ranks: Unmatched low-cost volume production serving domestic commercial vehicle manufacturing hubs.
Regional Dominance: Comprehensive dominance across China and expanding emerging market export networks.
Product Line: Heavy truck starters, bus starters, and diesel engine starting systems.
Conclusion
Heavy-duty starters are still significant in the transportation industry for logistics, construction, and industrial applications. As emissions levels are increasing and the infrastructure is being heavily invested in, key manufacturing companies are aggressively increasing their high-torque, cold-weather, and start-stop starter line products. Future trends will see lightweight designs, improved integration of electronics, and micro-hybrid capabilities as key market drivers, as key market leaders continue to ensure performance at a level of resilience appropriate to heavy-duty diesel and hybrid commercial applications all over the world.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


