
Oct 07, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the data center construction market size is projected to grow from USD 293.65 billion in 2026 to USD 691.33 billion by 2035, at a CAGR of 12.9% during the forecast period 2027-2035. Exponential growth in generative AI workloads, rapid cloud computing migration, rising demand for edge processing, and massive investments in high-density rack cooling infrastructure drive data center construction.
Introduction
The data center construction market is undergoing an unprecedented transformation driven by the digital economy's expanding computational requirements. Hyperscalers, colocation operators, and enterprise entities are rapidly scaling physical facilities to host high-density AI clusters and cloud architectures. Groundbreaking innovations in power delivery, liquid cooling, and modular designs have become vital to support continuous expansion, positioning civil engineering and general contracting firms as core enablers of modern technological growth.
Recent Development News
January 2026: Record-breaking U.S. data center construction starts reached $25.2 billion in a single month, marking the highest monthly figure recorded to date and driven by groundbreaking on 20 major projects.
March 2026: Google and Adani announced a major partnership under a $100 billion AI infrastructure plan to build a gigawatt-scale, sustainable data center campus in Visakhapatnam, India.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Data Center Construction Market Size & Statistics
The Market Size for Data Center Construction Was Estimated to be Worth USD 293.65 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 12.9% between 2026 and 2035.
The Data Center Construction Market Size is anticipated to reach USD 691.33 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 40.9% of the data Center Construction market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 9.71% in the Data Center Construction market.
Regional Growth and Demand Analysis by Transpire Insight
North America continues to anchor data center construction activity, driven by hyperscale operators such as Microsoft, Amazon, and Google expanding cloud and AI compute campuses across established corridors like Northern Virginia and Texas. Grid interconnection queues and power availability have become the binding constraint on new builds, pushing developers toward markets with abundant energy and prompting federal-level attention, including a pledged $20 billion push to accelerate domestic data center construction. Rising demand for AI-ready, high-density infrastructure is also reshaping electrical and cooling budgets across the region, with operators favoring modular and prefabricated designs to compress build timelines amid tight equipment and labor supply.
Asia-Pacific's growth is led by China and India, where government-backed cloud deployment initiatives and rapid digitalization are fueling sustained construction pipelines. Operators such as GDS Holdings have posted strong revenue growth on the back of rising demand for data services, while Japan and South Korea continue attracting hyperscale investment as interconnection hubs. Europe, meanwhile, is seeing a strategic shift toward regional digital autonomy, with Pan-European data center corridors and brownfield upgrades in markets like Germany and the UK reinforcing both new builds and secure domestic infrastructure.
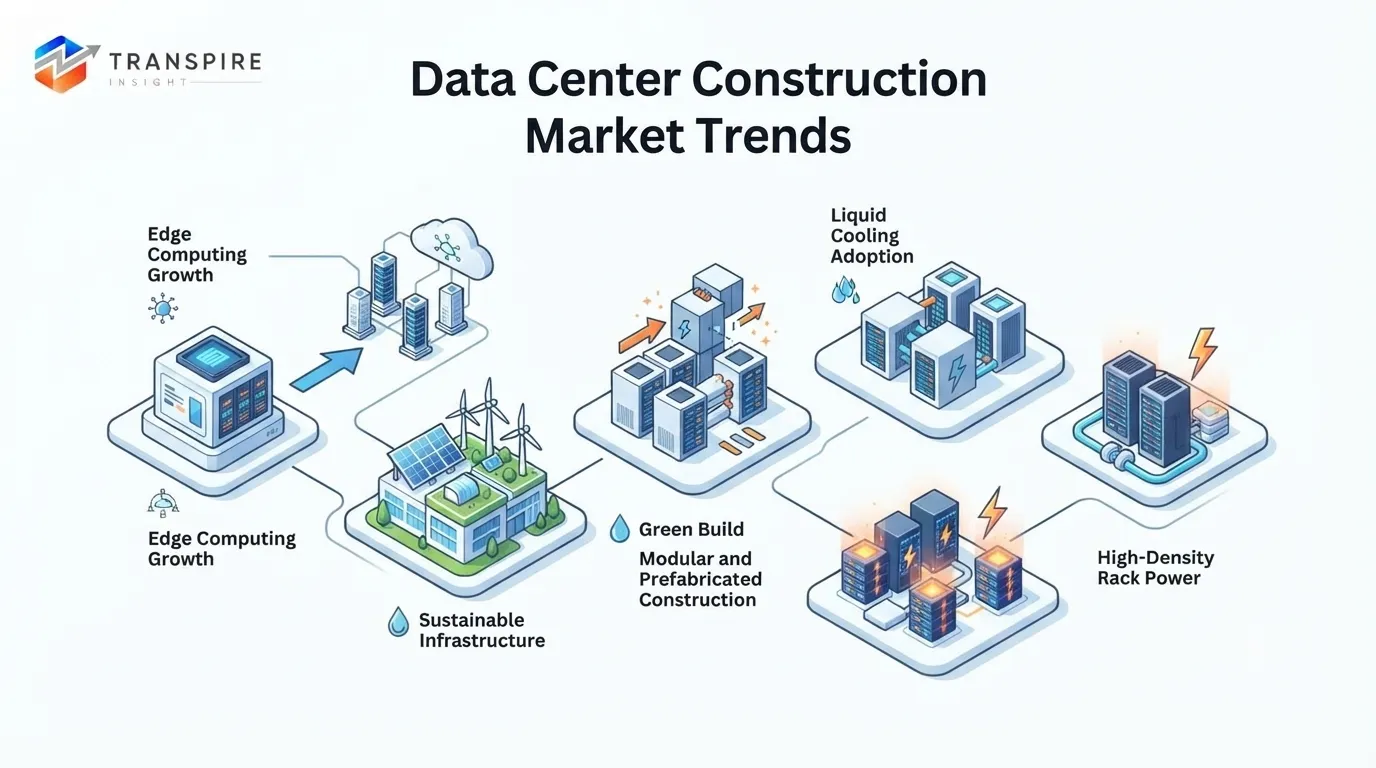
Top 15 Trends in the Data Center Construction Market
Hyperscale Campus Expansion
Microsoft, Amazon, and Google continue steadily and rapidly expanding hyperscale campuses across North America and Asia-Pacific to meet surging cloud, storage, and AI compute demand.
AI-Driven High-Density Demand
GPU-intensive AI training and inference workloads are driving demand for high-density racks, advanced power delivery, and specialized cooling across new hyperscale and colocation facilities worldwide.
Modular and Prefabricated Construction
Prefabricated and modular builds let operators consistently deploy data center capacity much faster, standardize designs, cut labor costs, and respond quickly to surging demand everywhere.
Liquid Cooling Adoption
Air cooling can't handle dense AI racks, so operators increasingly adopt liquid and immersion cooling systems to manage heat, boost efficiency, and support GPU density.
Power and Grid Constraints
Limited grid capacity and lengthy utility interconnection queues are steadily pushing developers toward markets offering abundant power, on-site generation, and flexible energy procurement strategies worldwide.
Small Modular Reactors
Developers increasingly view small modular reactors as a viable, carbon-free option for delivering reliable, gigawatt-scale baseload power to meet fast-growing data center demand today worldwide.
List of Top 25 Companies Leading the Data Center Construction Market
1. Turner Construction
Leading general contractor delivering massive hyperscale and enterprise infrastructure facilities.
Founded: 1902 | HQ: New York, NY, USA.
Why It Ranks: World-class execution capacity enables delivery of massive, multi-billion-dollar hyperscale digital campuses globally.
Regional Dominance: North America leads primary delivery operations across expanding primary hyperscale markets.
Product Line: Full-service general contracting, structural framing, and turnkey facility construction services.
2. DPR Construction
Technical builder specializing in highly complex, technical, and sustainable data centers.
Founded: 1990 | HQ: Redwood City, CA, USA.
Why It Ranks: Deep technical expertise and advanced prefabrication excel in complex mission-critical environments.
Regional Dominance: North American core markets dominate major technology hubs and hyperscale regions.
Product Line: Mission-critical construction, advanced prefabrication, and complex structural building solutions.
3. AECOM
Fully integrated infrastructure firm supplying engineering, architecture, and construction management solutions.
Founded: 1990 | HQ: Dallas, TX, USA.
Why It Ranks: engineering integration delivers complete lifecycle management for modern data infrastructure facilities.
Regional Dominance: operations lead major projects across the Americas, Europe, and Asia-Pacific.
Product Line: End-to-end architecture, environmental engineering, and mission-critical construction management solutions.
4. Jacobs Solutions
provider of technical, professional, and full-scale construction management services.
Founded: 1947 | HQ: Dallas, TX, USA.
Why It Ranks: End-to-end engineering excellence seamlessly integrates liquid cooling and sustainable utility grid connections.
Regional Dominance: The North American market represents the primary focus, alongside growing European expansion projects.
Product Line: Engineering design, project management, and specialized mission-critical infrastructure consulting services.
5. Mortenson
Pioneer in advanced prefabrication and modular techniques for enterprise data builds.
Founded: 1954 | HQ: Minneapolis, MN, USA.
Why It Ranks: Rapid deployment capabilities leverage advanced modular assembly and integrated off-site prefabrication techniques.
Regional Dominance: North American regional hubs dominate primary development and project execution pipelines.
Product Line: EPC delivery, prefabrication modular assembly, and renewable microgrid system integration.
6. Skanska
International construction firm known for sustainable building practices and green designs.
Founded: 1887 | HQ: Stockholm, Sweden.
Why It Ranks: Industry-leading sustainable building practices deliver carbon-neutral certified digital infrastructure and facilities globally.
Regional Dominance: European markets dominate, along with strong North American mission-critical operational footprints.
Product Line: Sustainable general contracting, civil works, and eco-friendly infrastructure building systems.
7. Bechtel Corporation
Engineering and construction titan building mega-scale energy and digital infrastructure projects.
Founded: 1898 | HQ: Reston, VA, USA.
Why It Ranks: Industrial-scale engineering capabilities execute massive gigawatt-scale data campuses and utility infrastructure projects.
Regional Dominance: project operations dominate large-scale industrial and utility infrastructure developments.
Product Line: Heavy EPC contracting, utility-scale power integration, and massive civil engineering.
8. JE Dunn Construction
Top-tier builder driving efficiency in mission-critical facilities via advanced prefabrication.
Founded: 1924 | HQ: Kansas City, MO, USA.
Why It Ranks: Lean building methodology and BIM tools enable rapid execution of resilient facilities.
Regional Dominance: North America retains a strong presence across central and eastern technology corridors.
Product Line: Mission-critical construction management, lean prefabrication, and general contracting services.
9. Fluor Corporation
engineering giant delivering comprehensive procurement, construction, and maintenance services.
Founded: 1912 | HQ: Irving, TX, USA.
Why It Ranks: procurement networks ensure fast-track construction delivery for large industrial computer facilities.
Regional Dominance: delivery capabilities cover Europe, Asia-Pacific, and North American energy markets.
Product Line: Full EPC management, supply procurement, and heavy structural engineering.
10. Structure Tone (STO Building Group)
Leading interior fit-out and mission-critical construction specialist for high-tech facilities.
Founded: 1971 | HQ: New York, NY, USA.
Why It Ranks: White-space fit-out specialization allows rapid deployment of critical interior electrical/mechanical infrastructure.
Regional Dominance: North America leads construction presence, along with expanding United Kingdom operations.
Product Line: Interior white-space construction, mission-critical fit-outs, and advanced MEP retrofits.
Conclusion
The data center construction market remains an essential foundation of the digital era, fueled by relentless demand for cloud capabilities and artificial intelligence infrastructure. General contractors and engineering firms are adapting by prioritizing modular construction, renewable energy integration, and direct-to-chip cooling. As grid constraints intensify globally, contractors capable of seamlessly integrating high-density power systems will lead the market's ongoing expansion.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


