
Oct 14, 2026
By Transpire Insight
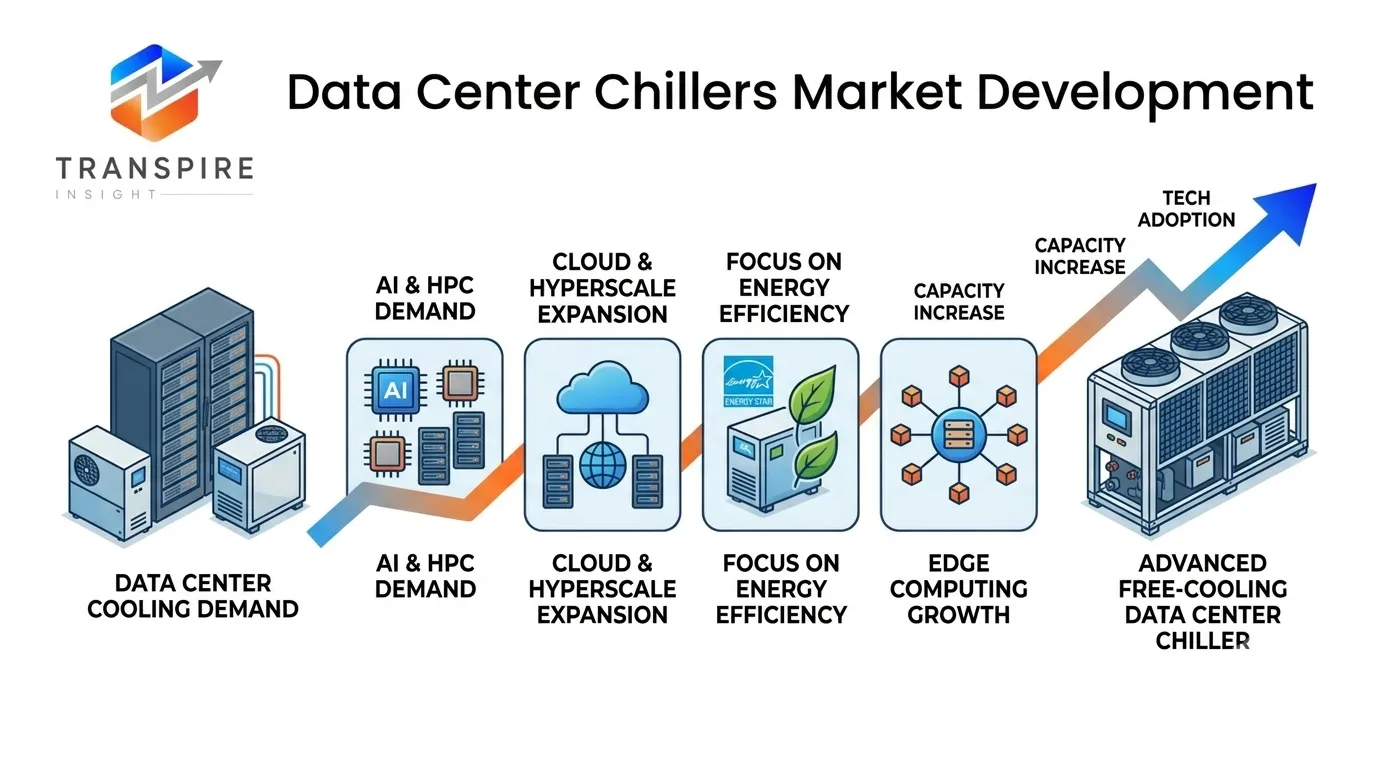
Description
According to a research report published by Transpire Insight, the data center chillers market size is projected to grow from USD 12.9 billion in 2026 to USD 28.7 billion by 2035, at a CAGR of 11.72% during the forecast period 2027-2035. Surging AI rack densities, continuous hyperscale data center expansion, strict PUE efficiency mandates, and rapid transitions toward low-GWP refrigerants and water-conserving, oil-free chillers drive robust market growth.
Introduction
The rapid rise of high-density AI workloads, cloud computing, and hyperscale facilities is expanding the data center chillers market. Chillers provide mission-critical heat extraction to ensure optimal server performance and maintain uptime. Driven by strict sustainability mandates, operators are rapidly replacing legacy cooling systems with high-efficiency, oil-free, magnetic-bearing water-cooled and air-cooled chillers, positioning liquid-to-air cooling architectures at the heart of modern data center infrastructure.
Recent Development News
September 2026: Trane Technologies completed a laboratory demonstration of an 800-volt direct current (DC) cooling architecture integrated into a high-efficiency chiller platform to optimize energy management in AI data centers.
September 2026: Vertiv announced targeted capital investments to double its chiller manufacturing capacity by year-end and agreed to acquire EMEA-based King Environmental Services to strengthen fluid management and load testing.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Data Center Chillers Market Size & Statistics
The Market Size for the Data Center Chillers Was Estimated to be Worth USD 12.9 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 11.72% between 2026 and 2035.
The Data Center Chillers Market Size is anticipated to reach USD 28.7 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 42% of the data center chillers market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 19% in the data center chillers market.
Regional Growth and Demand Analysis by Transpire Insight
North America leads the data center chillers market because of its dense concentration of hyperscale, colocation, and enterprise facilities, backed by a mature cloud, AI, and high-performance computing ecosystem. LG Electronics announced a supply deal for a large U.S. data center under construction, covering more than 100 chillers with a combined capacity of up to 50,000 tons of refrigeration. investment momentum is also strong: UNCTAD reports that data centers accounted for over one-fifth of all greenfield investments worldwide, totaling more than USD 270 billion. Europe follows a regulation-led path, where the EU Green Deal, tightening PUE and ERF targets, low-GWP refrigerant requirements, and waste heat recovery for municipal use push operators toward high-efficiency water-cooled chillers. Consolidation is also visible, as Munters acquired Italian chiller maker Geoclima to strengthen its data center cooling portfolio.
Asia Pacific is the fastest-growing region, driven by digitalization programs, e-commerce expansion, corporate cloud adoption in China and India, and government focus on sovereign computing and local digital infrastructure. Regional demand is shaped by water availability, with northern China leaning toward air-cooled chillers to conserve water, while large campuses elsewhere continue to favor water-cooled plants for efficiency. Suppliers are localizing their offerings: Carrier added a new oil-free data center model to its USX EDGE series in Japan, a market valued at around USD 250 million. As AI workloads raise rack densities, operators across the region are also specifying chillers that support liquid cooling and warm-water loops. Growth remains strongest in edge and colocation deployments, where compact, modular chiller plants help operators add capacity quickly.
Top 15 Trends in the Data Center Chillers Market
AI training clusters generate far higher heat loads than conventional servers, pushing operators toward liquid cooling loops that depend on dedicated chillers for precise temperatures.
Hyperscale campuses need multi-megawatt cooling plants, so operators order large-capacity chillers in bulk, as seen when LG Electronics secured a contract covering over 100 chillers.
Water-cooled chillers deliver higher heat transfer efficiency and scalability, making them the preferred choice for hyperscale and colocation sites prioritizing energy savings at multi-megawatt scale.
Oil-free magnetic-bearing compressors cut power draw markedly at part load, suiting warm-water AI loops; Carrier recently added an oil-free data center chiller model in Japan.
Water scarcity concerns in regions like the Western U.S. and northern China are steering operators toward air-cooled chillers that conserve water and speed up installation.
Tightening PUE and ERF targets under the EU Green Deal push European operators toward high-efficiency chillers, low-GWP refrigerants, and waste heat recovery for municipal heating.
List of Top 25 Companies Leading the Data Center Chillers Market
1. Vertiv
High-density thermal management systems purpose-built for hyperscale and AI facilities.
Founded: 1965 | HQ: Westerville, Ohio, USA.
Why It Ranks: Dominates mission-critical data center infrastructure with specialized, AI-ready liquid cooling solutions.
Regional Dominance: Strong market presence across North America, Europe, Asia-Pacific, and Latin America.
Product Line: Liebert AFC air-cooled chillers, Liebert HPC water-cooled chillers, and CDUs.
2. Trane Technologies
Innovator in ultra-high-efficiency centrifugal and magnetic-bearing oil-free chiller designs.
Founded: 1913 | HQ: Swords, Ireland.
Why It Ranks: Market leader in low-GWP, highly efficient chillers for hyperscale applications.
Regional Dominance: Highly dominant across North America, Europe, and Asia-Pacific regional commercial networks.
Product Line: CenTraVac centrifugal chillers, Sintesis air-cooled chillers, and 800-volt DC cooling.
3. Johnson Controls (YORK)
thermal management pioneer advancing low-energy waste-heat recovery and absorption technology.
Founded: 1885 | HQ: Cork, Ireland.
Why It Ranks: Extensive YORK chiller installations provide unmatched reliability in mission-critical applications.
Regional Dominance: stronghold spanning North America, Europe, the Middle East, and Asia-Pacific.
Product Line: YORK YK centrifugal chillers, YVAA variable-speed chillers, and absorption chillers.
4. Carrier Corporation
Pioneer in HVAC equipment offering advanced AquaEdge magnetic-bearing, oil-free water chillers.
Founded: 1915 | HQ: Palm Beach Gardens, Florida, USA.
Why It Ranks: High thermal efficiency ratings make Carrier a top pick for data center operators.
Regional Dominance: Leading market presence across the Americas, Europe, Asia-Pacific, and Middle East operations.
Product Line: AquaEdge 19DV water-cooled chillers and AquaSnap air-cooled liquid scroll chillers.
5. Daikin Industries
World's largest HVAC manufacturer, leading variable-refrigerant and magnetic-bearing chiller technology worldwide.
Founded: 1924 | HQ: Osaka, Japan.
Why It Ranks: World-class inverter technology drastically reduces annual energy overhead in data centers.
Regional Dominance: Dominates Asia-Pacific, with rapidly growing market penetration in Europe and North America.
Product Line: Daikin Applied oil-free centrifugal chillers and Pathfinder air-cooled screw chillers.
6. Schneider Electric
leader in digital automation and data center physical infrastructure thermal systems.
Founded: 1836 | HQ: Rueil-Malmaison, France.
Why It Ranks: Seamless integration of chillers with EcoStruxure management software optimizes overall power usage.
Regional Dominance: Massive market share across Europe, North America, the Middle East, and Asia-Pacific.
Product Line: Uniflair air-cooled and water-cooled chillers, CRAH units, and in-row coolers.
7. Stulz GmbH
Specialized precision cooling manufacturer tailored specifically for critical data center environmental control.
Founded: 1947 | HQ: Hamburg, Germany.
Why It Ranks: Custom-engineered modular chillers deliver exact environmental parameters for customized data centers.
Regional Dominance: Strong presence throughout Europe, North America, India, and East Asian markets.
Product Line: CyberCool 2 air-cooled chillers, CyberCool Indoor water-cooled units, and CRAH.
8. Mitsubishi Electric Corporation
technology giant producing ultra-reliable chillers and precision environmental control equipment globally.
Founded: 1921 | HQ: Tokyo, Japan.
Why It Ranks: Exceptional hardware reliability and advanced inverter scroll compressor efficiency set standards.
Regional Dominance: Market leader in East Asia and rapidly expanding presence across European markets.
Product Line: Climaveneta i-FX air-cooled chillers and MECH-i-Water-Cooled high-efficiency centrifugal series.
9. Airedale International Air Conditioning (Modine)
Specialist in data center cooling, delivering tailored eco-friendly chillers with integrated free-cooling systems.
Founded: 1974 | HQ: Leeds, United Kingdom.
Why It Ranks: Expertise in free-cooling chillers significantly decreases power consumption in European climates.
Regional Dominance: Dominates the United Kingdom and Western Europe, expanding across North America.
Product Line: TurboChill oil-free chillers, DCS chillers, and InRak CRAH equipment systems.
10. Legrand (Nortek Air Solutions)
Infrastructure specialist offering custom packaged chillers and air handlers for massive data centers.
Founded: 1860 | HQ: Limoges, France.
Why It Ranks: Tailored modular cooling equipment serves major enterprise hyperscalers seeking turnkey deployment.
Regional Dominance: Established power base in North America, Europe, and select Latin American markets.
Product Line: Custom air-cooled chillers, clean-room cooling systems, and server-rack cooling arrays.
Conclusion
As AI compute and rack power densities soar, data center chillers remain central to thermal management architectures. Market leaders are continually innovating with magnetic-bearing compressors, low-GWP refrigerants, and intelligent free-cooling systems to optimize Power Usage Effectiveness (PUE). Combining modular air-cooled and liquid-cooled chiller infrastructure equips operators to balance performance, environmental compliance, and energy savings, laying a sustainable foundation for next-generation digital infrastructure.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


