
Oct 22, 2026
By Transpire Insight
Description
According to a research report published by Transpire Insight, the automotive GenAI copilot market size is projected to grow from USD 2.26 billion in 2026 to USD 11.69 billion by 2035, at a 26.18% CAGR during the 2027-2035 forecast period. Rising consumer demand for personalized, conversational in-cabin experiences and the accelerated deployment of software-defined, highly autonomous vehicles drive rapid adoption of generative AI copilots across modern automotive platforms.
Introduction
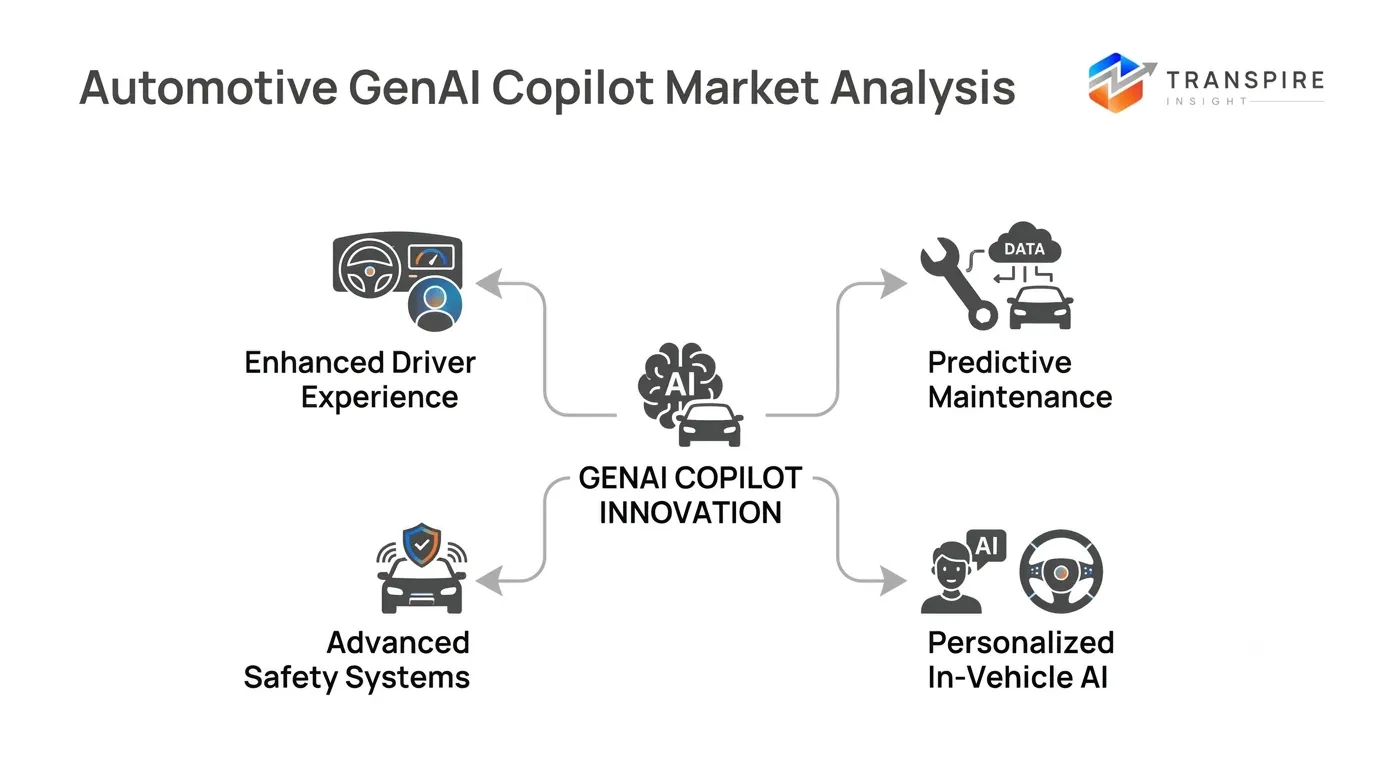
The Automotive GenAI Copilot market represents a transformative leap in connected mobility, elevating traditional voice assistants into proactive, context-aware intelligence hubs. By fusing large language models, advanced computer vision, and real-time vehicle telematics, these natural-language copilots orchestrate adaptive infotainment, predictive maintenance, and complex automated driving tasks. As automakers transition toward software-defined architectures, GenAI copilots have emerged as a core competitive differentiator for next-generation passenger and commercial vehicles.
Recent Development News
January 2026: Texas Instruments launched its next-generation TDA5 System-on-Chip (SoC) family featuring high-efficiency edge AI accelerators capable of up to 1,200 TOPS to power multi-modal in-cabin GenAI copilots and 4D radar perception.
September 2026: Microsoft unveiled an updated Copilot platform featuring autonomous "Autopilot" agentic capabilities designed to streamline end-to-end software development and deployment workflows for connected software-defined vehicle programs.
Stay Ahead of Emerging Opportunities with Expert Market Insights by Transpire Insight
Transpire Insight provides comprehensive, data-driven market intelligence to support smarter business decisions. Our research is rooted in comprehensive analysis, authoritative predictions, and industry expertise, enabling organizations to make informed decisions in rapidly evolving markets. We provide in-depth analysis of market segmentation, competitive positioning, regional trends, and emerging investment opportunities in high-growth areas. We blend accuracy with actionable intelligence, helping companies uncover new growth avenues, strengthen strategic decision-making, and stay ahead in a dynamic market.
Automotive GenAI Copilot Market Size & Statistics
The Market Size for Automotive GenAI Copilot Was Estimated to be Worth USD 2.26 Billion in 2026.
The Market Size is Going to Expand at a CAGR of 26.18% between 2026 and 2035.
The Automotive GenAI Copilot Market Size is anticipated to reach USD 11.69 Billion by 2035.
North America is projected to drive the highest demand during the forecast period, accounting for 40% of the automotive GenAI copilot market.
Asia-Pacific is projected to grow the fastest during the forecast period at a CAGR of 13% in the automotive GenAI copilot market.
Regional Growth and Demand Analysis by Transpire Insight
North America leads the market because of its high connected vehicle adoption, advanced ADAS systems, and AI-enabled in-cabin assistants. Strong OEM investments, widespread automotive AI R&D, and consumer demand for personalized, voice-controlled experiences keep demand high. The United States anchors the region, helped by strong technology infrastructure and early use of generative AI in software development. Recent industry activity shows this momentum. Qualcomm Technologies and Google Cloud expanded their partnership to deliver agentic AI for automakers, combining Google’s Automotive AI Agent with the Snapdragon Digital Chassis for conversational, hybrid edge-to-cloud in-car experiences. Visteon and TomTom also announced a collaboration on an in-car local AI conversational navigation assistant, built around a privacy-first approach. On the regulatory side, the National Highway Traffic Safety Administration proposed the AV STEP program to evaluate autonomous vehicles, which supports transparency and safety for advanced driver systems.
Asia Pacific is the fastest-growing region, driven by rising EV adoption, growing connected vehicle penetration, and supportive government initiatives for smart mobility. OEMs and tech startups are investing heavily in AI-enabled in-cabin assistants, predictive maintenance, and infotainment. China is a major force, where the Ministry of Industry and Information Technology launched a digital transformation plan mandating AI integration across R&D, production, and management, with a target of shorter product development cycles. India is also expanding quickly. Acsia Technologies launched Lila, a generative AI copilot that automates coding and speeds up automotive software development, from its new headquarters and R&D center in Thiruvananthapuram, which shows the region’s ambition to become a automotive technology hub.
Top 15 Trends in the Automotive GenAI Copilot Market
Large language models let drivers speak naturally instead of memorizing commands, making infotainment, navigation, and climate control feel truly intuitive while significantly reducing driver distraction.
Centralized compute and software-defined architectures give copilots access to vehicle data and controls, enabling deeper features and letting automakers continuously upgrade copilot intelligence over time.
Combining on-board processing with cloud models delivers fast responses and works offline, while heavier reasoning tasks use cloud power, balancing latency, cost, reliability, and privacy.
Copilots learn individual habits such as preferred routes, music, seat settings, and temperature, creating tailored cabin experiences that strengthen brand loyalty and clearly differentiate competing vehicles.
Copilots combine voice, camera, and gesture inputs to understand context, such as identifying landmarks or reading driver attention, making interactions more natural, accurate, and safer.
Copilots interpret sensor data and explain warning lights in plain language, predict component failures, and schedule service, reducing downtime and improving the overall ownership experience.
List of Top 25 Companies Leading the Automotive GenAI Copilot Market
1. Microsoft Corporation
Powers multi-modal in-cabin experiences using integrated Azure OpenAI cloud ecosystems.
Founded: 1975 | HQ: Redmond, Washington, USA.
Why It Ranks: Dominates cloud infrastructure, enterprise software, and deep automotive copilot integrations.
Regional Dominance: Strong presence across North America, Western Europe, and Asia-Pacific markets.
Product Line: Azure OpenAI Service, Microsoft Copilot Studio, and Azure Connected Vehicle Platform.
2. NVIDIA Corporation
Provides end-to-end hardware and synthetic data world models for automotive AI.
Founded: 1993 | HQ: Santa Clara, California, USA.
Why It Ranks: Unrivaled leader in high-performance GPU compute hardware and GenAI stacks.
Regional Dominance: technology market leadership across North America, Europe, and Asia-Pacific.
Product Line: NVIDIA DRIVE Thor, DRIVE Orin, and Cosmos World Foundation Models.
3. Cerence Inc.
Dedicated automotive voice and generative AI platform deployed in millions of vehicles.
Founded: 2019 | HQ: Burlington, Massachusetts, USA.
Why It Ranks: Market leader specializing exclusively in conversational, multi-modal in-cabin assistant solutions.
Regional Dominance: Deep penetration among major automotive OEMs in North America and Europe.
Product Line: Cerence Co-Pilot, Cerence Chat Pro, and Automotive Large Language Model.
4. Qualcomm Technologies, Inc.
Processes high-throughput generative AI models locally on low-power Snapdragon Cockpit chips.
Founded: 1985 | HQ: San Diego, California, USA.
Why It Ranks: Dominates modern digital cockpit processors and edge-AI compute architecture globally.
Regional Dominance: Strong strategic presence across Asia-Pacific, North America, and European manufacturing hubs.
Product Line: Snapdragon Digital Chassis, Snapdragon Cockpit Flex Platform, and Snapdragon Ride.
5. Google LLC
Integrates advanced Gemini LLM models into Android Automotive Operating System environments.
Founded: 1998 | HQ: Mountain View, California, USA.
Why It Ranks: Massive footprint in mobile, cloud ecosystem, maps, and conversational AI.
Regional Dominance: market leader across North America, Europe, and Asia-Pacific regions.
Product Line: Android Automotive OS, Gemini AI Assistant, and Google Cloud Vertex AI.
6. Robert Bosch GmbH
World's largest automotive Tier-1 supplier embedding GenAI across vehicle electronics platforms.
Founded: 1886 | HQ: Gerlingen, Germany.
Why It Ranks: Deep domain expertise in automotive systems, sensors, and OEM partnerships.
Regional Dominance: Market leader in Europe with extensive expansion across Asia and the Americas.
Product Line: Vehicle Motion Management, Mobility Cloud Services, and Smart Cockpit Systems.
7. SoundHound AI, Inc.
Delivers independent voice AI integration with generative context for connected vehicles.
Founded: 2005 | HQ: Santa Clara, California, USA.
Why It Ranks: Specialized voice recognition pioneer offering white-label dynamic generative in-vehicle assistants.
Regional Dominance: Expanding footprint across North American and European automotive original equipment manufacturers.
Product Line: SoundHound Chat AI for Automotive, SoundHound Speech AI, and Smart Answering.
8. Harman International Industries, Inc.
Samsung subsidiary specializing in connected vehicle technologies and immersive user experiences.
Founded: 1980 | HQ: Stamford, Connecticut, USA.
Why It Ranks: Prime innovator in intelligent automotive cabin design, audio, and telematics systems.
Regional Dominance: Widespread adoption across North American, European, and Asian automotive brand portfolios.
Product Line: HARMAN Ready Care, Ready Vision, and Digital Cockpit Platform solutions.
9. Baidu, Inc.
Pioneer in autonomous driving and conversational ERNIE Bot integration for vehicles.
Founded: 2000 | HQ: Beijing, China.
Why It Ranks: Unrivaled leader in China's autonomous vehicle networks and localized AI models.
Regional Dominance: Dominates the domestic Chinese market and is rapidly expanding across East Asia.
Product Line: Apollo Autonomous Driving, DuerOS for Auto, and ERNIE Speed Bot.
10. Aptiv PLC
Architects software-defined vehicle architectures and advanced perception compute systems for OEMs.
Founded: 2017 | HQ: Dublin, Ireland.
Why It Ranks: Key provider of end-to-end signal infrastructure and central vehicle compute.
Regional Dominance: Strong, balanced footprint throughout Europe, North America, and key Asian markets.
Product Line: Smart Vehicle Architecture (SVA), ADAS Controllers, and In-Cabin User Experience.
Conclusion
The Automotive GenAI Copilot market is fundamentally transforming vehicle cabin experiences and driving dynamics worldwide. As cloud giants, Tier-1 suppliers, and leading automakers collaborate, artificial intelligence transitions from basic voice commands into proactive, contextual co-piloting. Going forward, edge-computing hardware advancements and software-defined architectures will drive mass-market adoption, establishing generative AI copilots as an indispensable standard for safe, personalized, and intelligent mobility solutions across markets.


Send us a brief description of your challenge and we'll get back to you within 24 hours.

 inquiry@transpireinsight.com
 APAC:+91 7666513636
 Address


